


Installed Base Momentum And Fresh Alliances Put ASML In Focus
ASML Holding (ENXTAM:ASML) has moved back into the spotlight after Installed Base Management sales increased 31.8%, while fresh collaborations with Samsung, TSMC, Intel and Xanadu Quantum Technologies sharpen attention on its EUV and High NA roadmap.
For you as an investor, that mix of higher service activity and deepening technical partnerships affects how ASML’s existing tool fleet, and not just new system shipments, can influence future cash generation and risk.
ASML Holding’s recent collaborations with Samsung, TSMC, Intel and Xanadu have arrived while the share price has eased, with a 30-day share price return of down 3.98% and a 90-day move of down 12.67%. However, the year-to-date gain of 46.61% and 1-year total shareholder return of 83.38% still point to strong longer term momentum.
Capitalize on the same AI and lithography momentum driving ASML Holding by scanning a curated set of peers with 88 AI infrastructure stocks.ASML Holding now combines a softer 3 month share move with heavy investor gains over 1 and 3 years. Is most of the return already captured in the current €1,446 price, or does valuation still suggest upside ahead?
Most Popular Narrative: 57% Overvalued
ASML Holding last closed at €1,446, while the most followed narrative fair value sits at €920, which places the current quote well above that narrative anchor and raises sharp questions about how much of the story is already reflected in the price.
ASML’s story is one of quiet dominance at the heart of global tech. Founded in the Netherlands in 1984, ASML started as a joint venture between Philips and ASM International. Over the decades, it evolved into the sole supplier in the world of extreme ultraviolet (EUV) lithography machines, which are essential for manufacturing the most advanced semiconductor chips (such as those used in AI, smartphones, and data centers).
These machines are complex examples of advanced engineering, costing up to €350 million each, with components sourced globally and assembled with extremely tight tolerances. Only a small group of customers, including TSMC, Intel, and Samsung, can afford and operate them, giving ASML a distinctive technological position.
See why 51 investors see ASML Holding as 57% overvalued.
Result: Fair Value of €920 (OVERVALUED)
Still, tighter export controls on shipments to China and weaker demand from a few key chipmakers could quickly challenge the current ASML Holding narrative.
Find out about the key risks to this ASML Holding narrative.
Another View On ASML Holding’s Valuation
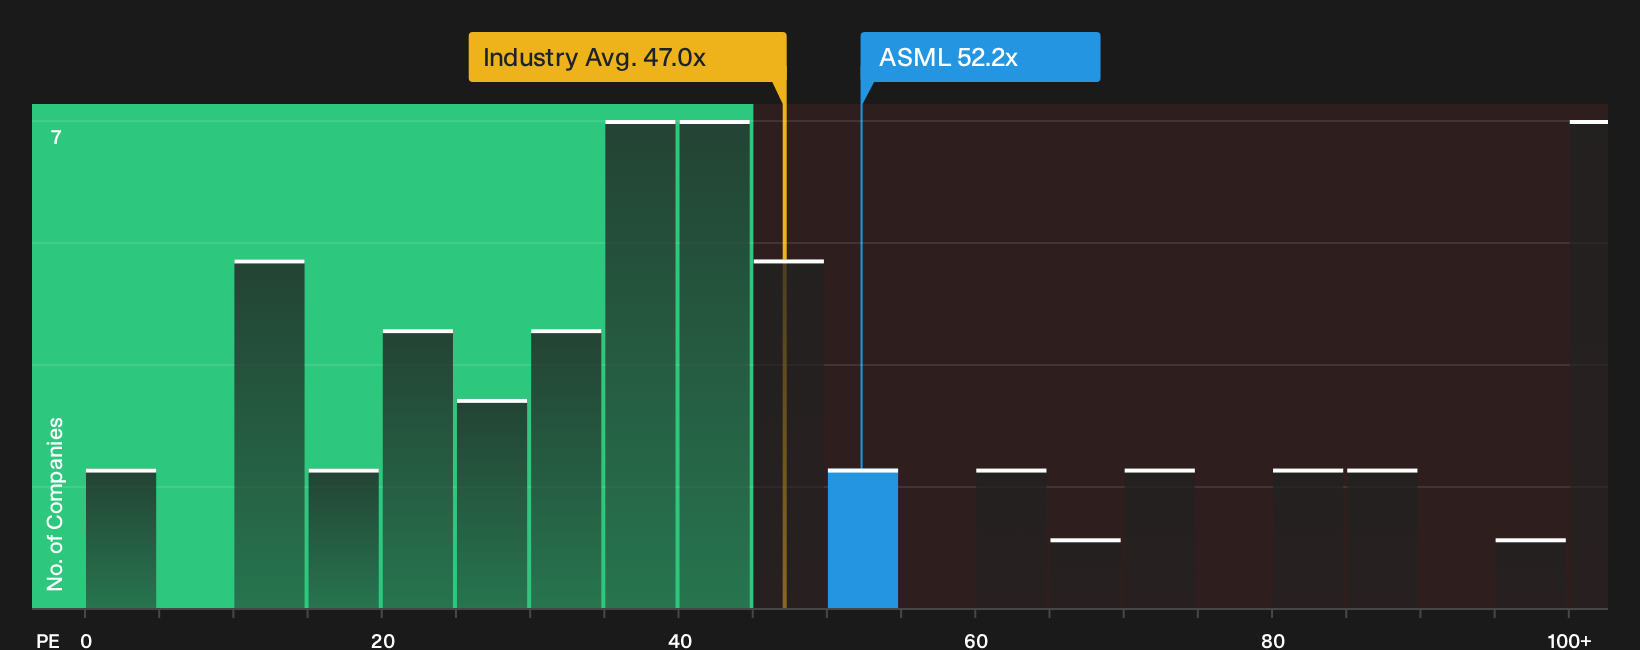
A different lens on ASML Holding comes from the P/E ratio. The stock trades at 52.2x earnings, slightly richer than both peers at 49.3x and the European semiconductor group at 51.4x, while the fair ratio sits higher at 61.3x.
That mix of a premium to peers yet a discount to the fair ratio hints at a tug of war between quality and price risk. If the market edges closer to the 61.3x fair ratio, current levels could appear conservative. If peers pull the multiple down instead, this raises the question of how comfortable an investor might be paying this valuation today given that uncertainty.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on ASML Holding so far. If you want to act before sentiment swings again, consider the trade-off yourself with 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond ASML Holding?
If ASML Holding is already on your radar, you may want to broaden your opportunity set. Fresh ideas can come from comparing strong outliers with a wider field of quality stocks.
- Target resilient compounding potential by scanning a pool of high quality companies trading below intrinsic estimates with the 182 high quality undervalued stocks.
- Prioritise income today and staying power tomorrow by reviewing a curated set of reliable payers through the 157 dividend fortresses.
- Dial down portfolio stress and focus on durability by checking a pre-filtered group of lower risk opportunities using the 226 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com