


Tariffs, higher fuel costs and “higher for longer” rates are squeezing small and mid-sized manufacturers right where it hurts, the cash cycle. That pressure is pushing more businesses toward invoice financing and working-capital lenders, which can create fresh opportunity and fresh risk for anyone looking at listed specialty finance stocks. This article walks through three U.S. invoice-financing players exposed to these macro shocks and what that could mean for their shares.
The three specialty finance stocks covered below are only a starting sample from this theme, and the full screen surfaced 1 more U.S. listed invoice and working-capital lender with an equally interesting story that is not profiled here. To go straight to the full list and identify which tickers best fit your own risk and return playbook, analyze the Publicly Listed U.S. Invoice-Financing and Working-Capital Lenders to Small and Mid-Sized Businesses screener.
Stewards (SWRD)
Overview: Stewards Inc. provides revenue based and working capital financing, including merchant cash advances and business loans, to U.S. small and mid sized businesses.
Operations: The business reports about $7.5 million from Financing Solutions, with all reported revenue of roughly $16.9 million generated in the United States.
Market Cap: US$454 million
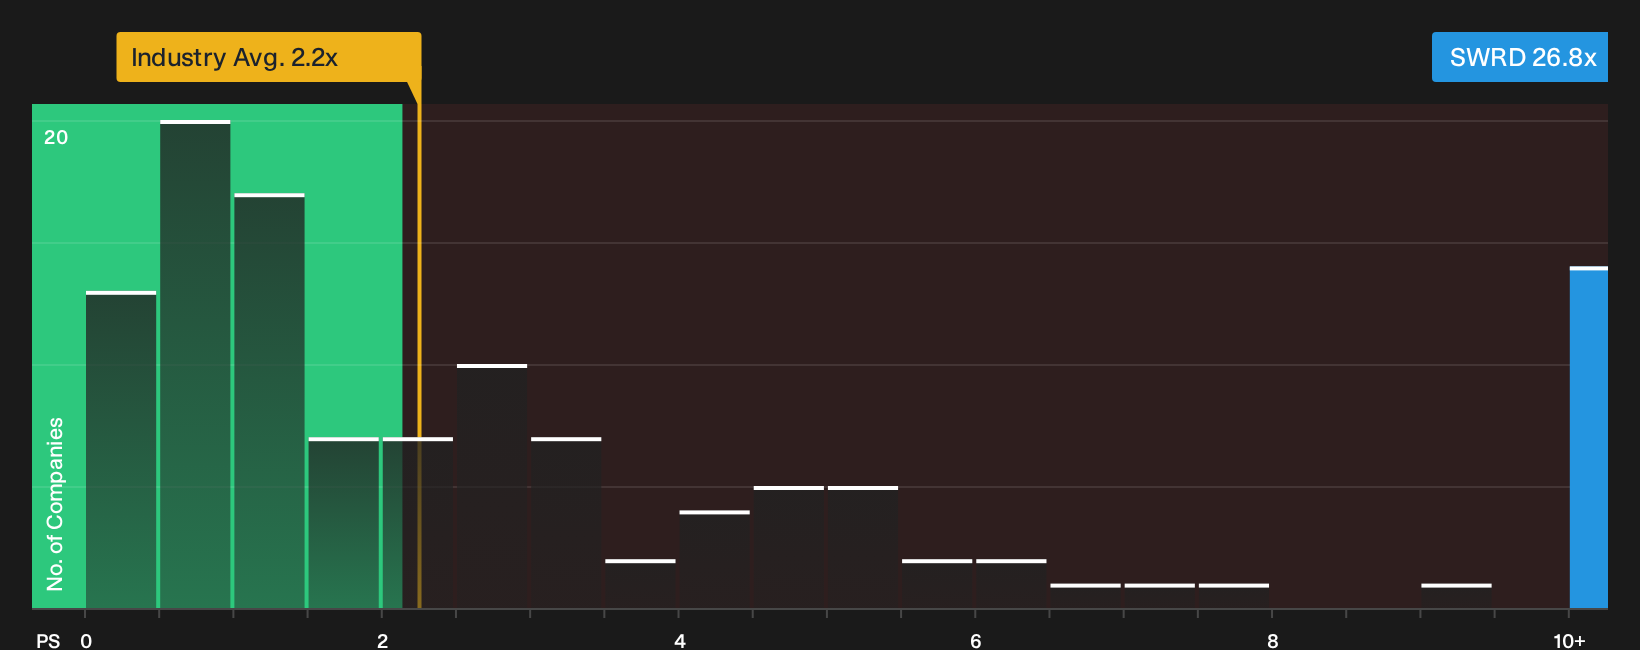
Stewards sits squarely in the stress point of this theme, supplying non bank working capital to small and mid sized firms feeling tariff, fuel and rate pressure. Revenue is rising, the stock trades on a rich P/S multiple and funding relies entirely on external capital. The value of that model depends heavily on how one unseen pressure on its margins evolves.
To see how that pressure shows up in the numbers, review the 1 key reward and 2 important warning signs (1 is major!) and decide whether Stewards’ premium P/S reflects underlying fragility or leverage.
HA Sustainable Infrastructure Capital (HASI)
Overview: HA Sustainable Infrastructure Capital finances energy efficiency and renewable power projects across the United States, earning returns from long-term climate-focused assets.
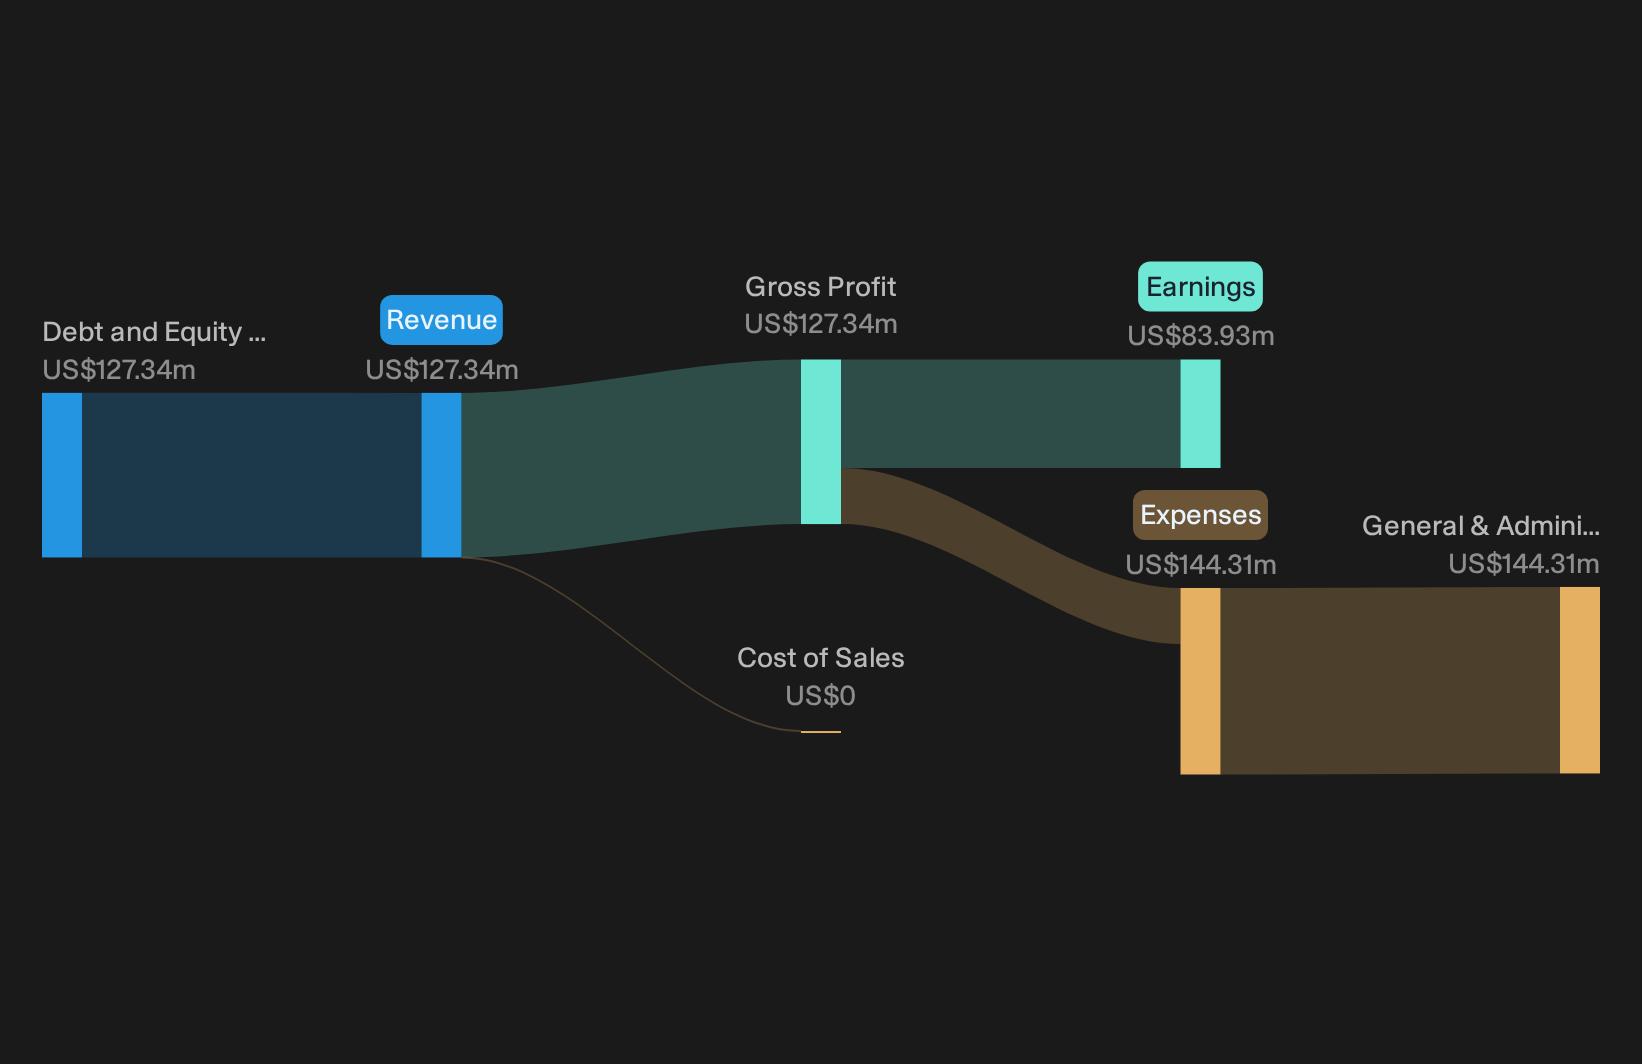
Operations: HA Sustainable Infrastructure Capital generates all of its roughly $127 million in revenue from U.S. debt and equity investments in sustainable infrastructure projects.
Market Cap: US$4.7b
HA Sustainable Infrastructure Capital fits this screener as a specialist lender to long-lived clean energy and efficiency assets rather than classic SME invoice finance. However, its receivables-style cash flows and reliance on external funding still echo specialty credit risk. Investors watching tariffs, fuel costs and higher rates may find the real story in how its funding costs interact with those long-term project returns, depending on how one critical pricing pressure evolves.
That pricing pressure question sits at the heart of HA Sustainable Infrastructure Capital, and the analysis report for HA Sustainable Infrastructure Capital shows whether funding costs are quietly eroding long term project returns.
Bladex (BLX)
Overview: Bladex Inc. is a Panama based trade finance bank that funds cross border working capital across Latin America and the Caribbean.
Operations: Bladex generates about $294 million from its Commercial segment and $35 million from Treasury activities, both supporting trade related finance.
Market Cap: US$2.0b
Bladex ties into this screener through its trade related working capital and factoring activities. The real interest comes from how management is trying to turn that niche into a stickier, higher fee business.
"The rollout of a new digital trade finance platform positions Bladex to significantly increase transaction volumes, improve client retention, and expand service offerings to underbanked SMEs, which should drive fee income, boost revenue growth, and enhance operational efficiency over the coming 18 months."
What really matters now is how a single shift in where that funding comes from filters through to future margins and growth optionality.
That funding twist is where Bladex could really accelerate, and the full narrative for Bladex shows how fee income, risk and valuation might decouple from traditional trade banks.

Seeking Fresh Alternatives Before They Fly
New themes move fast, and the cleanest breakout ideas rarely stay under the radar for long. To spot fresh momentum before prices move further, consider taking action early.
- Track cash rich compounders before the crowd notices by scanning the list of solid balance sheet and fundamentals (23 results) and filter for businesses that can fund growth without relying heavily on fresh equity.
- Hunt for early stage AI companies with real revenue momentum using the 38 profitable AI stocks that aren't just burning cash so you focus on businesses already proving their models.
- Target income ideas with pricing power using the 7 dividend fortresses and focus on payout streams that aim to keep working while markets move.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com