


AI stocks have been on a wild narrative ride, and Nvidia CEO Jensen Huang just nudged that story in a fresh direction by rejecting talk of AI “extinction” risk while backing ongoing investment in the tech. That kind of clear pro-adoption stance can reshape how investors think about risk and reward. This article breaks down 3 stocks exposed to that shift and what Huang’s comments might mean for each.
The stocks covered next are just a small sample of the Global AI Platform and Infrastructure Leaders idea. The full screen surfaced 60 more large listed companies with equally compelling AI related narratives that are not discussed here.
If you want to move beyond teasers and start sizing up your own shortlist, head straight into the Global AI Platform and Infrastructure Leaders screener to identify, filter and analyze potential high conviction AI platform and infrastructure plays.
Monolithic Power Systems (MPWR)
Monolithic Power Systems sits near the center of the AI infrastructure story, supplying power chips that keep high end data center and cloud hardware running efficiently. This is exactly the kind of behind the scenes exposure this screener is built to spotlight.
Investor optimism appears anchored in MPS's exposure to accelerating AI adoption in data centers (including design wins with major ASIC-based AI platforms and anticipated industry-wide server transitions to 48V/800V architectures). This optimism could drive sustained revenue outperformance, even as end-market growth normalizes and competition increases.
What really matters next is how one quiet shift in this AI power market filters through to future profitability and staying power.
Monolithic Power Systems focuses on semiconductor based power electronics, with all of its US$3.3b revenue coming from power chips and related products that support servers, AI systems, autos and industrial gear worldwide, and the stock carries a market value around US$59.8b.
To see how that power story could evolve from design wins to long term earnings resilience, read the full narrative for Monolithic Power Systems and identify what the market may be missing.

Taiwan Semiconductor Manufacturing (TWSE:2330)
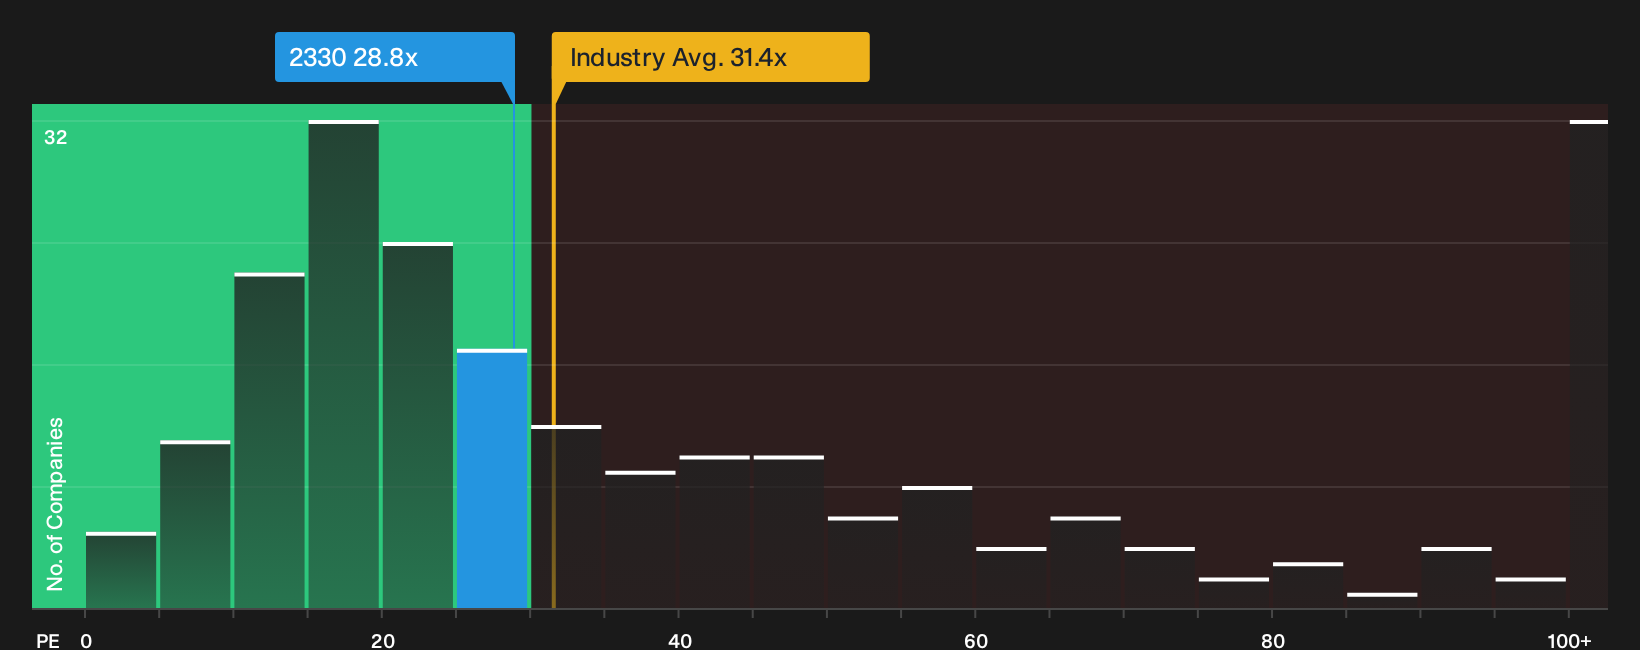
Taiwan Semiconductor Manufacturing is the foundry behind many of the cutting edge AI accelerators and cloud chips in this screener, with its NT$4.4t foundry operation driving all revenue and supporting a market value of around NT$63.8t.
For anyone tracking how AI data-center buildouts translate into real-world suppliers, Taiwan Semiconductor Manufacturing is the purest expression of that theme in this list.
Geopolitical concentration: Self-explanatory. TSMC might not exist, at least in its current form, if a certain regional bully gets its way.
What happens to AI-driven demand and pricing power if one unseen pressure around where cutting edge chips are made starts to shift?
If that pressure point is what worries you, read the full narrative for Taiwan Semiconductor Manufacturing to see how Taiwan Semiconductor Manufacturing’s AI trajectory could still accelerate from here.
SK hynix (KOSE:A000660)
SK hynix is effectively the memory engine of the AI buildout, feeding data-center GPUs and accelerators with DRAM, HBM and NAND that power training and inference workloads worldwide.
SK hynix generates all of its ₩189,170,615 million revenue from manufacturing and selling semiconductor products, with a market value of about ₩1,353,503.2 billion.
For an investor looking at AI infrastructure from the ground up, SK hynix is where the abstract idea of "AI demand" turns into very real orders for high bandwidth memory, DRAM and NAND that feed hyperscale data centers, cloud platforms and advanced GPUs.
SK hynix's accelerating investment in new fabs and advanced packaging, together with visible long-term supply agreements with major hyperscalers, provides insulation against cyclical downturns and may enable output scale that supports higher revenues as memory content requirements in AI, automotive, and IoT increase.
The real swing factor is what happens to pricing power if one key supply constraint in high bandwidth memory starts to ease faster than expected.
If that supply swing is the real question for you, read the full narrative for SK hynix to see how SK hynix could turn easing constraints into a lasting advantage.

Seeking Fresh Alternatives For Your Watchlist
New themes can gather momentum quickly, and some of the most interesting ideas may still be flying under the radar. Review these fresh lists before they become widely followed.
- Identify income-focused companies with strong cash support and use the 7 dividend fortresses to find yield opportunities before payouts and prices change significantly.
- Explore potential infrastructure-related companies and use the 39 power grid technology and infrastructure stocks while the grid overhaul story is still developing and valuations remain in earlier stages.
- Look for companies using AI in their operations and use the 38 profitable AI stocks that aren't just burning cash to focus on businesses that are already generating earnings from AI-related activity rather than relying on headlines alone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com