


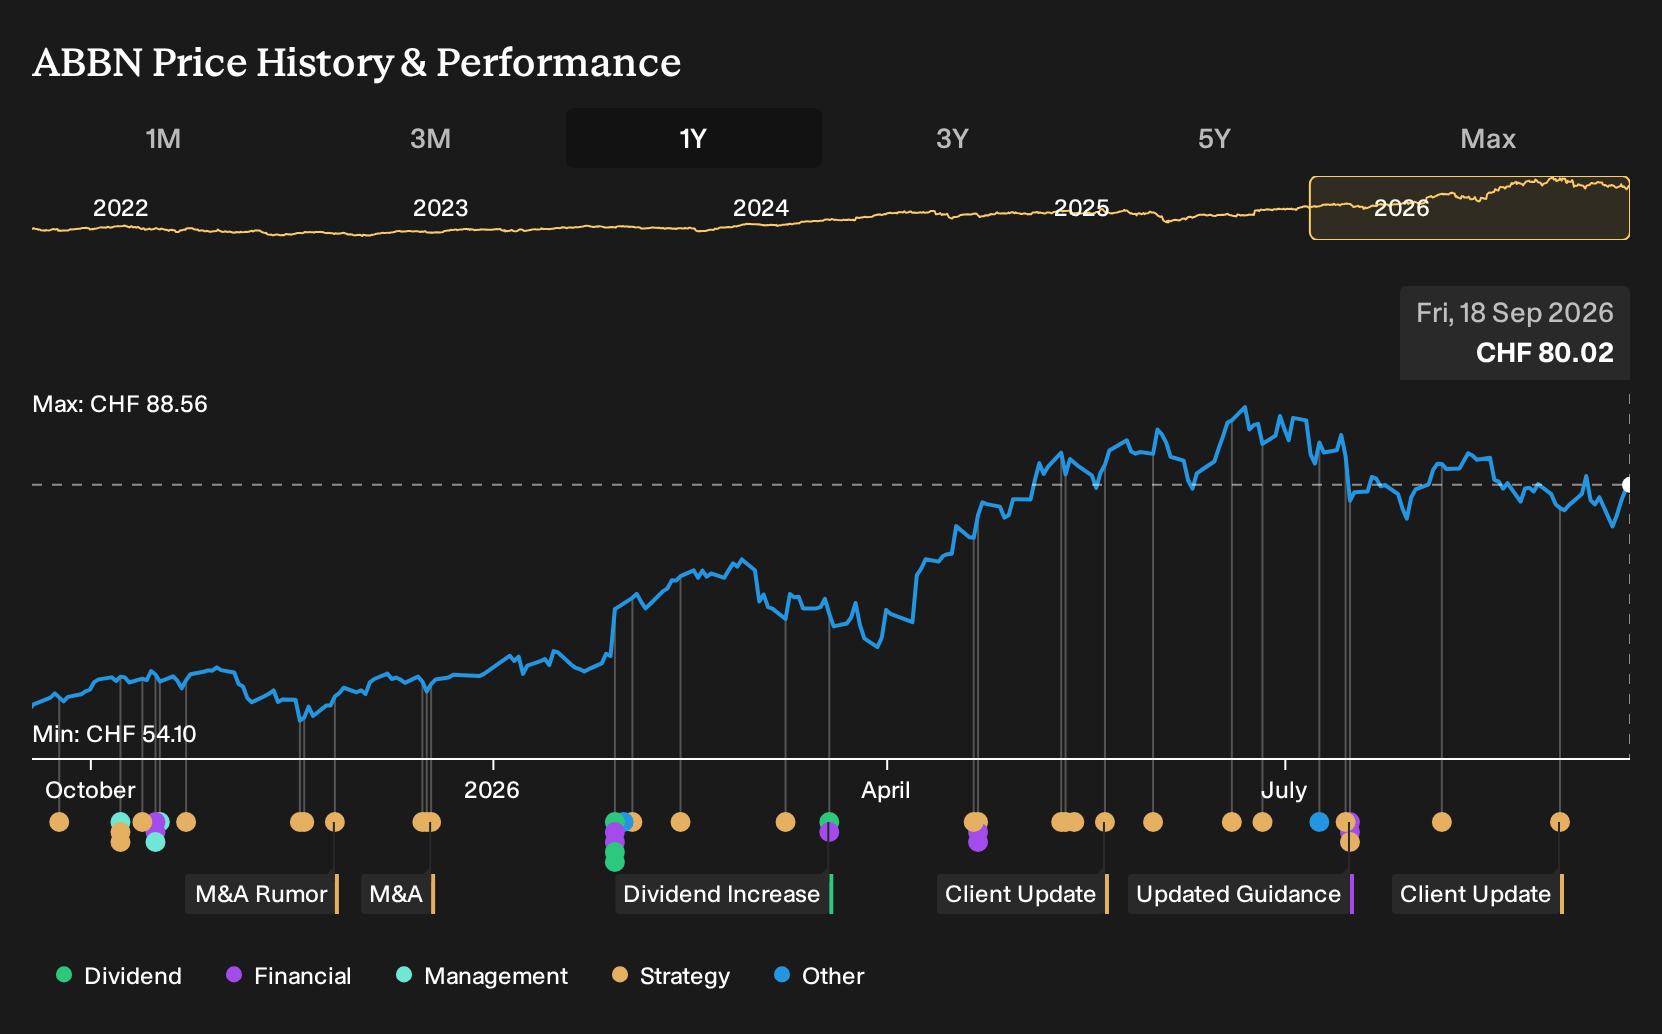
- ABB has attracted fresh attention after recent share price moves, with market interest underpinned by robust order intake in electrification, utilities and data center demand, alongside progress in building to grid and direct current power technologies.
- The combination of strong backlog support and emerging projects such as ABB’s work on building to grid systems and the Ferrari Hypersail partnership highlights how the company’s power technology pipeline is shaping expectations around future cash flow generation and valuation risk.
- This review will now examine how ABB's investment narrative could be affected by its strong electrification and data center order momentum.
Scan beyond ABB and evaluate other power grid and electrification beneficiaries with the hand picked 39 power grid technology and infrastructure stocks that are riding the same demand from utilities and data center build outs.
ABB Investment Narrative Recap
To own ABB today, you need to be comfortable with a story built on electrification, grid upgrades and data center power needs turning into sustained orders and cash generation. The recent focus on building-to-grid and direct-current systems supports that view by tying ABB closer to utility and infrastructure projects with multiyear visibility.
The flip side is execution risk. A high P/E and limited valuation cushion make delivery on the order backlog and pipeline critical. Any slowdown in utility or data center projects, or weaker automation demand in areas like China, would likely matter more than the latest share price move.
The most relevant recent development for this story is ABB’s work on building-to-grid and direct-current technologies, including the Ferrari Hypersail partnership. These projects anchor ABB in the power conversion and grid connection layer that data centers and renewables depend on, which is where the strongest order momentum is showing up.
For catalysts, investors are watching whether these solutions convert into recurring service, software and lifecycle revenues, not just one-off equipment sales. The risk is that execution delays or increased competition in key regions compress margins just as the company is priced close to DCF estimates, which would leave less room for error on future cash flow delivery.
ABB's narrative projects $48.6b revenue and $7.3b earnings by 2029. This assumes 10.8% yearly revenue growth and an earnings increase of about $2.3b from $5.0b today.
Uncover why ABB's fair value indicates that revenue and earnings by 2029 are roughly in line with its current price.
Exploring Other Perspectives
One alternate read on ABB focuses on protectionism risk. The most pessimistic analysts were pencilling in revenue of about $43.6b and earnings near $6.6b by 2029, which sits well below the bullish $9.5b earnings view. That gap shows how widely opinions can differ, so treat this news as a chance to compare several competing narratives.
Explore 5 other ABB fair value estimates, including one that suggests as much as 14% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ABB research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ABB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ABB's overall financial health at a glance.
Looking For More Ideas Beyond ABB?
Once you have a view on ABB, it can help to widen the lens and compare it with other companies that share similar quality, income, or resilience traits using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, start with a curated set of 179 high quality undervalued stocks that may line up better with your return expectations and risk limits.
- For investors who care most about reliable income, focus on companies screened as 159 dividend fortresses to see which payouts might fit a long term portfolio.
- When capital preservation matters just as much as upside, consider a group of 227 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com