


UK green infrastructure is back in the spotlight as policymakers talk about turning the National Wealth Fund into something closer to a full-scale development bank, with deeper pockets and a bigger appetite for long term projects. That kind of public firepower can change who gets funded and on what terms. This piece highlights three UK listed clean energy and infrastructure developers that appear closely tied to this policy story.
The stocks highlighted below are only a small sample of what fits this green infrastructure thesis, and the full screen surfaced 19 more UK listed developers with similarly detailed stories that are not covered here. To identify potential opportunities in this wider group, head straight to the UK-listed green infrastructure and clean energy developers screener to filter, analyze and focus on the highest conviction plays.
SSE (LSE:SSE)
Overview: SSE is a UK utility that builds and operates renewable power projects and electricity networks that underpin the country’s energy transition.
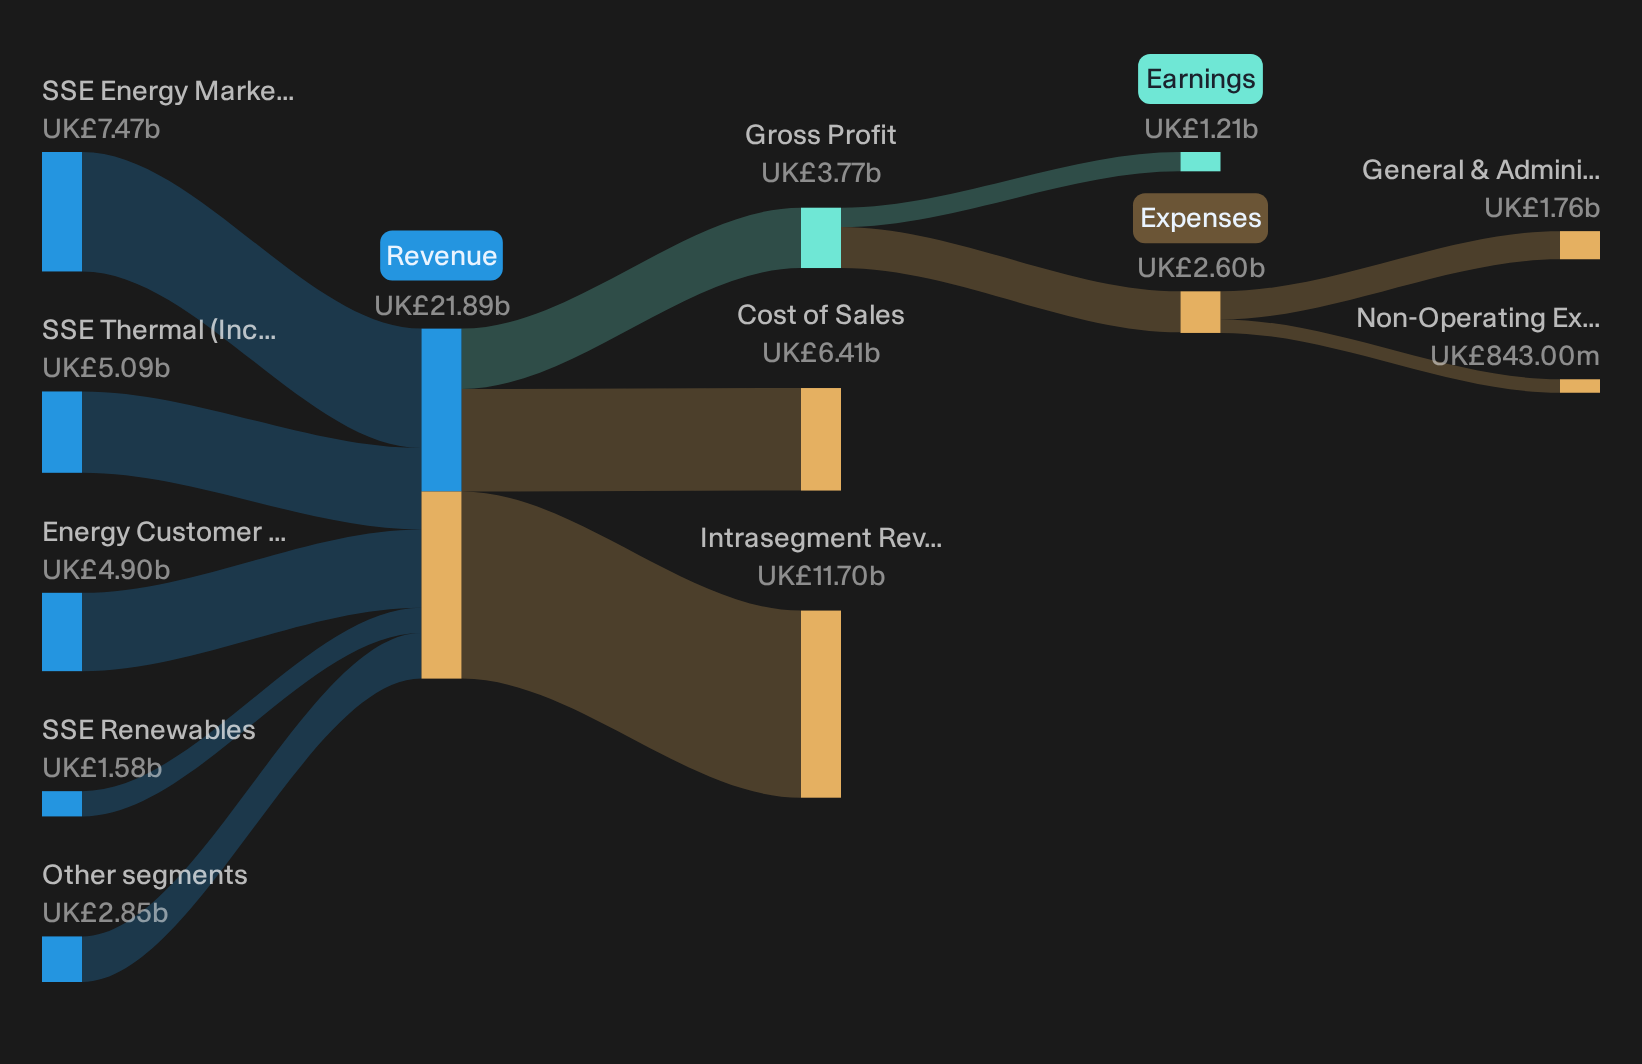
Operations: SSE generates over £7.5b from SSE Energy Markets, about £5.1b from SSE Thermal, £4.9b from Energy Customer Solutions and around £4b from its Renewables, Distribution and Transmission units, with most activity in the UK.
Market Cap: £29.3b
SSE matters for this green infrastructure screen because it directly links offshore wind farms, hydro assets and grid investment to the UK’s push for cleaner, more reliable power.
"Expansion of regulated asset base (RAV growth)"
What happens to that RAV expansion, and the returns attached to it, depends heavily on how one key policy support question is resolved.
That policy hinge is exactly what the full narrative for SSE unpacks, showing where SSE’s regulated growth could accelerate, stall or quietly decouple from headline sentiment.
Ceres Power Holdings (LSE:CWR)
Overview: Ceres Power Holdings develops solid oxide fuel cell and electrolysis technology that helps cut emissions in power, hydrogen and heavy industry.
Operations: Ceres Power currently reports no segmented business revenue, with sales mainly coming from Asia at about £28 million and Europe near £5 million.
Market Cap: £877 million
Ceres Power fits into this green infrastructure screen as a UK developer whose fuel cell and electrochemical platforms can plug into hydrogen, retrofit and industrial decarbonisation projects that government backed capital might increasingly target.
"Ceres Power's unique solid oxide technology and licensing business model provide cross-border opportunities, enabling the company to tap into global markets despite trade wars and localized production. This licensing approach helps reduce costs, expand global reach, and grow revenue by attracting partnerships with major companies across different regions."
The key uncertainty is how far future project pipelines actually convert these licensed technologies into recurring royalties and improved margins at scale.
That conversion risk is exactly why the full narrative for Ceres Power Holdings digs into how project timing, partner execution and capital intensity could either accelerate or stall Ceres Power’s royalty engine.

Ashtead Technology Holdings (LSE:AT.)
Overview: Ashtead Technology Holdings rents subsea equipment and provides offshore services that support oil, gas and offshore renewable energy projects worldwide.
Operations: Ashtead Technology generates about £204 million from oil well equipment and services, with revenue mainly in Europe at £141 million and smaller contributions from the Americas, Middle East and Asia Pacific.
Market Cap: £270 million
Ashtead Technology Holdings matters for this green infrastructure screen because its subsea kit and services help keep offshore wind and other marine renewables projects moving from seabed surveys through to long term inspection work.
"Although long-term customer backlogs at major subsea contractors and a forecast rise in offshore infrastructure spend point to a healthy opportunity set, timing slippages, regional conflicts and project cancellations, such as those seen in the Middle East and APAC, may lead to ongoing revenue volatility and working capital swings that constrain free cash flow and slow debt reduction."
The real swing factor for Ashtead Technology Holdings is how one pressure on cash generation shapes future spending capacity and profitability.
That cash squeeze is exactly what the full narrative for Ashtead Technology Holdings unpacks, separating short term funding friction from the longer term growth capacity Ashtead Technology Holdings might be building beneath the surface.
Seeking Fresh Alternatives Beyond Today?
Fresh ideas move first. Late money chases what is already flying, while early entries catch breakouts under the radar for now. Momentum can shift quickly, so consider acting in a timely way.
- Spot quieter potential before it gets crowded by scanning 6 high quality undiscovered gems, which focuses on quality fundamentals while attention stays locked on bigger, louder tickers.
- Track durable income while prices swing elsewhere by reviewing 1 dividend fortresses, designed to highlight businesses aiming to support higher yields for longer.
- Explore structural demand in critical metals by checking 17 top copper producer stocks, which highlights producers tied to long term electrification and infrastructure themes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com