


Northwest Natural Holding (NWN) recently drew investor attention after its shares closed at $48.34, with a trailing 1-year total return of 17.6% and a 3-year total return of 40.9%.
Recent moves show that momentum for Northwest Natural Holding has cooled in the short term, with the share price slipping 2.2% over the past month and 3.2% over the last quarter, even as the 1-year total shareholder return of 17.6% points to a stronger longer run for patient holders.
Scan beyond Northwest Natural Holding and compare its recent 1-year and 3-year gains with a curated group of 30 resilient stocks with low risk scores that aim to pair resilience with measured momentum.
That softer recent share performance could be investors cooling on Northwest Natural Holding rather than any clear shift in the underlying gas and water utility business. Which story do the current valuation markers actually support?
Most Popular Narrative: 16% Undervalued
Against a last close of $48.34, the most followed narrative for Northwest Natural Holding points to a fair value of $57.50, which frames the current pullback as a possible discount rather than a clear warning sign.
Robust customer growth in Texas via the SiEnergy and Pines acquisitions, supported by urbanization and population expansion, suggests a long tailwind for meter additions, translating to steady increases in revenues and future earnings.
See why 7 investors see Northwest Natural Holding as 16% undervalued.
Result: Fair Value of $57.50 (UNDERVALUED)
Still, the bullish Northwest Natural Holding story runs into real friction if regulators push back on cost recovery or if decarbonization policies steadily erode long term gas demand.
Find out about the key risks to this Northwest Natural Holding narrative.
Another View on Northwest Natural Holding’s Valuation
The fair value narrative puts Northwest Natural Holding at $57.50, yet the SWS DCF model tells a different story. On that cash flow view, the stock around $48.34 sits above an estimated value of $39.46, which screens as overvalued instead of discounted. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
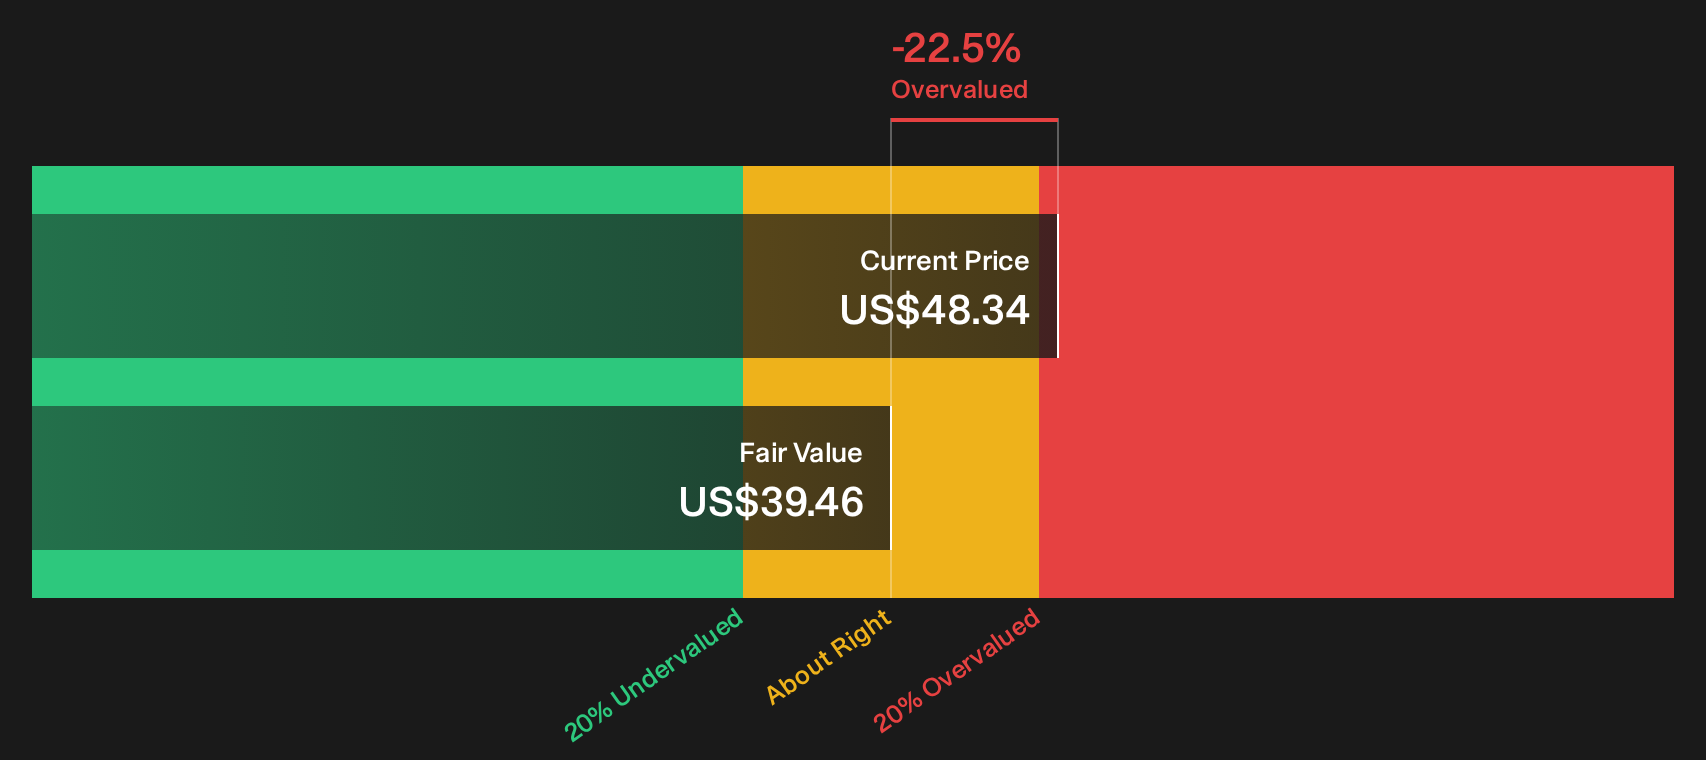
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Northwest Natural Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Northwest Natural Holding’s value and risk profile can feel messy, so it may help to move quickly and review both sides of the story in detail. To weigh the concern around downside drivers against the potential upside that optimistic holders see, start with the 3 key rewards and 2 important warning signs.
Looking for more Northwest Natural Holding sized ideas?
If you want to pressure test the Northwest Natural Holding story, widen the lens and stack it against other opportunities sourced from the Simply Wall St screener.
- Target durable balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that can help you stress test resilience before the next bout of volatility hits.
- Hunt for potential mispricing and compare Northwest Natural Holding against a curated pool of 35 high quality undervalued stocks that may offer a more attractive entry point.
- Build your watchlist around staying power by checking a 16 high quality undiscovered gems that could potentially reward investors who move before the crowd.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com