


The Federal Reserve just raised interest rates for the first time since 2023, lifting its target range to 3.75% to 4%. It also hinted another increase could follow. For most companies, a quarter-point move isn’t a massive concern. But for CoreWeave (CRWV), even a small increase matters because it presses on the firm’s weakest point.
CoreWeave’s whole model runs on debt. It borrows heavily to buy Nvidia (NVDA) chips and build data centers, then rents out that computing power. The business is growing fast, with revenue up 112% last quarter. The problem is the cost of that growth. CoreWeave carries more than $51 billion in debt, which is more than its market cap itself. Its interest bill now runs higher than its operating income. Its CFO recently described the build-out as funded through debt, customer prepayments, and other capital.
Higher rates make new borrowing pricier, and CoreWeave has to keep borrowing to keep growing. Its recent debt already carried interest rates around 9%. So every rate increase raises the cost of the next data center. Investors are growing nervous, and the market shows it. The perceived risk that CoreWeave can’t pay its debts has climbed sharply. Insider selling, including share sales filed by the CEO, has added to the unease.
The Gap With Nebius Just Widened
This is precisely why I’ve preferred Nebius (NBIS) over CoreWeave. As I wrote when both firms last reported, the two play in the same AI cloud market, but their balance sheets aren’t close. Nebius carries roughly $2 billion in net debt against CoreWeave’s $46 billion. It also covers much of its spending through customer prepayments rather than fresh borrowing. An increased rate barely touches that model. CoreWeave gets punished much worse.
CoreWeave does have its strengths, though. It holds a backlog worth over $100 billion and just raised its guidance. So this isn’t a company that is about to collapse. But the rate hike widens a gap that was already there. CoreWeave now has to find its way out of a debt load that just got even more expensive to carry.
About CoreWeave Stock
CoreWeave is a cloud computing company that provides the powerful computing infrastructure needed to run artificial intelligence applications. The company is best known for its GPUs, which are commonly used for AI training, machine learning, and other demanding workloads. It also offers data storage, networking, software tools, and services that help customers build, manage, and scale AI projects more efficiently. Founded in 2017, the company is headquartered in Livingston, New Jersey.
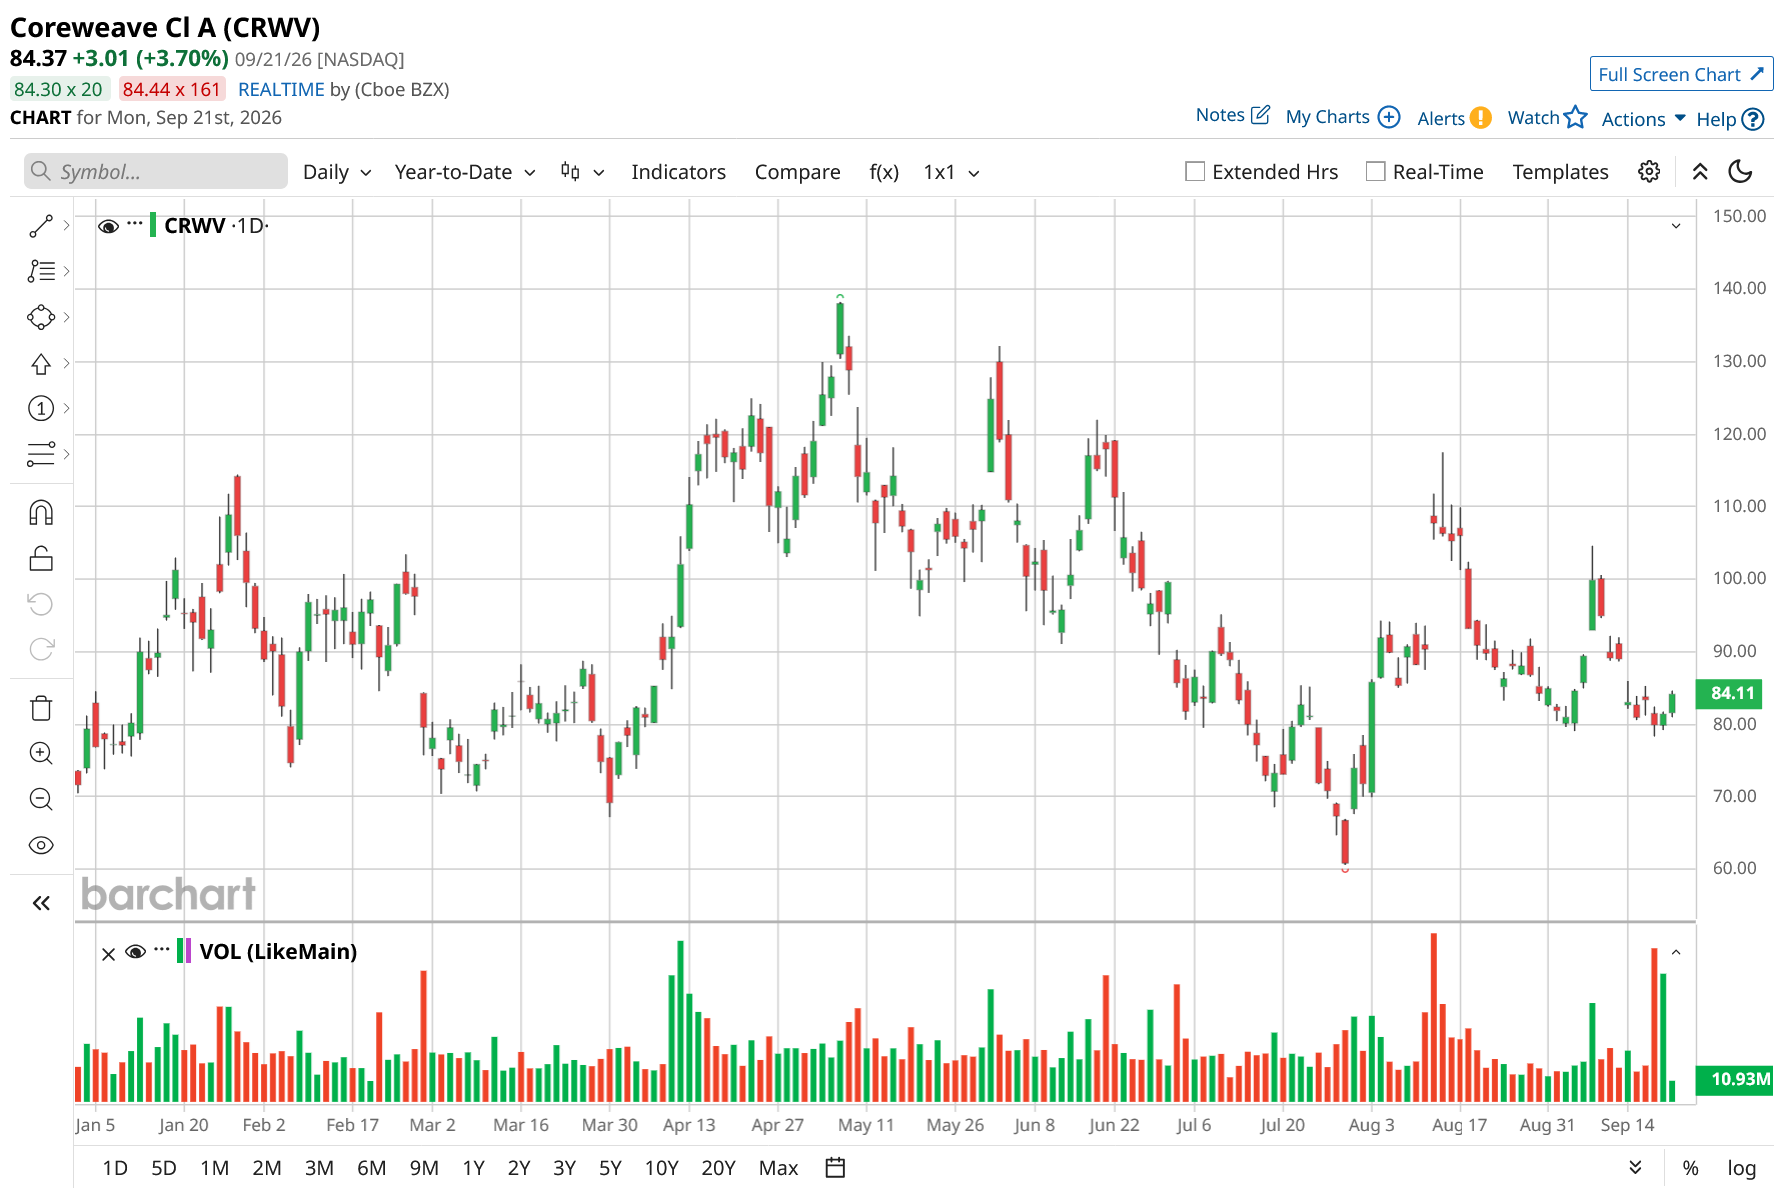
Over the past year, CoreWeave shares have declined 33%, underperforming the broader cloud infrastructure market. The First Trust Cloud Computing ETF (SKYY) generated gains of 20% during the same period. The performance gap indicates that the decline was driven by company-specific concerns rather than by weakness across the broader sector. However, CRWV shares have risen 17% year-to-date (YTD), still lagging the ETF’s gain of 28%.
CoreWeave isn’t profitable, so there’s no meaningful price-to-earnings (P/E) available. Its forward price-to-sales (P/S) ratio of 3.56x looks inexpensive next to most AI infrastructure names. Nebius, for example, has a P/S ratio of 17.16x. So CoreWeave is nearly 5 times cheaper. But cheap doesn’t mean safe here. The low multiple reflects the debt problem rather than a bargain the market has missed. The EPS outlook remains volatile through this decade, which shows how uncertain the path to profit still is.
The balance sheet is the real issue. CoreWeave holds just $5.54 billion in cash against $51.61 billion in debt, leaving it deeply in the red on a net basis. Until that gap narrows, I’d call the valuation a warning, not an opportunity.
Lifts 2026 Guidance Following Strong AI Infrastructure Momentum
CoreWeave reported its second-quarter fiscal 2026 earnings on Aug. 11. It reported revenue of $2.6 billion, up 112% year-over-year (YoY). This increase reflects strong demand for the company’s cloud services. The company’s adjusted EBITDA reached $1.5 billion, up from $753 million a year earlier, with a 59% margin. Adjusted operating income was $128 million. Net loss for the quarter was $626 million, and interest expense was $640 million. It is spending aggressively on power, infrastructure, and financing to support future growth. Therefore, capital expenditure incurred in the quarter was $9.4 billion.
Looking forward, CoreWeave raised its full-year 2026 revenue guidance to $12.4 billion to $13.2 billion. The company also lifted its full-year adjusted operating income outlook to $960 million to $1.15 billion and increased its exit ARR target to $18.5 billion to $19.5 billion. The company expects to end the year with more than 1.85 gigawatts of active power, up from previous guidance of more than 1.7 gigawatts. For the third quarter, the company guided revenue of $3.45 billion to $3.6 billion. It plans to invest more to meet future demand; as a result, it guided capital expenditures of $11.5 billion to $13.5 billion. CFO Nitin Agrawal said the company is more confident than ever in the long-term ROI of its product and capacity investments.
What Do Analysts Expect for CRWV Stock?
Wall Street remains largely constructive on CRWV stock, even as some analysts take a more cautious stance. Bernstein analyst Madison Rezaei reiterated a “Sell” rating with a price target of $74. In contrast, Truist Financial maintained a “Buy” rating and assigned a price target of $165. The analyst’s price target reflects 96% upside from current levels. However, another analyst from Goldman Sachs reiterated a “Hold” rating while raising the firm’s price target from $121 to $139.
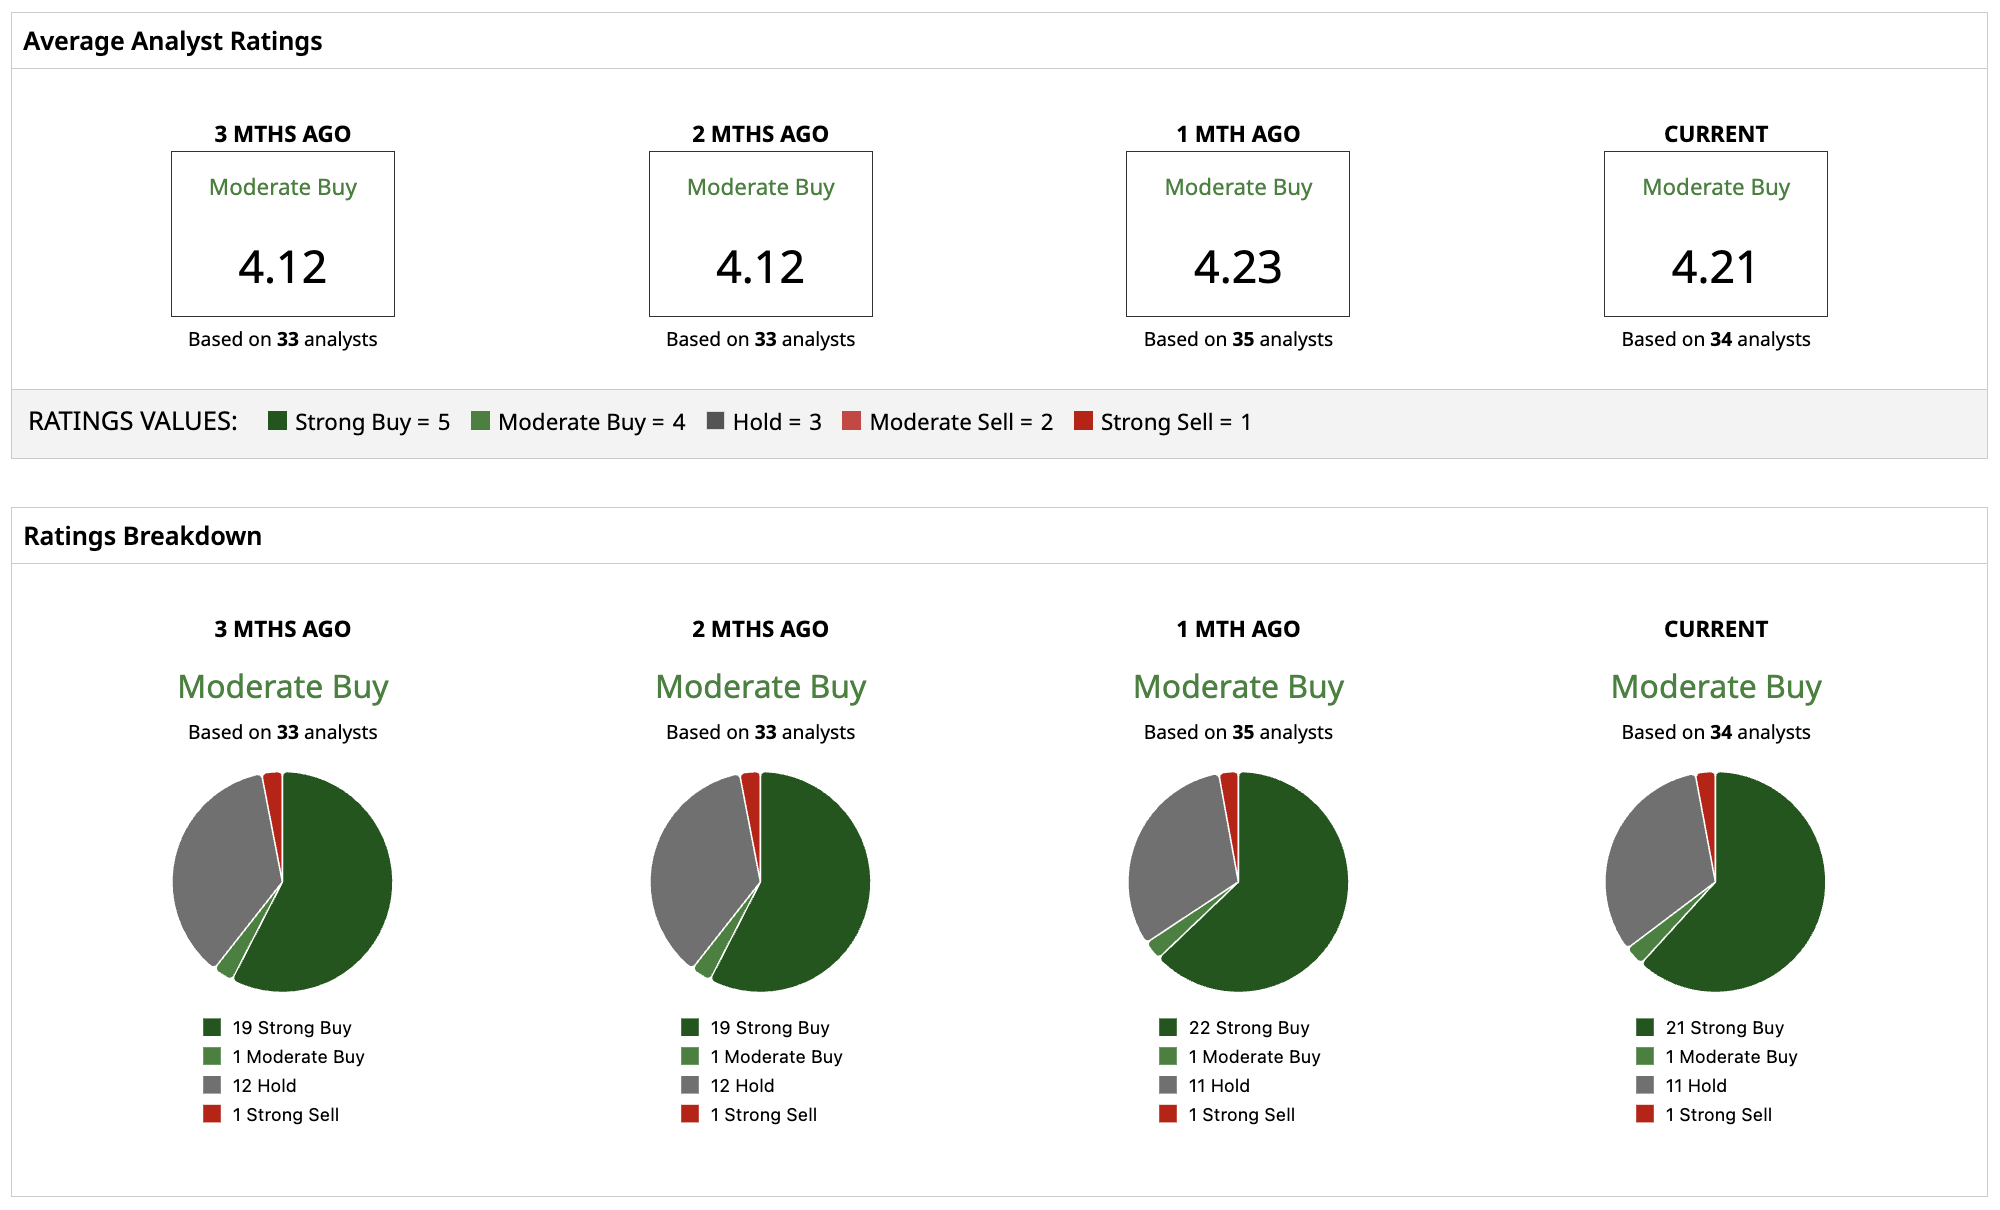
Based on 34 Wall Street analysts covering CWRV stock, it holds a consensus “Moderate Buy” rating. Out of those, 21 have a “Strong Buy” rating, one has a “Moderate Buy” rating, 11 have a “Hold” rating, and one has a “Strong Sell” rating. The median price target of $138.64 reflects 64% upside from the current share price.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.