


Executive change puts Capri Holdings stock in focus
Capri Holdings (CPRI) drew fresh attention after appointing Catherine So as Chief Legal and Sustainability Officer, a move that brings governance, compliance, and environmental priorities directly into the investment conversation.
Recent trading has been choppy for Capri Holdings, with the share price at US$14.75 after a 1-day share price return that declined 1.34%, even as the 30-day share price return rose 8.06% and the year-to-date share price return fell 39.52%.
Over a longer stretch, total shareholder return declined 26.43% over the past year and more than 70% over three and five years. Investors watching the executive hire and the recent conference appearance are weighing whether sentiment is merely stabilising in the short term or still resetting around Capri Holdings’ risk profile.
Scan Capri Holdings alongside a handpicked peer group by reviewing the 35 high quality undervalued stocks, which combines cash flow strength with sturdier balance sheets than the recent share price moves might suggest.
Capri Holdings now trades near US$14.75 after steep multi year value erosion, even as a new governance hire lands. Does that reset create a skewed opportunity for fresh buyers, or does it signal that risk still dominates the payoff?
Most Popular Narrative: 35% Undervalued
Capri Holdings closed at $14.75 while the most followed narrative pegs fair value at $22.53, a wide gap that raises questions about whether the market is underestimating its turnaround efforts or still heavily discounting execution risk.
Sequential improvement in full-price store traffic, reduced discounting, and growing success of new product launches, supported by data-driven marketing and influencer engagement, signal effective brand revitalization and are expected to drive AUR and revenue growth.
Expanded use of advanced analytics and digital platforms is improving consumer targeting and engagement, setting the stage for higher conversion rates, increased customer database size, and improved net margins as omnichannel strategies mature.
See why 9 investors see Capri Holdings as 35% undervalued.
The fair value narrative uses an 11.67% discount rate and assumes Capri Holdings can translate these merchandising and analytics efforts into better earnings quality over time, even as current guidance reflects slower revenue growth and margin pressure. At the same time, it bakes in meaningful risks around tariffs, inventory, and brand fatigue, which helps explain why the implied valuation multiple in 2029 is lower than where the US Luxury peer group currently trades.
The result is a model that points to a fair value of $22.53 against a share price under $15. The gap is driven less by aggressive top line forecasts and more by expectations that margins and cash generation can improve from today’s levels if execution holds. For readers weighing that thesis against the recent share price history, it is worth stress testing the assumptions on revenue, profitability, and discount rate to see how much conviction you really have in the underlying narrative.
Result: Fair Value of $22.53 (UNDERVALUED)
Still, the Capri Holdings story can quickly change if tariff costs bite harder than expected or if Michael Kors brand fatigue persists and pressures margins again.
Find out about the key risks to this Capri Holdings narrative.
Another view on Capri Holdings valuation
The DCF style fair value narrative says Capri Holdings is undervalued at $14.75 versus an assessed $22.53, with upside based on future profit and cash flow. A second lens using earnings multiples presents a less forgiving picture and highlights valuation risk more clearly.
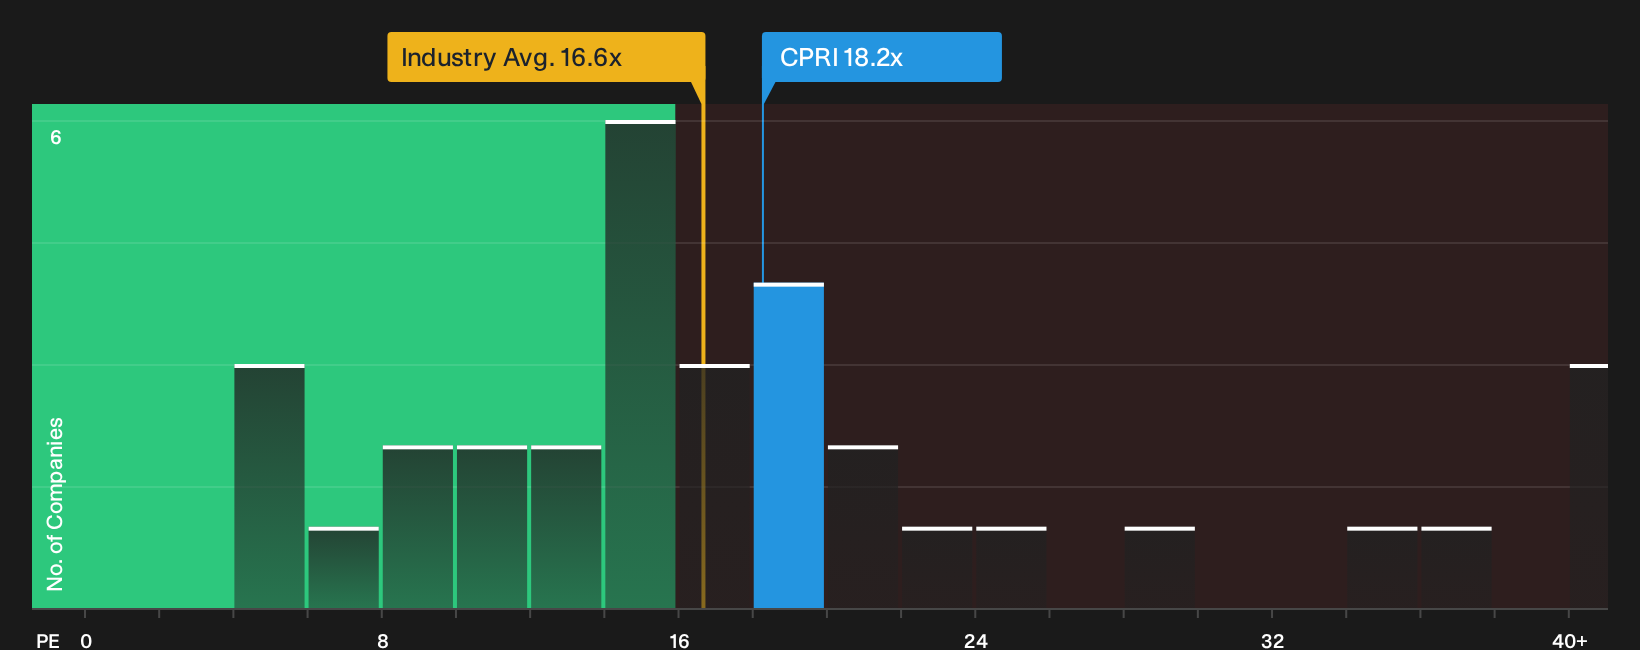
Capri trades on a P/E of 18.2x, which is higher than both the US Luxury industry at 16.6x and the peer average at 15.9x, even though analyst forecasts already incorporate significant earnings growth. The fair ratio is estimated at 22.5x, a level the market could move toward over time. That gap indicates some potential headroom if the outlined scenario occurs, but also raises the question of whether investors are being compensated adequately today for brand, debt, and execution risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Capri Holdings can easily pull you in opposite directions, so move quickly, test the numbers yourself, and see whether the balance of risks and rewards actually fits your playbook by weighing the 3 key rewards and 2 important warning signs.
Looking for more Capri Holdings investment ideas?
If Capri Holdings has sharpened your focus on valuation and risk, do not stop here. Broader context across sectors can sharpen your next move and help you spot gaps others ignore.
Use the Simply Wall St Screener to pressure test your thesis and uncover fresh watchlist candidates before momentum and liquidity shift to less attractive levels.
- Target resilient balance sheets and fundamentals by scanning our list of solid balance sheet and fundamentals (23 results) that can complement or contrast what you see in Capri Holdings.
- Hunt for mispriced opportunities by reviewing the 16 high quality undiscovered gems that combine financial quality with limited current market attention.
- Prioritise stability by checking the 30 resilient stocks with low risk scores and see which businesses score well on downside protection before capital leaves the safer end of the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com