


Fed governor Austan Goolsbee is hinting at more rate hikes and more pain for workers, which pushes a lot of fast growth stories to the sidelines and suddenly makes reliable cash payouts look far more interesting. Investors hunting for steadier dividends and tempered volatility may not want to wait until a full recession headline hits. This article walks through three defensive dividend stocks that are exposed to these Fed risks and explains why they deserve a closer look now.
The three stocks below are a starter set, while the full defensive dividend screen surfaced 29 more companies with similar quality stories that are not covered here.
If you want to identify, compare, and analyze those extra income ideas with tighter filters on risk, payout and valuation, head straight into the Defensive Dividend-Paying Value Stocks screener.
Nomad Foods (NOMD)
Nomad Foods fits this defensive dividend theme because it sells everyday frozen staples that people keep buying through good and bad cycles. The current rate backdrop makes that kind of steady demand and cash generation more valuable to dividend-focused investors.
Nomad Foods is a €3.0b frozen foods specialist, with essentially all of its revenue coming from products like fish, vegetables, ready meals and ice cream, and a roughly US$1.5b market cap that places the stock in the large cap, lower beta part of the screen.
"Ongoing innovation and renovation efforts, including the introduction of higher-margin categories like snacking, protein bowls, and expansion of chicken and natural fish products, position Nomad to capture revenue growth as consumers increasingly seek convenient, health-oriented frozen foods."
The real swing factor for Nomad Foods is how one pressure on profitability evolves if consumer budgets tighten while input costs stay stubbornly high.
If that squeeze on profitability is what you care about most, read the full narrative for Nomad Foods to see how Nomad Foods could still turn that pressure into accelerating strength.

Archer-Daniels-Midland (ADM)
Archer-Daniels-Midland is a defensive dividend candidate because it sits in the food and feed supply chain that tends to keep moving even when higher rates pressure growth stocks, and its size gives it room to keep paying investors while conditions stay uncertain.
Archer-Daniels-Midland is a US$41.1b agri-business that sources, processes, and distributes crops into oils, starches, sweeteners, and nutrition ingredients for human and animal use. Most of its roughly US$80.2b revenue is tied to Ag Services and Oilseeds at US$65.3b, Carbohydrate Solutions at US$11.5b, and Nutrition at US$7.5b.
"Reliance on U.S. biofuel policy clarity and Renewable Volume Obligations creates a risk that any delay or smaller than expected mandate keeps crush margins subdued for longer, which would restrain AS&O revenue and earnings power relative to what current pricing may imply."
What happens to Archer-Daniels-Midland’s appeal to dividend-focused investors if that one pressure on future profitability does not break its way?
If that risk feels overdone, read the full narrative for Archer-Daniels-Midland to see how Archer-Daniels-Midland’s income story could still accelerate beyond biofuel policy swings.

Quest Diagnostics (DGX)
Quest Diagnostics brings a healthcare tilt to this defensive dividend screen, with diagnostic testing that patients and insurers tend to treat as essential even when higher rates cool risk appetite elsewhere.
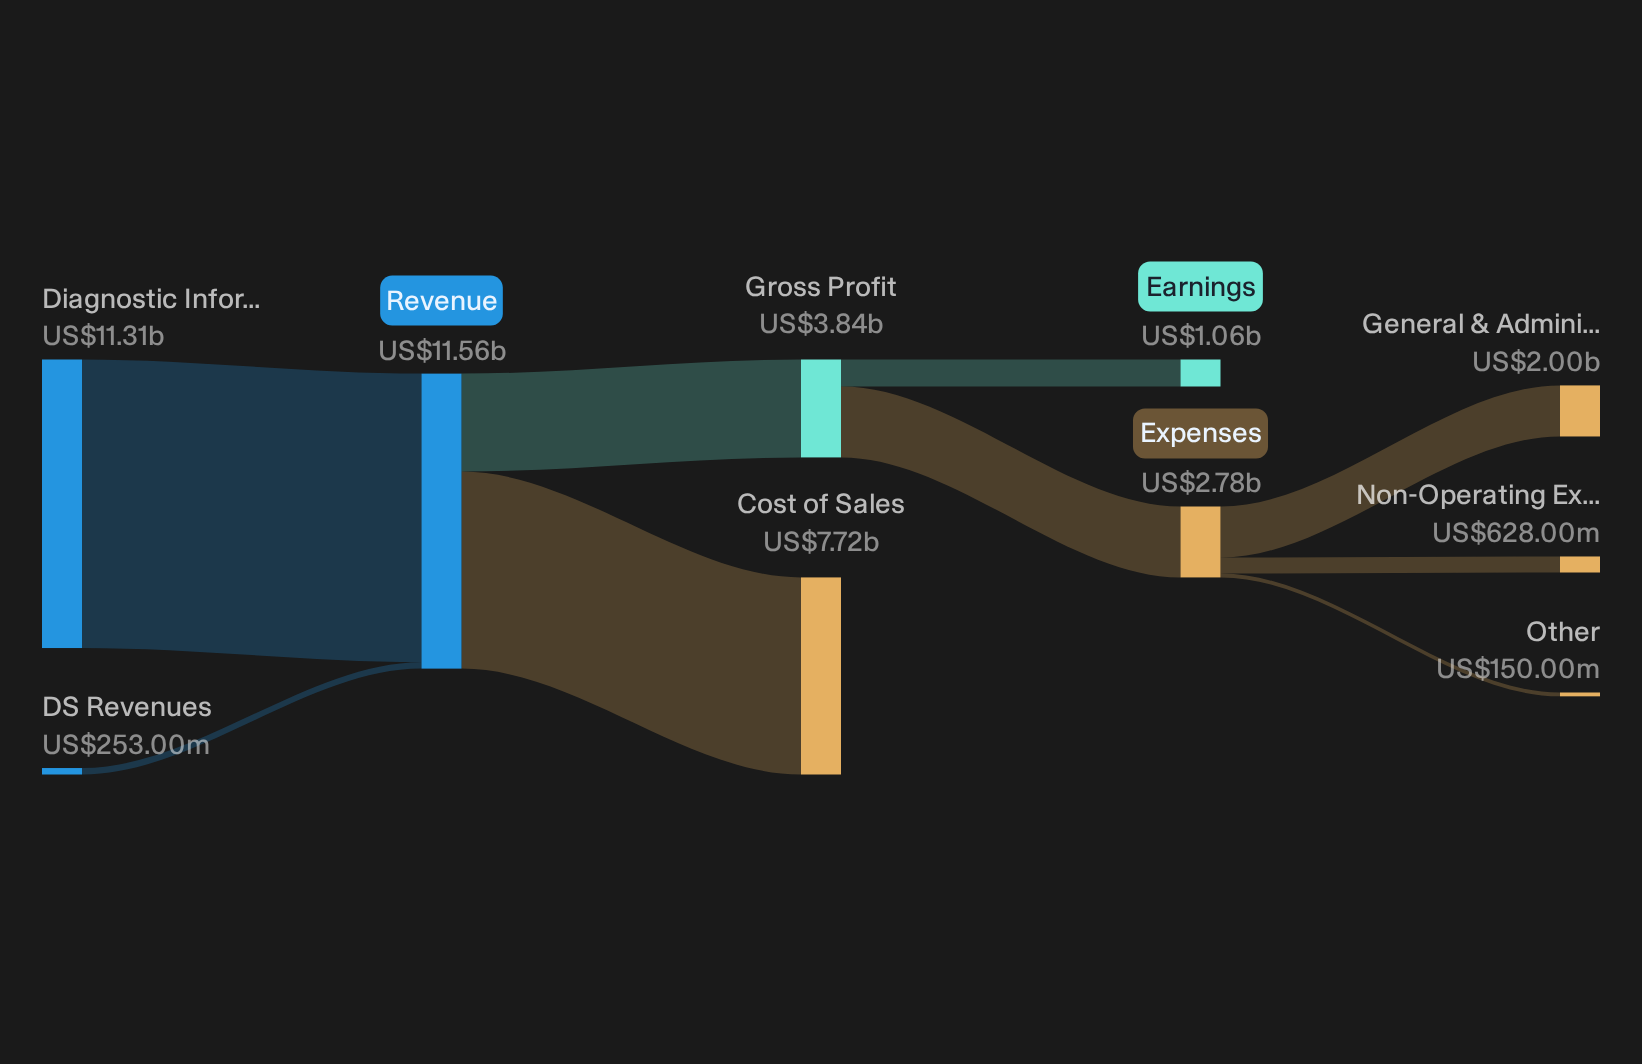
Quest Diagnostics runs a broad diagnostic testing network across the United States, generating about US$11.3b from Diagnostic Information Services and US$253 million from DS Revenues, with a roughly US$27.2b market cap anchoring it firmly in large cap territory.
"Ongoing growth in advanced and preventive testing, including cardiometabolic, autoimmune, brain health, oncology, and women's/reproductive diagnostics, as well as robust demand from functional medicine and wellness-focused consumers, are driving higher test volumes and increasing test-per-requisition, which supports both revenue growth and margin expansion."
The real test for Quest Diagnostics is how one unresolved cost and funding pressure shapes the balance between that volume story and future margins.
That pressure on margins is exactly where the story gets interesting, so read the full narrative for Quest Diagnostics to see whether Quest Diagnostics’ testing engine is quietly accelerating.
Curious About Dividend Alternatives?
Fresh ideas move first. By the time every investor piles in, the early momentum is gone and the best entry points are dropping away, so act now and get in early.
- Spot early upside in high quality value names by scanning the 35 high quality undervalued stocks before that edge is fully priced in by the wider market.
- Ride the next wave of automation leaders by tracking the curated 95 robotics and automation stocks while many of these operators are still flying under most radars.
- Position ahead of the energy build out by reviewing the focused 39 power grid technology and infrastructure stocks while these infrastructure stories remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com