


Tokai Carbon (TSE:5301) has caught investors’ attention after a strong year to date, with the share price at ¥2,127.5 and double digit returns over the past month and the past 3 months.
Short term momentum around Tokai Carbon has been strong, with a 9.5% 7 day share price return contributing to a 26.3% gain over 30 days. The 118.9% year to date share price return and 113.3% 1 year total shareholder return suggest a sustained rerating rather than a brief spike.
Scan momentum plays similar to Tokai Carbon by running through the hand picked 17 high quality undervalued stocks that combine strong share price moves with solid underlying fundamentals.
After a move like Tokai Carbon’s, investors are left with a simple fork in the road. Has the rerating already done the heavy lifting, or does the current valuation still leave clear upside on the table?
Price-to-Earnings of 22.9x: Is it justified?
The recent surge in Tokai Carbon’s share price now sits against a P/E of 22.9x, a level that reflects investors paying a premium versus the JP Chemicals industry and the stock’s own estimated fair multiple.
The P/E ratio compares the current share price to expected earnings per share and helps indicate how much the market is willing to pay for each unit of profit. For a manufacturer of carbon-related products with forecast earnings growth of 14.4% per year, this metric becomes a quick shorthand for how confident investors are in those profit forecasts.
For Tokai Carbon, that confidence appears clearly. The P/E of 22.9x is described as expensive relative to the broader JP Chemicals industry average of 12.9x, which represents a strong gap. It is also above the estimated fair P/E of 17.9x, which suggests the current pricing is ahead of the level the market could move towards if sentiment cooled or expectations normalized.
Explore the SWS fair ratio for Tokai Carbon.
Result: Price-to-Earnings of 22.9x (OVERVALUED)
Still, Tokai Carbon’s premium P/E leaves little room for disappointment if earnings forecasts prove optimistic or if demand across key carbon product lines softens.
Find out about the key risks to this Tokai Carbon narrative.
Another View on Tokai Carbon’s Value
The P/E screen presents Tokai Carbon as expensive, yet the SWS DCF model suggests the opposite. With the share price at ¥2,127.5 and an estimated future cash flow value of ¥3,269.37, the stock appears roughly 34.9% undervalued on this framework.
Two very different answers raise a simple question for investors: does the market have earnings multiples right, or are long term cash flows being underpriced?
Look into how the SWS DCF model arrives at its fair value.
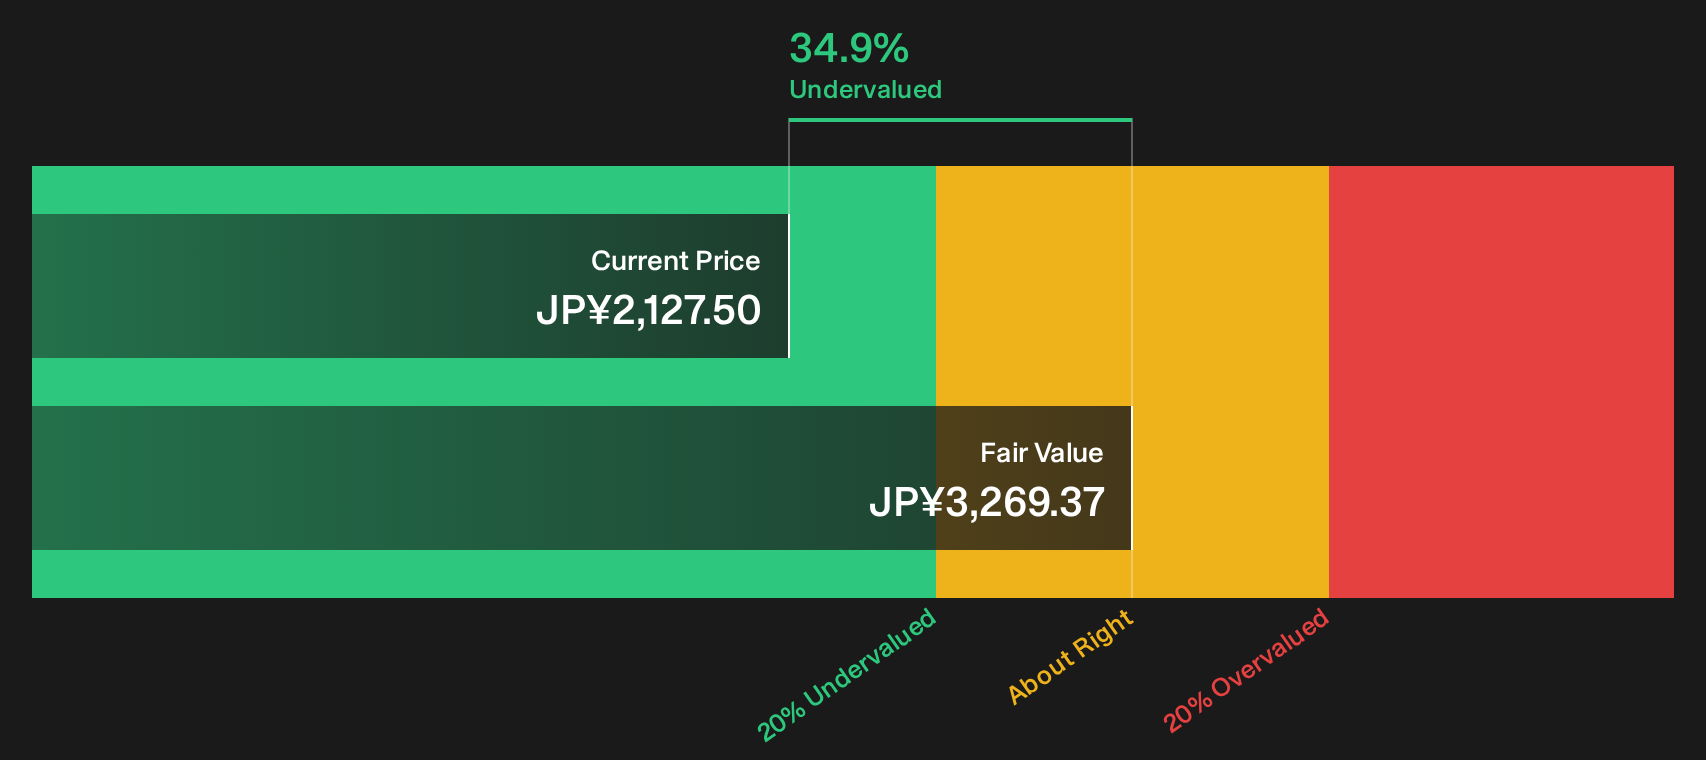
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokai Carbon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Tokai Carbon is clearly divided, with both excitement and caution in the mix, so move quickly, review the key data for yourself, and weigh up the 3 key rewards and 2 important warning signs
Looking for more Tokai Carbon style ideas?
If Tokai Carbon has sharpened your focus on what the market might be missing, do not stop here. Broader idea hunting often reveals the real outliers.
- Target resilient compounding potential by scanning companies with strong balance sheets and fundamentals through this focused list of solid balance sheet and fundamentals (21 results).
- Hunt for mispriced quality by reviewing a curated 17 high quality undervalued stocks that prioritise robust cash flows and healthier financial footing.
- Spot under the radar opportunities early by checking a tightly filtered pool of 75 high quality undiscovered gems before attention and liquidity move in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com