


Why Mitsui High-tec Stock Is Back On Investors’ Radar
Mitsui High-tec (TSE:6966) just paired a strong half year earnings report with a raised full year outlook, putting fresh attention on the stock after a mixed recent share price run.
The group reported half year sales of ¥130,672 million and net income of ¥9,943 million, both higher than the prior year period, alongside earnings per share of ¥54.41 from continuing operations.
Management also lifted full year guidance, now projecting ¥272,000 million in net sales and profit attributable to owners of parent of ¥14,500 million, supported by robust demand, cost controls, and foreign exchange effects.
At a share price of ¥890.0, Mitsui High-tec has delivered a 1-day share price return of 2.89% and a year to date share price gain of 18.98%. However, the 90-day share price return is down 23.21% and the 3-year total shareholder return is down 39.90%, which indicates recent momentum is occurring against a weaker longer term base as investors respond to the earnings beat, raised guidance, and a slightly higher second quarter dividend.
Scan beyond Mitsui High-tec and compare its earnings-driven story with a curated set of 75 high quality undiscovered gems that show strong fundamentals yet still fly under most investors' radar.
The share price has bounced on stronger guidance, while the longer term chart still shows heavy damage. Does Mitsui High-tec now offer enough potential upside, on valuation grounds, to compensate for that history of drawdowns?
Price-to-Earnings Of 18.3x For Mitsui High-tec: Is It Justified?
Mitsui High-tec closed at ¥890.0, and on that price the stock trades on a P/E of 18.3x, which places it between cheaper peers and a more expensive broader semiconductor sector.
The P/E ratio compares the current share price to earnings per share and shows how many years of current profit the market is willing to pay for. For a business like Mitsui High-tec that manufactures tooling, machine tools, and electronic and electrical parts, earnings-based measures tend to matter because they capture both margins and capital intensity in a single number that is easy to line up against competitors.
On one side, analysts flag that the shares look expensive relative to a peer average P/E of 13.8x. This suggests investors are paying a richer price compared with similar companies. On the other side, the same 18.3x P/E sits below the broader JP semiconductor industry at 21x and is also under an estimated fair P/E of 19.5x. This indicates the market valuation could move closer to that higher level if earnings and expectations stay aligned.
Explore the SWS fair ratio for Mitsui High-tec.
Result: Price-to-Earnings of 18.3x (ABOUT RIGHT)
Still, the 5-year total shareholder return is down 43.99%, and weak tooling and machine tools revenue of ¥11,420 million could keep sentiment fragile around Mitsui High-tec.
Find out about the key risks to this Mitsui High-tec narrative.
Another View On Mitsui High-tec’s Valuation
The SWS DCF model paints a far less friendly picture for Mitsui High-tec. At a share price of ¥890, the stock is described as trading well above an estimated future cash flow value of ¥207.1. That gap raises a blunt question: Is the current price leaning too hard on optimistic assumptions?
Look into how the SWS DCF model arrives at its fair value.
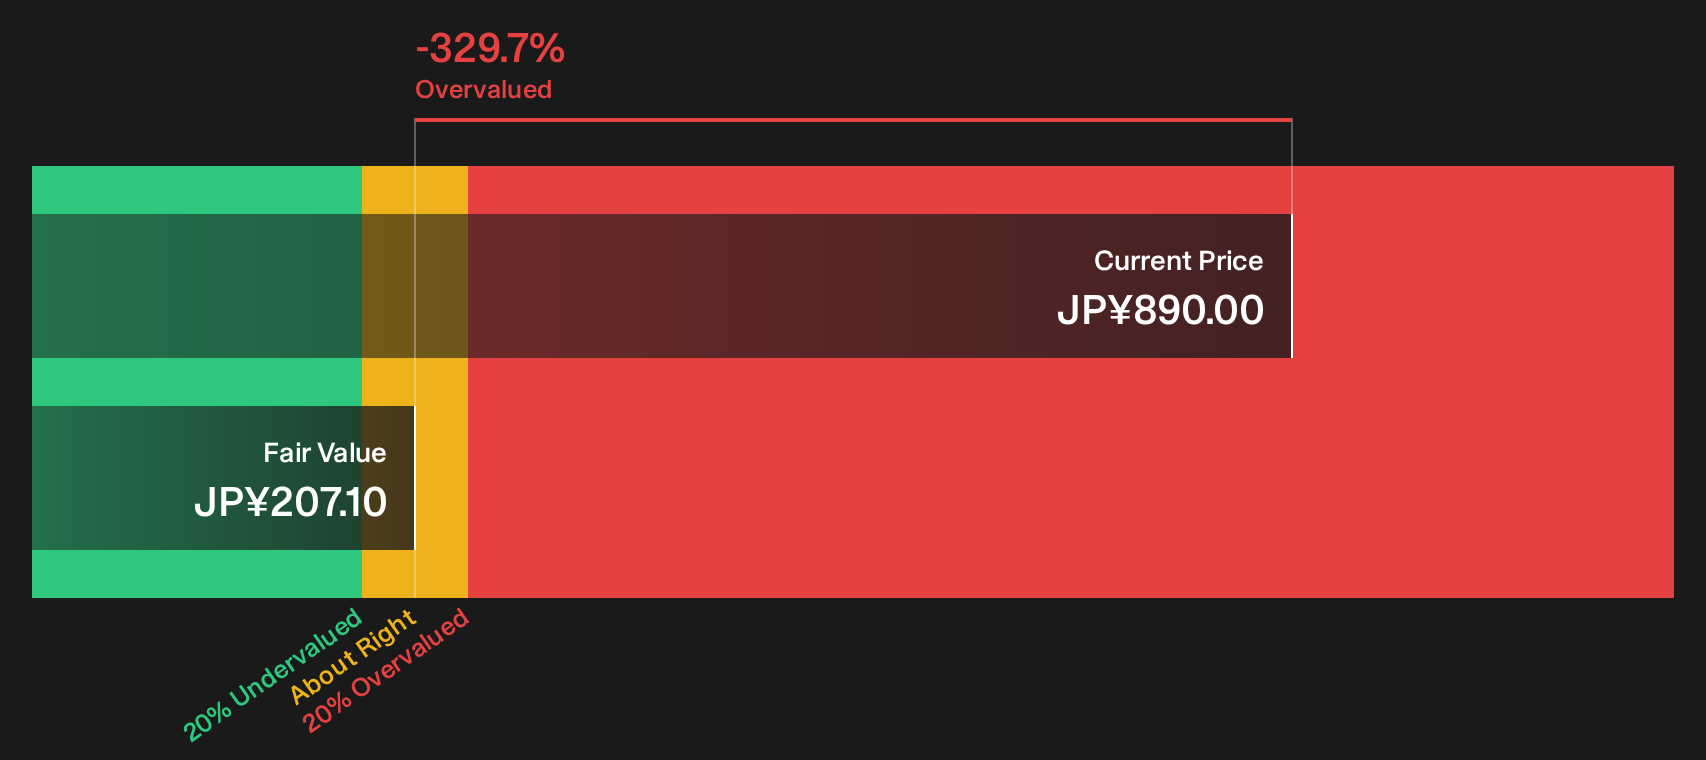
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsui High-tec for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Mitsui High-tec can feel confusing. Move quickly, test the numbers against your own expectations, and weigh the 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Mitsui High-tec?
If Mitsui High-tec has you rethinking your watchlist, broaden your scope with a few focused stock ideas that lean on clear fundamentals and risk filters.
- Target potential mispricings by scanning a curated pool of companies that screen as high quality and attractively priced through the 17 high quality undervalued stocks.
- Stack potential income ideas by reviewing a focused universe of higher yielding payers identified in the 14 dividend fortresses.
- Dial back potential downside by checking companies that score well on resilience and risk using the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com