


Lease renewal raises fresh questions for Entra’s income profile
Entra (OB:ENTRA) has renewed a 2,100 sqm office lease at Tullins gate 2 in Oslo, extending it by nearly six years from 2031 and adding 600 sqm from 2027.
For context, Entra’s share price has softened recently, with a 1-month share price return of 3.44% down and a year-to-date share price return of 10.12% down. The 1-year total shareholder return of 13.99% down contrasts with a 3-year total shareholder return of 9.22% up, suggesting that nearer-term momentum has faded even as long-term holders still sit on gains over three years.
Compare Entra’s lease driven story with other property-focused opportunities by scanning our curated list of solid balance sheet and fundamentals (198 results) tailored for investors who care about income resilience and balance sheet strength.
Entra’s share price has already reset sharply, yet fresh lease security at Tullins gate hints at income that may not be fully reflected. Is most of the rerating already completed, or does the valuation still lag the assets?
Most Popular Narrative: 3% Undervalued
Entra last closed at NOK101.20 against a widely followed fair value estimate of NOK104.40, so the narrative frames the stock as modestly undervalued while hinging on a very specific earnings and margin recovery path.
Analysts are assuming Entra's revenue will grow by 5.0% annually over the next 3 years.
Analysts assume that profit margins will increase from 3.4% loss today to 70.2% in 3 years time.
See why 2 investors see Entra as 3% undervalued.
Result: Fair Value of NOK104.40 (UNDERVALUED)
Still, Entra’s exposure to higher vacancies in smaller offices and its relatively high leverage, combined with refinancing needs within four years, could quickly challenge this underpricing story.
Find out about the key risks to this Entra narrative.
Another View: What Entra’s Cash Flows Are Worth
The analyst narrative around Entra leans on earnings and margin assumptions, yet the SWS DCF model points in a very different direction. On that measure, the shares at NOK101.20 trade far above an estimated future cash flow value of NOK9.27, which implies heavy optimism is already in the price. Where does that leave investors who care more about cash than accounting earnings?
To see how that cash flow view is built and which inputs matter most, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
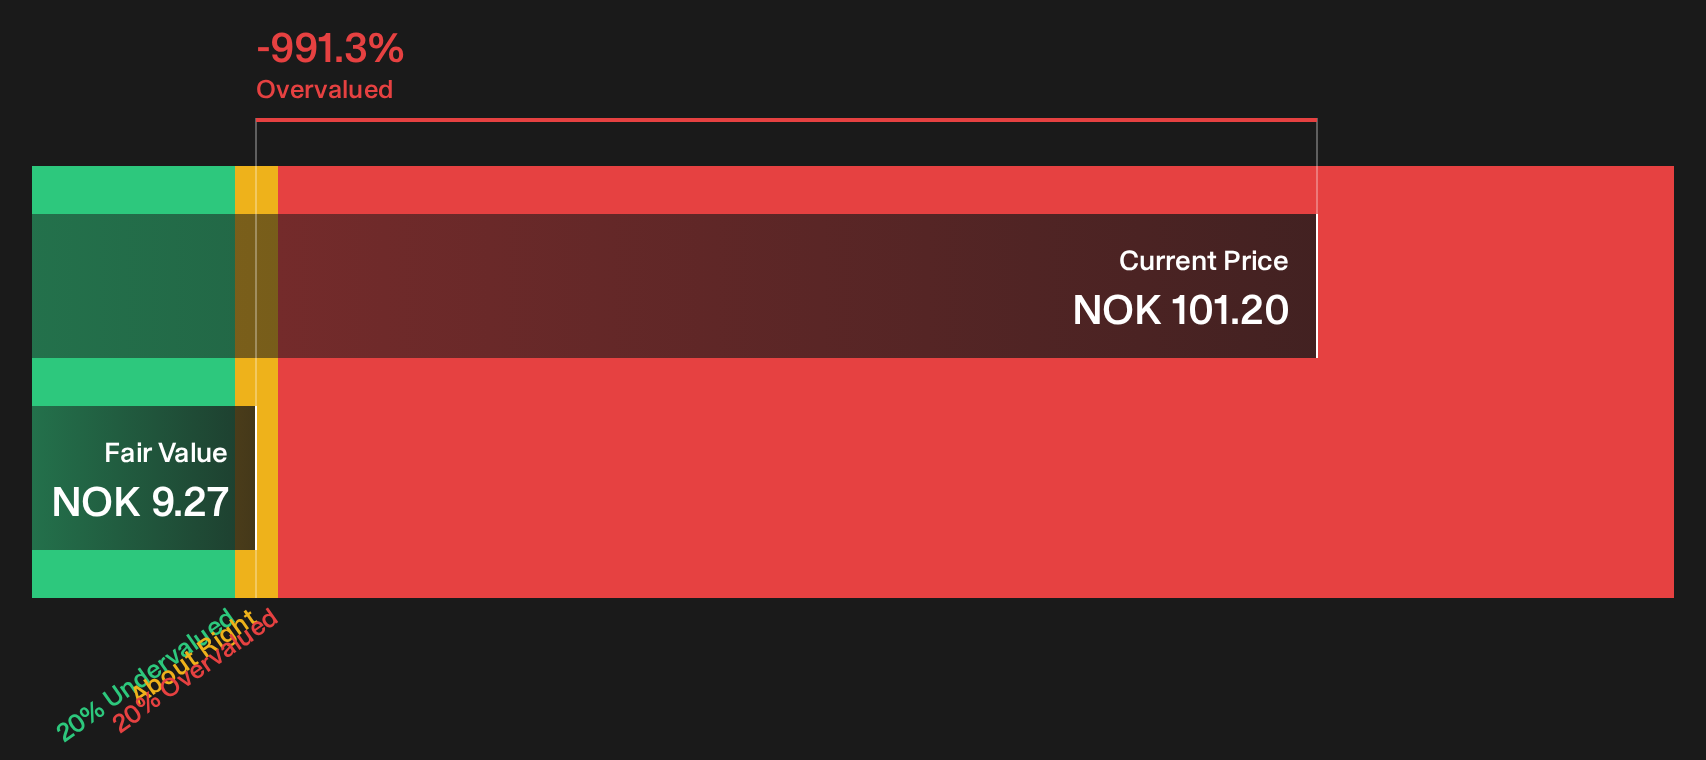
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Entra for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The story so far presents Entra as a combination of opportunity and concern. Move quickly, review the underlying data, and weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Entra?
Do not stop with Entra. Use fresh screens to surface other potential opportunities that fit your risk tolerance, income needs, and return goals.
- Target income strength by scanning a curated set of higher yielding companies through the 162 dividend fortresses.
- Hunt for pricing gaps by reviewing the 173 high quality undervalued stocks that filters for quality fundamentals at relatively low valuations.
- Dial down portfolio risk by focusing on the 229 resilient stocks with low risk scores, which is designed to highlight businesses with more resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com