


- Swiss sportswear group On previously announced a long term partnership with Kylian Mbappé to front its new global football push, adding a fresh competitor in adidas's core soccer category.
- The move spotlights how high profile athlete deals can shift attention and marketing firepower in performance football, raising questions about how adidas allocates sponsorship spend and protects its position in a flagship sport.
- We will examine how adidas's investment narrative, built around growth, brand strength and margins, is tested by On's Mbappé backed soccer entry.
Scan how adidas compares with other potential winners in performance sportswear by reviewing a hand picked set of 615 high quality undiscovered gems that may be flying under most investors' radars.
adidas Investment Narrative Recap
To own adidas, you need to believe the brand can keep turning global demand for performance and athleisure products into healthier earnings, while holding its ground in key sports like football and running. The immediate swing factor is execution in core regions such as North America and China, where pricing, product and direct to consumer rollouts all feed into margins.
The biggest near term risk still sits with costs and competition rather than the Mbappé news. Higher U.S. import tariffs and intense promotional activity can squeeze gross margin if adidas cannot offset them. Entering soccer with a single athlete front man adds pressure, but looks incremental rather than a game changer for near term results.
There are no fresh adidas announcements tied directly to this football headline, which leaves the focus on existing building blocks of the story. The business is leaning on double digit growth in areas like Running and Training, plus a shift toward higher margin direct channels where e commerce and own stores are growing in tandem.
For you, that means linking this Mbappé move by On to whether adidas can keep its product cycle and sponsorship portfolio sharp enough in football while still executing on bigger catalysts. Those include expanding in emerging markets such as Latin America and Asia Pacific, and pushing sustainability and localised product ranges that support pricing and brand strength across the wider portfolio.
What The Current adidas Forecasts Are Actually Asking You To Believe
adidas' narrative projects €31.9 billion in revenue and €2.4 billion in earnings by 2029, which implies revenue growth of 7.0% per year and an earnings increase of about €1.0 billion from earnings today of €1.4 billion.
Uncover why adidas' fair value indicates a 42% potential upside to its current price, which could narrow quickly.
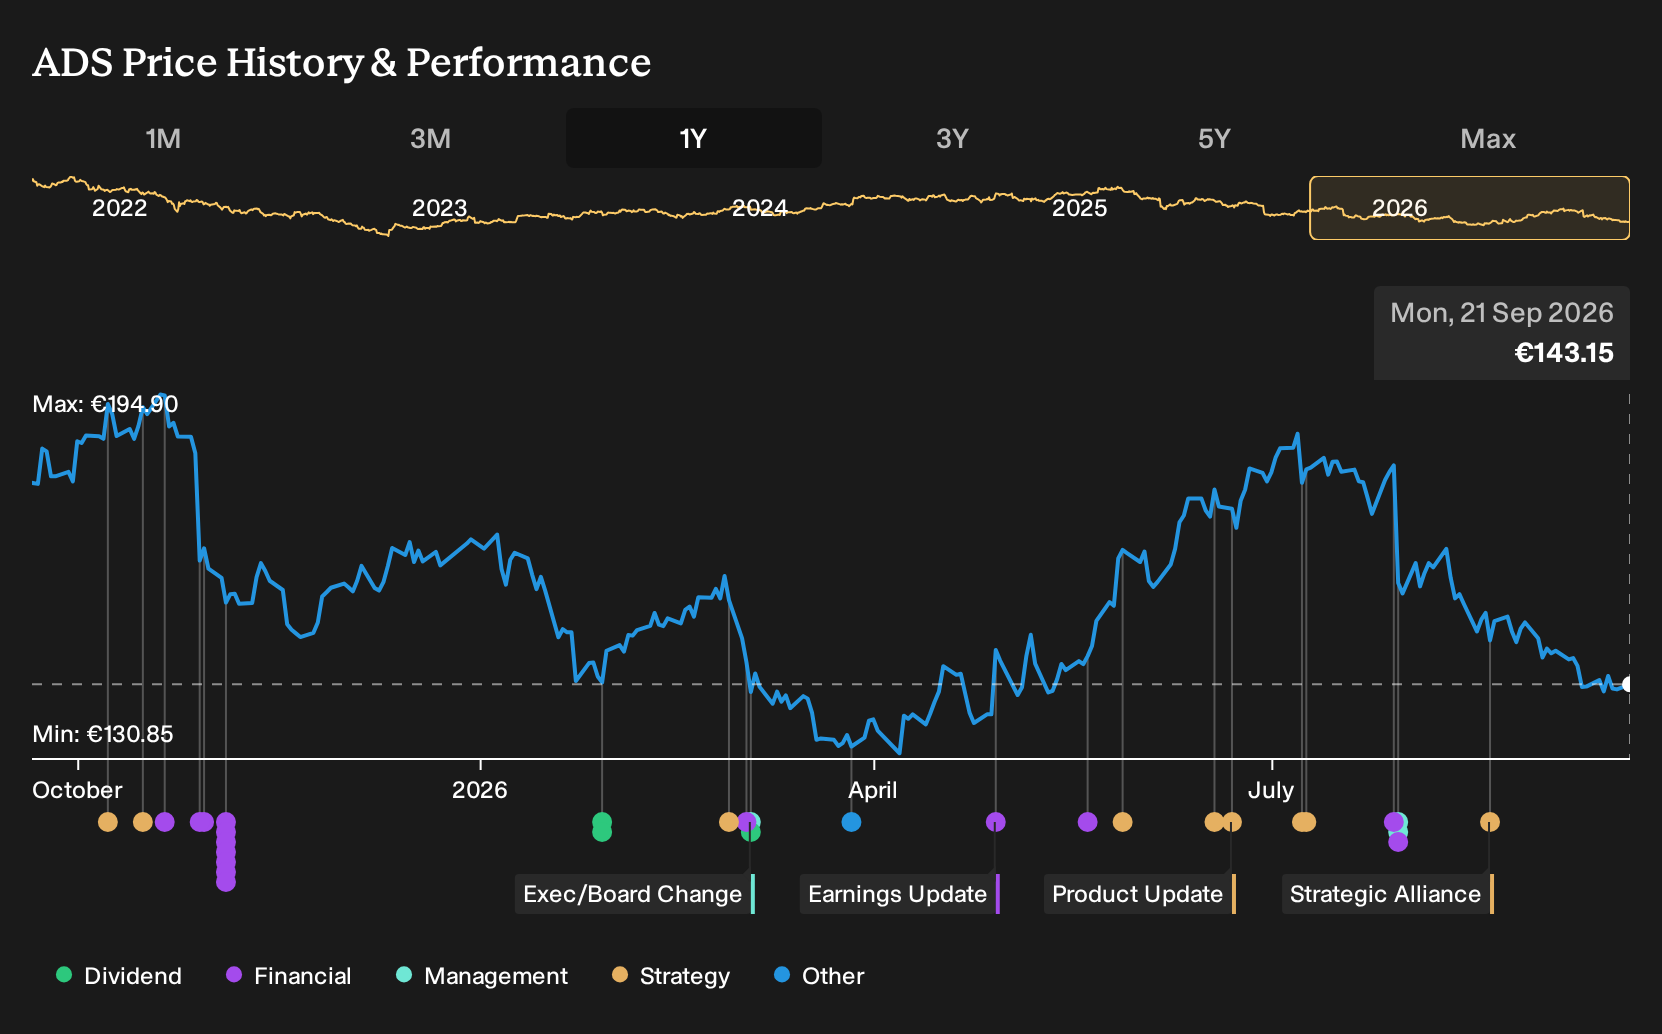
Exploring Other Perspectives
One alternate adidas angle treats rising global visibility in core sports as the real swing factor. The most optimistic analysts were already baking in revenue of about €33.5b and earnings near €2.7b by 2029, before this Mbappé news. You can now ask whether a fresh rival endorsement push nudges those upbeat stories higher or lower.
Explore 6 other adidas fair value estimates, including one that suggests as much as 150% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your adidas research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for adidas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate adidas' overall financial health at a glance.
Looking For More Investment Ideas Beyond adidas?
If this adidas story has sharpened your view on sportswear, it can help to widen the lens and see how other businesses stack up on quality, resilience and income potential using the Simply Wall St Screener.
- If capital protection comes first for you, start with a curated set of 229 resilient stocks with low risk scores that score well on resilience and downside control.
- If balance sheet strength is your filter, narrow the universe to a list of solid balance sheet and fundamentals (198 results) and compare how their financial footing differs from adidas.
- If you prefer companies that the market may be overlooking, scan a 615 high quality undiscovered gems to spot candidates that warrant a closer look before they gain wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com