


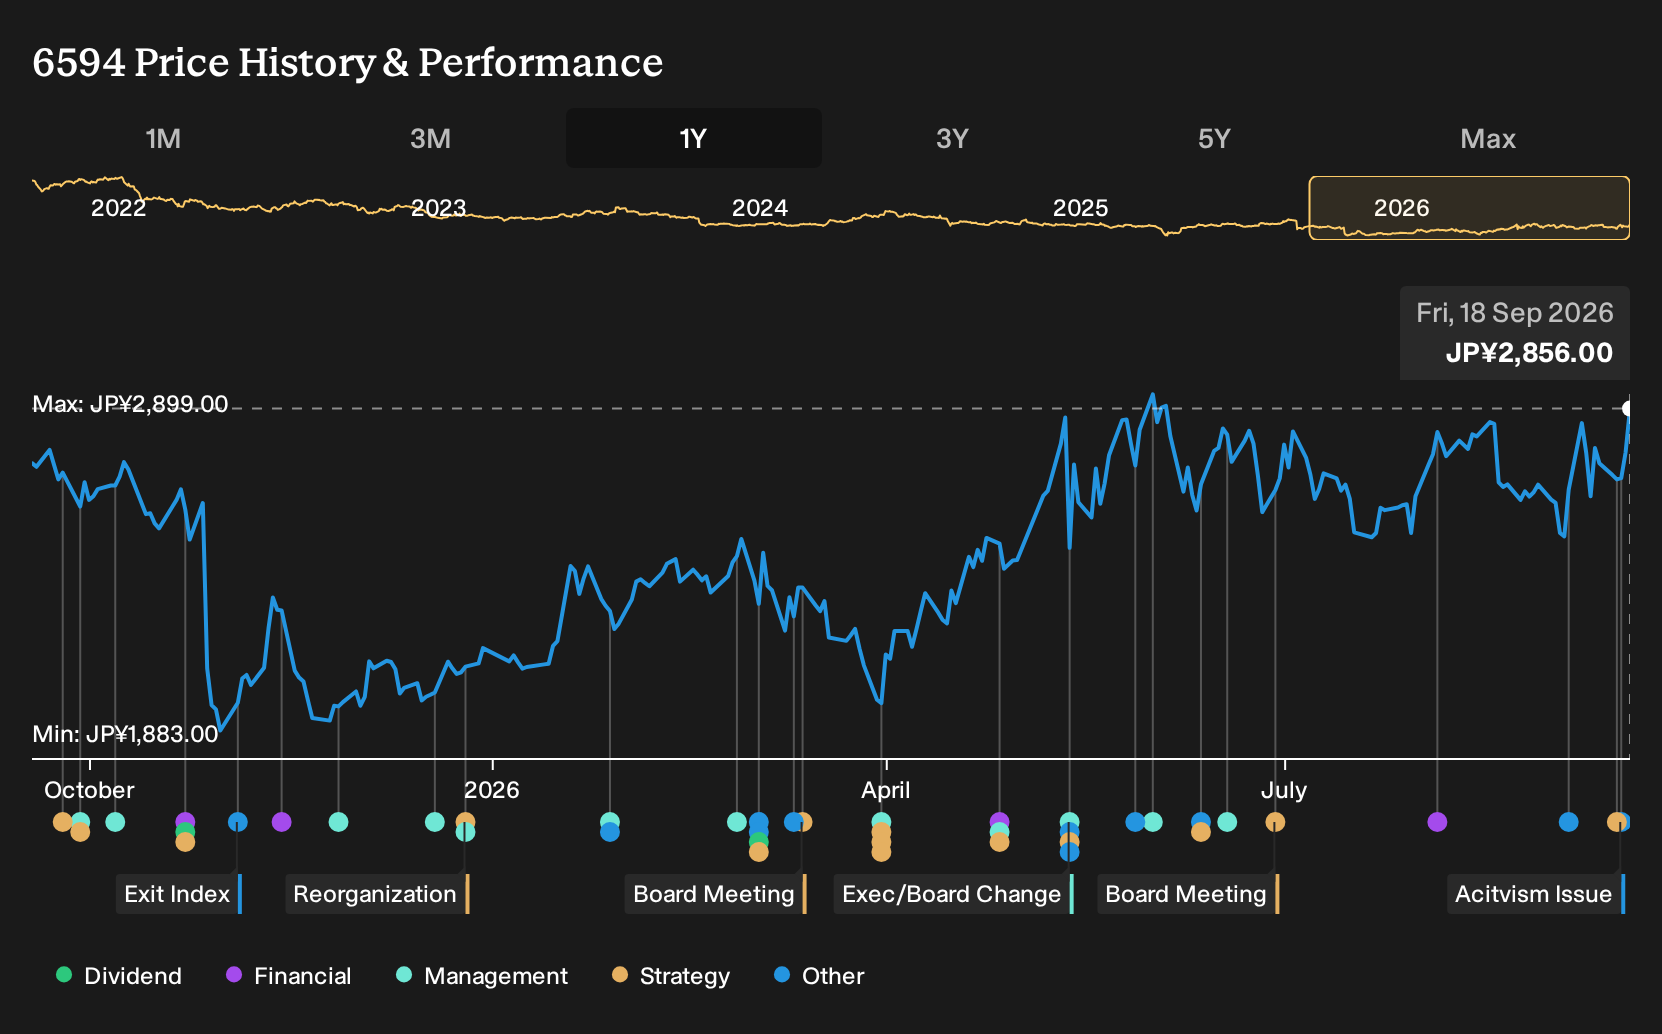
- In mid September 2026, Oasis Management disclosed a stake in Nidec and began pushing for new officers, board reshuffles, capital policy changes, and even the possibility of delisting, along with future proposals on dividends, assets, and management.
- The activism points straight at Nidec’s governance and capital allocation, which sit alongside execution on motors for EVs and data centers as key drivers of long term value.
- We will now assess how Oasis Management’s push for board and capital policy changes could reshape Nidec’s existing investment narrative.
Nidec Investment Narrative Recap
For an investor to stay with Nidec, the key belief is that motors for EVs, data centers, and higher value industrial uses can offset volatility in older product lines and cyclical demand. The short term focus is still on execution in these growth pockets, tight cost control, and keeping restructuring from spilling over into day to day operations.
Oasis Management’s activism touches governance and capital policy more than factory floors. Unless it leads to rapid shifts in restructuring pace or investment priorities, the immediate operational catalyst is unchanged. The biggest near term risk remains choppy demand in data center and automotive markets combined with ongoing restructuring and compliance issues.
The move that ties closest to Oasis’ campaign is Nidec’s board meeting on 15 September 2026 to consider setting a record date for an extraordinary general meeting. That step creates a concrete path for shareholders to vote on potential changes to directors, capital structure, or listing status if proposals are formally tabled.
For you, the relevance is straightforward: any extraordinary meeting that brings governance, director turnover, or capital allocation into focus could influence how Nidec funds EV and data center projects, how aggressively it exits weaker businesses, and how it balances dividends, debt, and reinvestment. Execution on those choices will feed directly into earnings quality and risk around the restructuring plan.
Nidec’s current analyst narrative points to revenues of ¥2,917.1b and earnings of ¥238.0b by 2029, based on 3.7% yearly revenue growth and an earnings increase of about ¥118b from current earnings of ¥120.1b.
Discover why Nidec's fair value points to a potential 9% downside from its current price, suggesting a valuation premium that leaves little room for error.
Exploring Other Perspectives
One big swing factor you may want to watch is how hard Nidec pushes restructuring. The most optimistic analysts already modeled faster clean up, with revenue reaching about ¥3,163.4b and earnings of roughly ¥283.3b by 2029. Oasis’ activism could either reinforce that story or force a rethink once forecasts are updated.
Explore 3 other Nidec fair value estimates, including one that suggests the potential for as much as 30% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nidec research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nidec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nidec's overall financial health at a glance.
Looking for more investment ideas beyond Nidec?
Once you have a view on Nidec, it can help to compare the story with other businesses that share some of the same themes around balance sheets, income potential, and future growth optionality.
- If capital preservation is near the top of your list, start with a basket of companies that screen as relatively resilient by reviewing 21 resilient stocks with low risk scores.
- For readers who care most about quality at a sensible entry point, look across a curated set of potentially mispriced opportunities through 17 high quality undervalued stocks.
- If you prefer businesses with sturdier finances backing their plans, focus on companies with stronger balance sheets and fundamentals using the list of solid balance sheet and fundamentals (21 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com