


Why this new debenture deal matters for Choice Properties Real Estate Investment Trust
Choice Properties Real Estate Investment Trust (TSX:CHP.UN) has just closed a $300 million private placement of senior unsecured debentures, a financing move tied directly to refinancing debt coming due later this year.
The fresh series Y debentures carry a 4.836% coupon and mature in 2033, and management plans to use the cash, alongside other resources, to repay $350 million of series Q debentures due in November 2026.
Recent moves at Choice Properties Real Estate Investment Trust have come against a mixed backdrop, with the unit price at CA$14.96 and a 90-day share price return that declined 8% even as the 1-year total shareholder return reached 6.75% and the 5-year total shareholder return came in at 35.57%. This suggests longer term holders have seen steadier momentum than short term traders focused on the recent pullback and refinancing headlines.
Scan a hand picked 8 resilient stocks with low risk scores that, like Choice Properties Real Estate Investment Trust, focuses on balance sheet resilience and predictable funding rather than short term market swings.
Choice Properties trades below both analyst targets and one estimate of fair value after this refinancing step. Is that a simple discount, or a warning that the market’s caution on this REIT is justified?
Preferred Price-to-Sales of 3.4x for Choice Properties: Is it justified?
On the numbers, Choice Properties Real Estate Investment Trust trades on a P/S of 3.4x, and that level screens as inexpensive relative to both its peer group and one estimate of fair value. With the units at CA$14.96 and trading at a 29.8% discount to an internal fair value estimate based on future cash flows of CA$21.30, the current tag points to a market that is pricing in plenty of caution.
The P/S multiple simply compares the market value of the trust to the revenue it generates. For a REIT such as Choice Properties, which booked CA$1.46b of revenue across mainly retail and industrial assets in Canada, this metric can be a cleaner indicator than earnings based ratios when the income statement shows a loss or heavy non cash items.
What really jumps out is the relative gap. Management oversees a platform that is forecast to grow revenue by 15.8% a year, yet the units trade at a P/S of 3.4x versus 6.3x for the North American retail REIT industry and a peer average of 5.4x. Against an estimated fair P/S of 8.5x, the current valuation implies the market is applying a meaningful discount that could narrow if the forecast top line growth and refinancing plans continue to support the balance sheet.
Explore the SWS fair ratio for Choice Properties Real Estate Investment Trust.
Result: Price-to-Sales of 3.4x (UNDERVALUED)
Still, Choice Properties Real Estate Investment Trust faces pressure if higher funding costs persist or if Canadian retail tenants weaken and put leasing income under strain.
Find out about the key risks to this Choice Properties Real Estate Investment Trust narrative.
Another View on Choice Properties valuation
There is a second lens on Choice Properties Real Estate Investment Trust. The SWS DCF model points to a future cash flow value of CA$21.30 per unit versus the current CA$14.96 price, which reads as undervalued. Does that signal mispricing, or simply reflect the risks around today’s loss making status and funding costs?
Look into how the SWS DCF model arrives at its fair value.
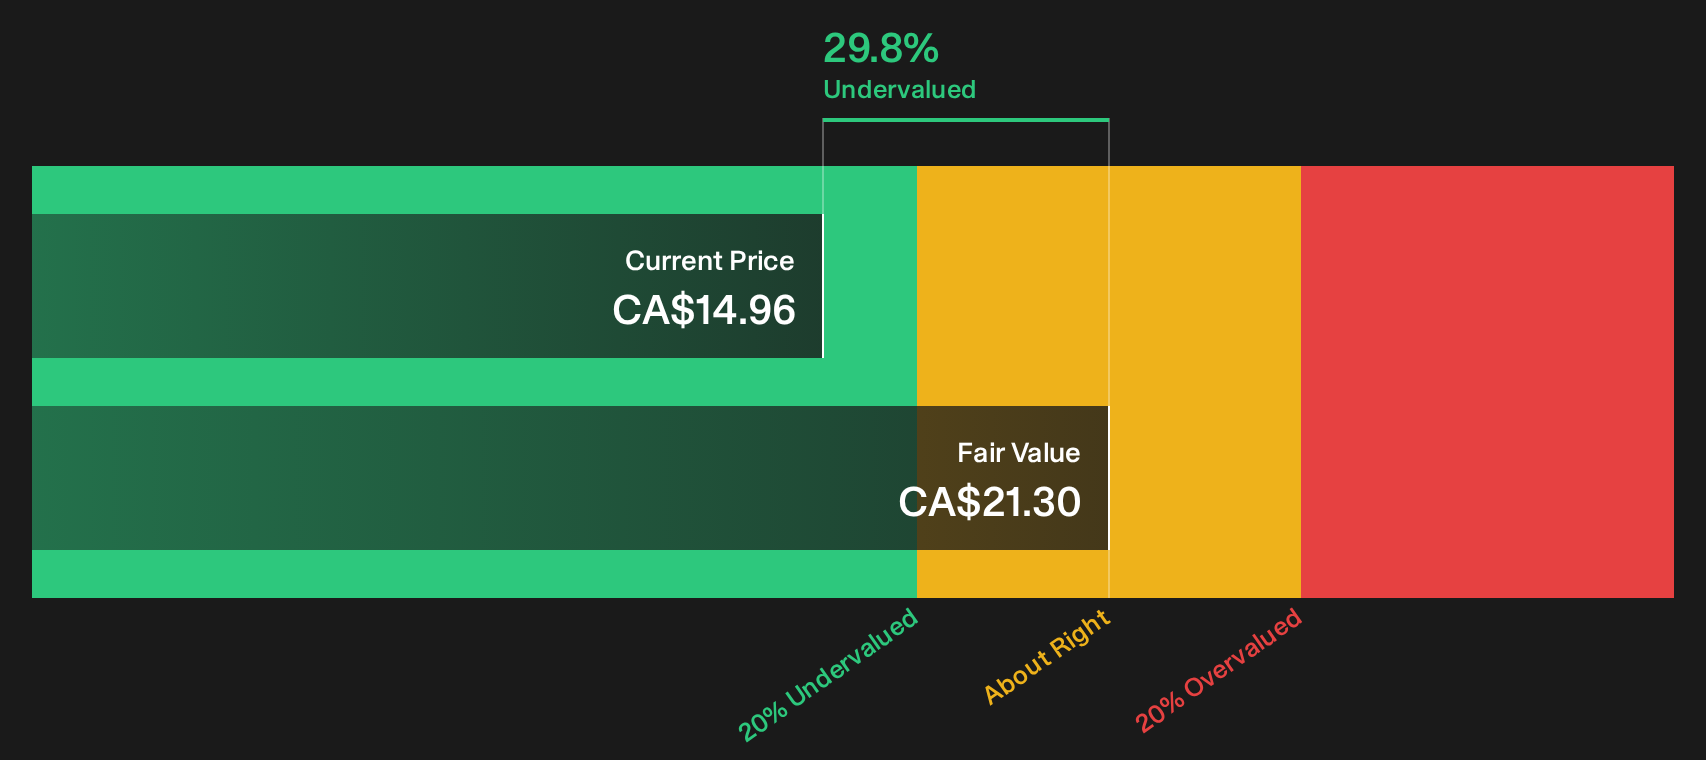
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Choice Properties Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Choice Properties valuation and funding risk can feel messy. Treat this as your cue to move quickly and stress test the story against your own expectations using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Choice Properties?
If Choice Properties Real Estate Investment Trust has you thinking harder about price, debt and cash flows, then it makes sense to widen your lens to other opportunities using structured screeners.
- Target dependable income streams by reviewing a focused set of higher yield opportunities through the 1 dividend fortresses.
- Spot potential value gaps by scanning the 7 high quality undervalued stocks that filter for quality fundamentals at what may be discounted prices.
- Strengthen your watchlist by checking a list of solid balance sheet and fundamentals (7 results) that highlights businesses with sturdier finances when conditions get rough.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com