


James Hardie Industries (ASX:JHX) is back in front of housing-focused investors, presenting at the Zelman Housing Summit 2026 in Boston, a setting that puts its fibre cement and siding portfolio under close scrutiny.
Recent trading tells a mixed story for James Hardie Industries. The 1 day share price return of 1.81% comes after a 30 day share price decline of 13.56%. However, the year to date share price return of 20.27% and 1 year total shareholder return of 25.27% point to momentum that has been building rather than fading, even as longer term total shareholder returns over 3 and 5 years remain in decline.
Scan how James Hardie Industries stacks up against other housing exposed materials players by reviewing our curated list of list of solid balance sheet and fundamentals (12 results).
James Hardie Industries appears to be a solid housing supplier based on recent earnings and long-run brand strength. After the sharp 30-day pullback and still-positive one-year return, the question is whether that quality is now reasonably priced or still demanding a premium.
Most Popular Narrative: 4% Overvalued
Against the last close at A$37.03, the most followed narrative pegs James Hardie Industries at a fair value of A$35.59, implying a modest premium that investors need to weigh against its housing exposure and acquisition story.
Synergy capture from the AZEK merger is already showing tangible cost reductions, with management reaffirming cost savings targets ($125 million over 3 years) and planning for over $500 million of commercial synergies within 5 years, providing clearer visibility to potential EBITDA margin expansion and earnings growth.
See why 37 investors see James Hardie Industries as 4% overvalued.
Result: Fair Value of A$35.59 (OVERVALUED)
Still, weakness in single family construction in key US regions and high post acquisition debt levels could easily unsettle the James Hardie Industries narrative.
Find out about the key risks to this James Hardie Industries narrative.
Another View On James Hardie Industries Valuation
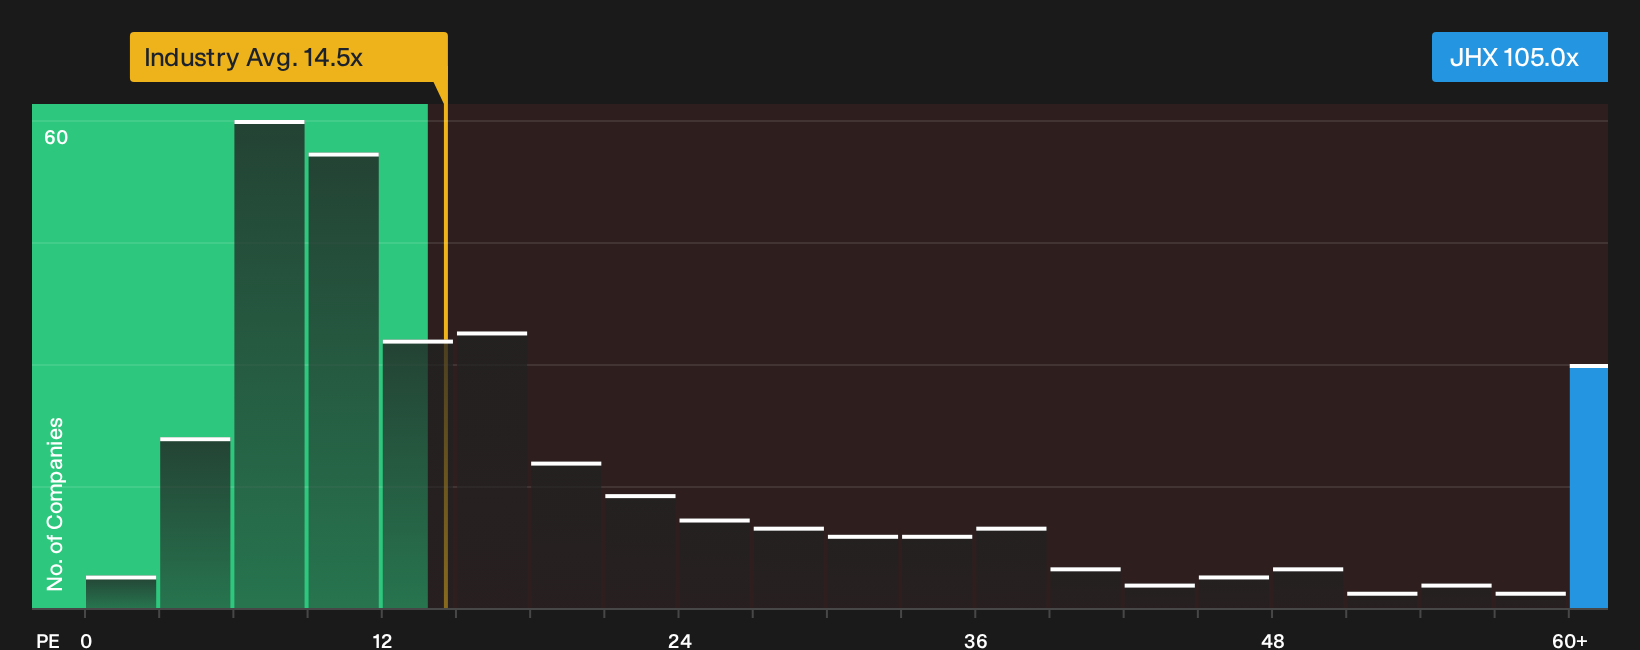
Price based on earnings paints a very different picture for James Hardie Industries. The stock trades on a P/E of 105x, compared with 14.5x for the global Basic Materials industry and 30.1x for peers, while the fair ratio is 27.3x. That is a wide gap. For investors, the question is whether this premium reflects future earnings strength or simply stretches valuation risk.
To see how this stacks up against the underlying numbers, take a closer look at our valuation breakdown. This includes how today’s multiple compares with the fair ratio over time, through See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out James Hardie Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around James Hardie Industries can be useful, but your own verdict matters more. Move quickly to review the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond James Hardie Industries?
If James Hardie Industries has your attention, do not stop here. Broader ideas can sharpen your watchlist and reveal opportunities you might otherwise miss.
- Spot potential turnaround stories early by scanning the 19 elite penny stocks with strong financials that already show stronger financial footing than most micro caps.
- Zero in on quality at a marked-down price by filtering for 5 high quality undervalued stocks that pair robust cash generation with healthier balance sheets.
- Build a cash flow focused shortlist by checking out 3 dividend fortresses that aim to combine higher yields with resilient payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com