


The Federal Reserve’s latest rate hike has pushed borrowing costs higher and increased pressure on heavily indebted businesses worldwide. Australian investors watching this play out can look at companies where cash continues to flow steadily, yet the share price still lags what discounted cash flow models suggest is fair value. This article highlights three stocks in that group and explains why their pricing gap may warrant closer attention.
The three stocks profiled below are only a sample of what this cash flow lens is picking up, and the full screen surfaced 1 more company with an equally compelling story that is not covered here.
If you want to go straight to the source and identify candidates that align with your own risk and return preferences, analyze the full Undervalued Stocks Based On Cash Flows screener through the Undervalued Stocks Based On Cash Flows screener.
Regis Resources (ASX:RRL)
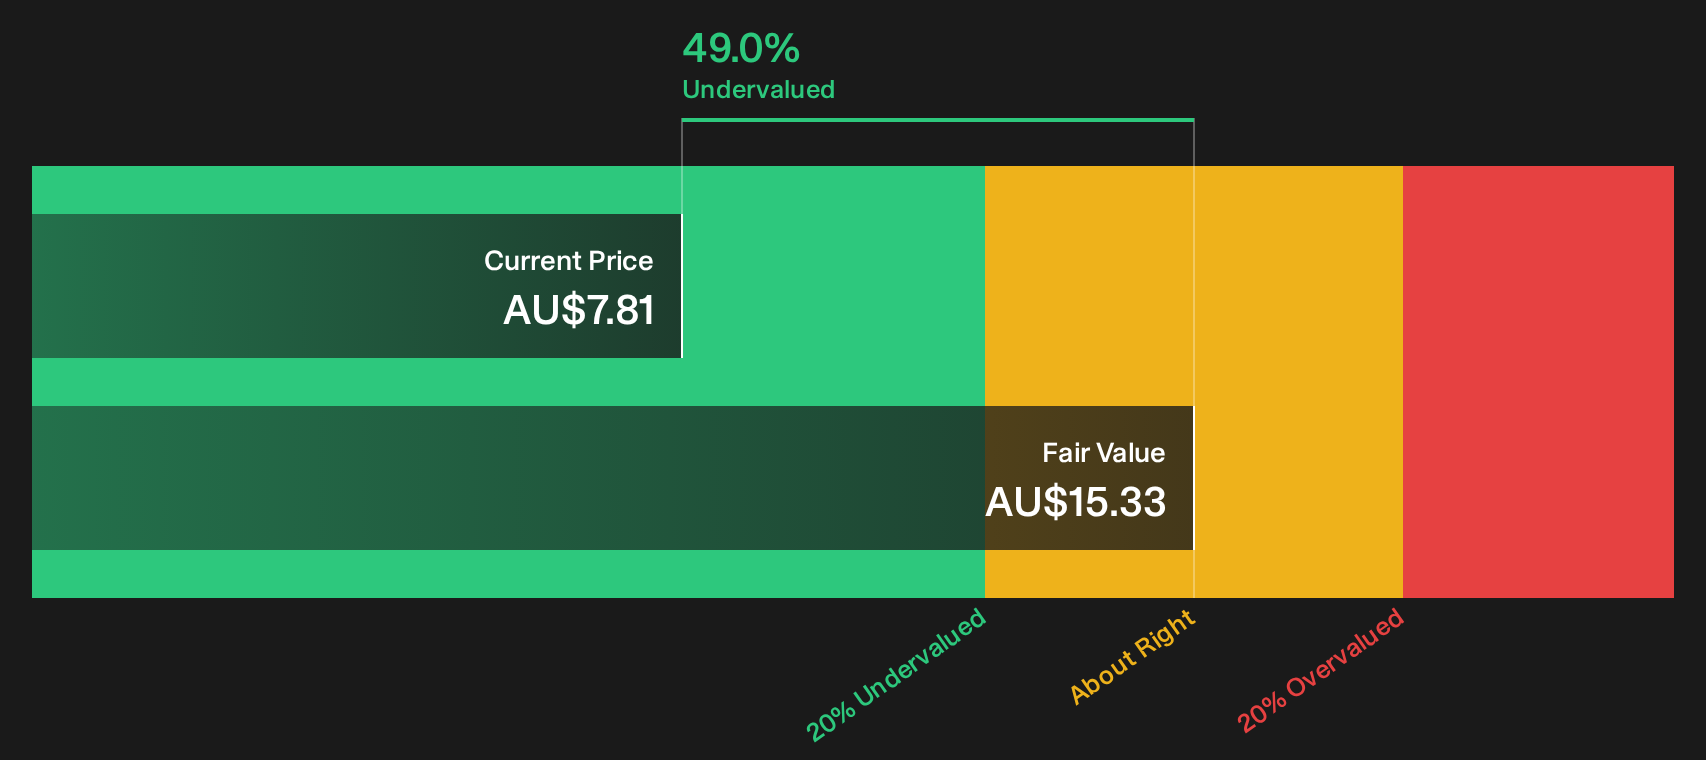
Regis Resources is a pure play on Australian gold, with the Duketon project generating the bulk of operating cash flows that anchor its place in this cash flow based value screen.
Regis Resources develops and operates gold projects across Australia, with Duketon producing about A$1.45b of revenue and Tropicana about A$897 million, all within Australia, and the group valued at roughly A$5.9b by the market.
"Regis's robust balance sheet, with record net cash and an undrawn $300 million facility, provides significant scope for transformational M&A, including the potential acquisition of additional stakes in strategic assets like Tropicana or synergistic gold-copper projects, which could deliver substantial production growth and earnings per share accretion."
What happens if a single assumption on future margins proves too conservative is where the Regis Resources cash flow story gets interesting.
If that margin shift is what interests you, read the full narrative for Regis Resources to see how Regis Resources' cash profile could be decoupling from current market expectations.
NobleOak Life (ASX:NOL)
NobleOak Life is a Sydney based insurer focused on life, income protection, TPD, trauma and related cover, where recurring policy premiums underpin the cash flow story that feeds DCF models. It generated about A$399 million from strategic partnerships, A$106 million from direct channels and A$15 million from Genus, with a market value near A$123 million.
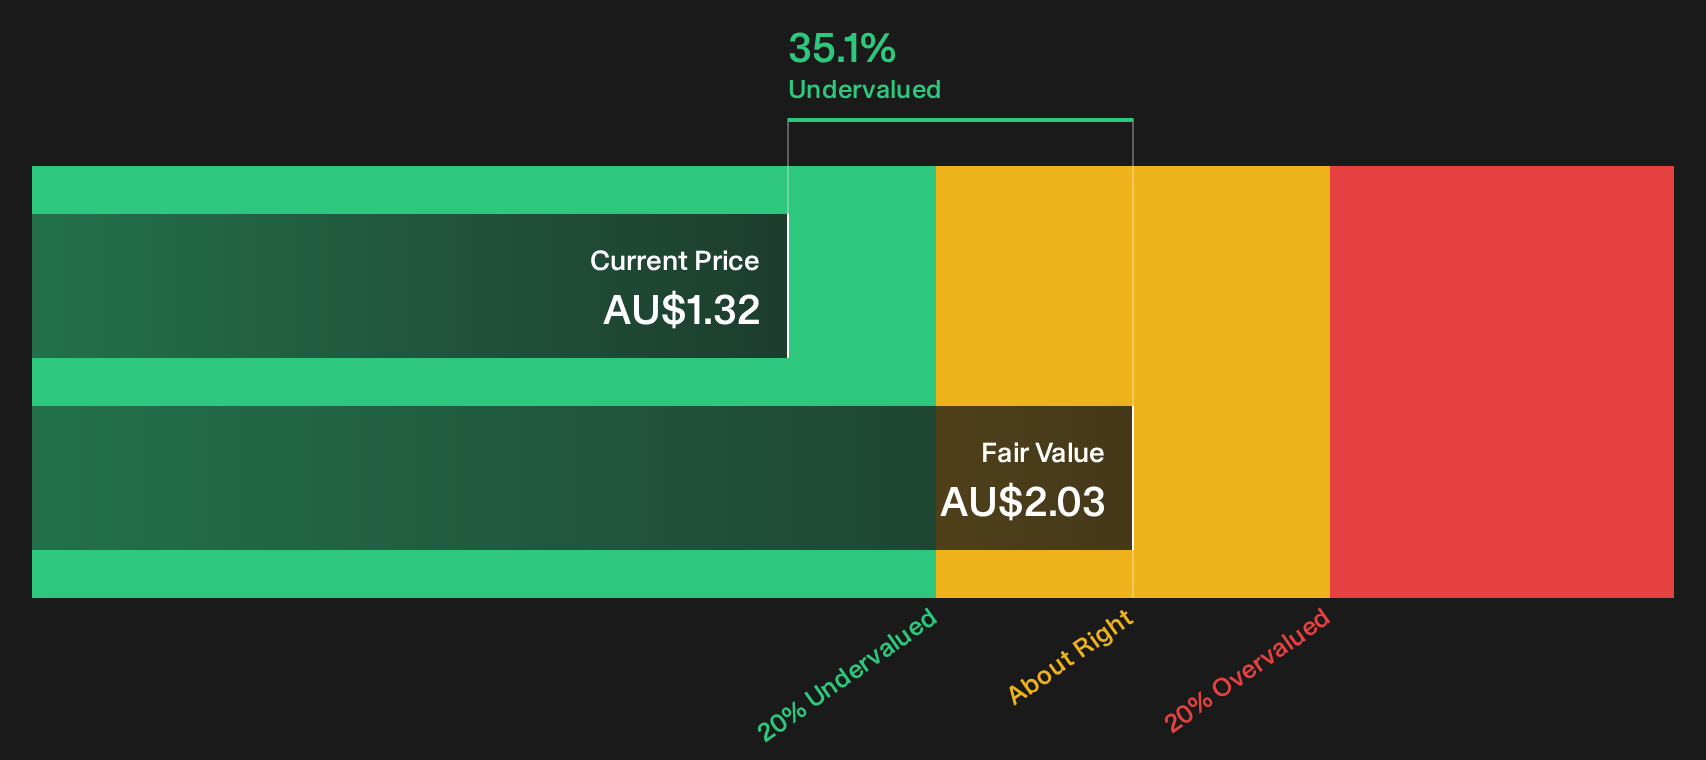
NobleOak Life links closely to this cash flow screen because its long term life insurance policies convert into repeat premium receipts that can be modelled with more clarity than many cyclicals. The stock trades at a discount to the screener’s A$2.03 DCF estimate and on a low 8.7x P/E. The key issue is what happens if claims experience shifts just a little from recent patterns.
If that claims lever has your attention, pull up the analysis report for NobleOak Life and see how NobleOak Life’s cash flows and valuation could be mispriced.
JB Hi-Fi (ASX:JBH)
JB Hi-Fi is a household electronics and appliances retailer where everyday purchases and after-sales services feed into the kind of recurring cash flows this DCF led screener is built to spot, with a market value around A$7.3b across JB Hi-Fi, The Good Guys and e&s.
JB Hi-Fi sells everything from TVs and laptops to fridges and gaming gear, mainly through JB Hi-Fi Australia at about A$7.4b in revenue, The Good Guys at roughly A$2.9b, JB Hi-Fi New Zealand near A$431 million and e&s around A$273 million, with after-sales services helping convert these sales into repeat cash flows.
That mix of everyday tech and household essentials means JB Hi-Fi sits close to the screener’s sweet spot, where reliable cash generation rather than blue-sky stories drives the valuation debate and where even small shifts in service income can move the DCF needle.
"The acquisition of e&s is expected to enhance JB Hi Fi's access to premium home appliances and expand the customer base to include builders and commercial clients, potentially boosting revenue growth."
What really matters now is how one quiet change in the balance between high-margin services and sheer volume of product sales plays out.
If that shift in the services mix has you thinking about where JB Hi-Fi’s cash engine could be heading next, read the full narrative for JB Hi-Fi to see how that balance might be quietly accelerating value.

Seeking Alternatives Before The Crowd Moves
Fresh opportunities can move from quiet to flying once momentum builds and early buyers get caught on the right side of a breakout. Scan what is still under the radar for now and act now.
- Track cash rich businesses quietly building momentum and screen for potential low risk compounders using the list of solid balance sheet and fundamentals (12 results).
- Spot companies riding the AI infrastructure build out before valuations run away by filtering through the 86 AI infrastructure stocks.
- Target potential income workhorses with payouts that could support a portfolio tilt toward cash returns using the 3 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com