


- CorVel Corporation recently launched its CareMC Accelerator for Guidewire ClaimCenter, connecting claims activity and Managed Care operations through secure Single Sign-On, structured data exchange, and real-time status updates directly within the claims workflow.
- The integration’s focus on automated data transfer, configurable workflows, and reduced IT burden positions CorVel as a practical infrastructure partner for carriers seeking to reduce manual administration in workers’ compensation and medical management.
- We will look at how CorVel's investment narrative is shaped by this CareMC Accelerator integration that streamlines managed care within claims.
Scan how CorVel's CareMC accelerator fits into a broader push toward more automated claims infrastructure by reviewing a curated set of 30 resilient stocks with low risk scores that prioritize workflow efficiency and disciplined execution.
What Is CorVel's Investment Narrative?
CorVel appeals most if you believe in a long haul story around disciplined execution in workers’ comp and medical cost containment. The firm already leans heavily on technology across Managed Care, and the new CareMC Accelerator for Guidewire ClaimCenter fits cleanly into that playbook by trying to remove friction where adjusters actually work. That is an operational bet, not a marketing one. You are essentially backing management to keep turning workflow tools into durable service relationships rather than one off pilots.
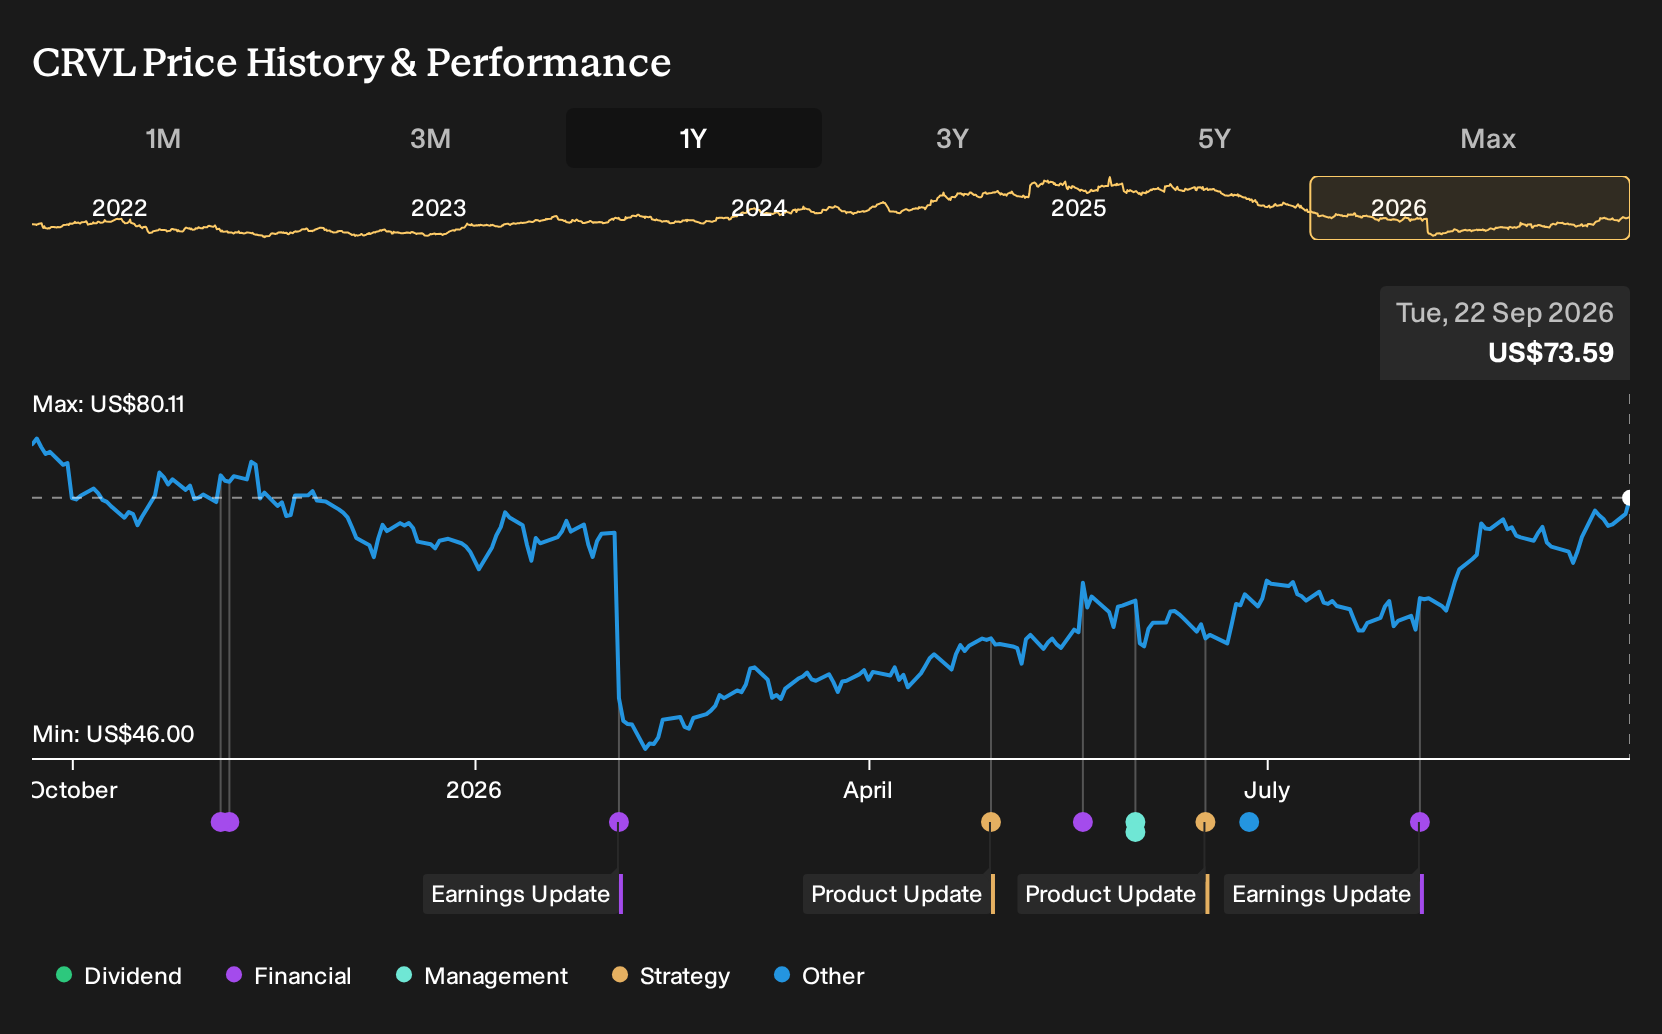
In the near term, the CareMC tie in could matter at the margin for sales conversations with Guidewire oriented carriers, but it will not rewrite the core drivers overnight. Earnings have grown 14.2% per year over the past 5 years, P/E sits at 32.2x against a 24x US Healthcare industry average, and return on equity is 28.2%. That mix puts the focus on execution quality and pricing power in Managed Care more than on headline growth forecasts, especially with recent share performance trailing the broader US market and healthcare sector.
That said, anyone looking at CorVel purely through the lens of software like the CareMC Accelerator still needs to weigh the fact that ...
There's only one way to know the right time to buy, sell or hold CorVel. Head to Simply Wall St's company report for the latest analysis of CorVel's Fair Value.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CorVel research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CorVel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CorVel's overall financial health at a glance.
Looking For More CorVel Style Investment Ideas?
If CorVel's mix of workflow tools and disciplined cost control appeals to you, it can help to widen the lens and compare it with other businesses that share some of those risk and return traits. The Simply Wall St Screener lets you filter for different types of opportunities so you can build a watchlist that actually matches your own approach rather than someone else's model portfolio.
- For investors who care about balance sheet strength as much as income statements, scan a list of solid balance sheet and fundamentals (23 results) that can help anchor a more resilient portfolio.
- If you prefer ideas that the market may not be fully focused on yet, review a 16 high quality undiscovered gems that combine quality fundamentals with lower profile coverage.
- When income is a priority, focus on cash return potential by screening through 7 dividend fortresses that aim to pair higher yields with business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com