


Genmab has delivered a 24.9% return over the past year, which puts fresh attention on whether the current share price is in line with what its earnings can reasonably support. With the stock around DKK 2,279 at the last close, the question becomes how much of that performance is grounded in the underlying profit engine of the business.
- The 24.9% gain over 1 year raises the stakes for anyone asking if Genmab's valuation is being driven more by solid earnings than by sentiment.
- The company’s model, which converts research into partnered therapies and royalty streams, can have a direct impact on how consistently earnings translate into cash that could underpin today’s pricing.
- Your read on Genmab is one view; the desks covering it have another. See what analysts think Genmab's shares could be worth.
The stock's next move may depend on whether Genmab's current earnings level is enough to justify where the shares trade today.
If you are weighing whether Genmab's 24.9% one-year return aligns with its earnings, it can be helpful to benchmark the stock against a wider field using 171 high quality undervalued stocks
Does Genmab Look Fairly Valued on Earnings?
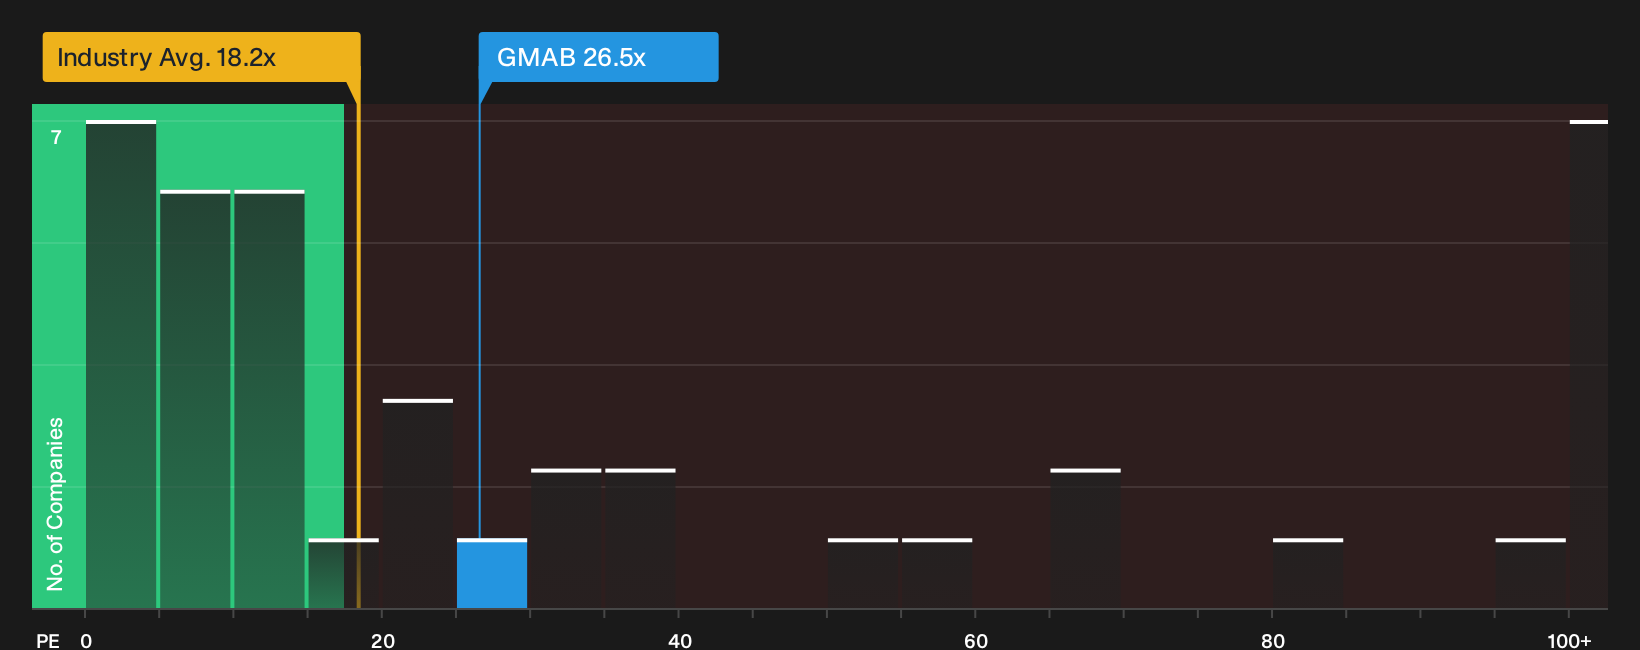
The P/E ratio suits Genmab because earnings are a key way investors frame the value of a profitable biotech with royalty and partnership income. On this measure, Genmab trades on a P/E of 26.5x, which is close to the Biotechs sector average of 25.8x and also near the 26.5x level implied by the peer set on average at 15.4x and the tailored fair ratio used here. That clustering suggests the share price is not significantly detached from where comparable earnings streams in this area have been marked.
The fair ratio reflects what Genmab might be expected to trade on given its margins, growth profile, size and risk. The current 26.5x sitting close to that reference point points to a valuation that does not clearly screen as expensive or cheap on earnings alone. For anyone weighing the recent 24.9% return, this leaves the P/E as a starting point that needs to be considered alongside pipeline risk, partner concentration and cash generation to judge whether the stock still fits their return and risk targets. Explore the numbers behind Genmab's P/E valuation.
The Genmab Narrative: What Would Justify Today's Price?
Genmab's recent P/E discussion sets up the next step, which is to spell out what kind of future earnings profile would need to play out for the valuation to look clearly high or clearly low. Simply Wall St Narratives on the Community page turn that into specific, trackable storylines about Genmab's future growth, margins and profitability, each treating fair value as a hypothesis about the business that you can watch either hold up or break over time.
Genmab splits opinion, with one camp arguing the stock underprices its pipeline and balance sheet, while the other worries about concentration risk and future pricing pressure.
Bull case: 22% undervalued
"The accelerating global shift to targeted, personalized medicine and the aging population are fueling massive structural growth in demand for advanced antibody therapies…"
Discover why this Narrative puts Genmab at 22% undervalued.
Bear case: 39% overvalued
"Highly concentrated dependence on a few commercial assets, principally DARZALEX, EPKINLY, and Tivdak, and a continued lack of diversified late-stage wholly owned programs mean long-term earnings are at risk…"
Explore why this Narrative puts Genmab at 39% overvalued.
One more Genmab angle that could shift how you see the stock
Everything so far has focused on where Genmab trades today, but professional coverage also sketches out where profits and sales are projected to head over the next few years. Explore where analysts expect Genmab to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com