


- Aya Gold & Silver reported high grade drill results at the Zgounder Silver Mine in Morocco and an updated Boumadine Preliminary Economic Assessment with detailed production, recovery and payability assumptions.
- The combination of very high silver grades at Zgounder and a Boumadine plan built around three payable concentrates tightens Aya Gold & Silver’s focus on Morocco based growth and metallurgical execution.
- This article examines how Aya Gold & Silver’s investment narrative is reframed by Boumadine’s updated economics and metal payability assumptions.
Aya Gold & Silver Investment Narrative Recap
To own Aya Gold & Silver, you need to believe the combination of Zgounder and Boumadine can support a long life, Morocco focused precious metals business while keeping costs and execution under control. The latest Zgounder drill results speak directly to that belief by pointing to very high grade mineralization at depth and near surface in the open pit area.
In the near term, the key catalyst is how efficiently Aya turns these intercepts into mine plans, reserves and practical throughput at Zgounder while advancing Boumadine on its new PEA case. The biggest risk remains operational, particularly ore dilution, metallurgy at Boumadine and single country exposure, which the new results do not materially change.
The updated Boumadine Preliminary Economic Assessment released on 9 September 2026 ties tightly into this latest Zgounder news. Investors now have high grade silver drill results at the existing producing asset and a study that outlines a three concentrate, gold and silver driven development project using a conventional flotation flowsheet backed by years of testwork.
Regarding catalysts, the Boumadine PEA puts concrete numbers around payability, recoveries and planned throughput. It also notes that future roasting and leaching could offer another processing route, even if this sits outside the current plan. The operational risk is clear. Aya must execute on mine construction, cost control and concentrate marketing in the same Moroccan jurisdiction where all its growth is concentrated.
Aya Gold & Silver’s current consensus narrative points to revenues of $346.6 million and earnings of $81.5 million by 2029, with analysts assuming revenue stays broadly flat while profit margins trend lower and earnings decline by $31.2 million from $112.7 million today.
Uncover why Aya Gold & Silver's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
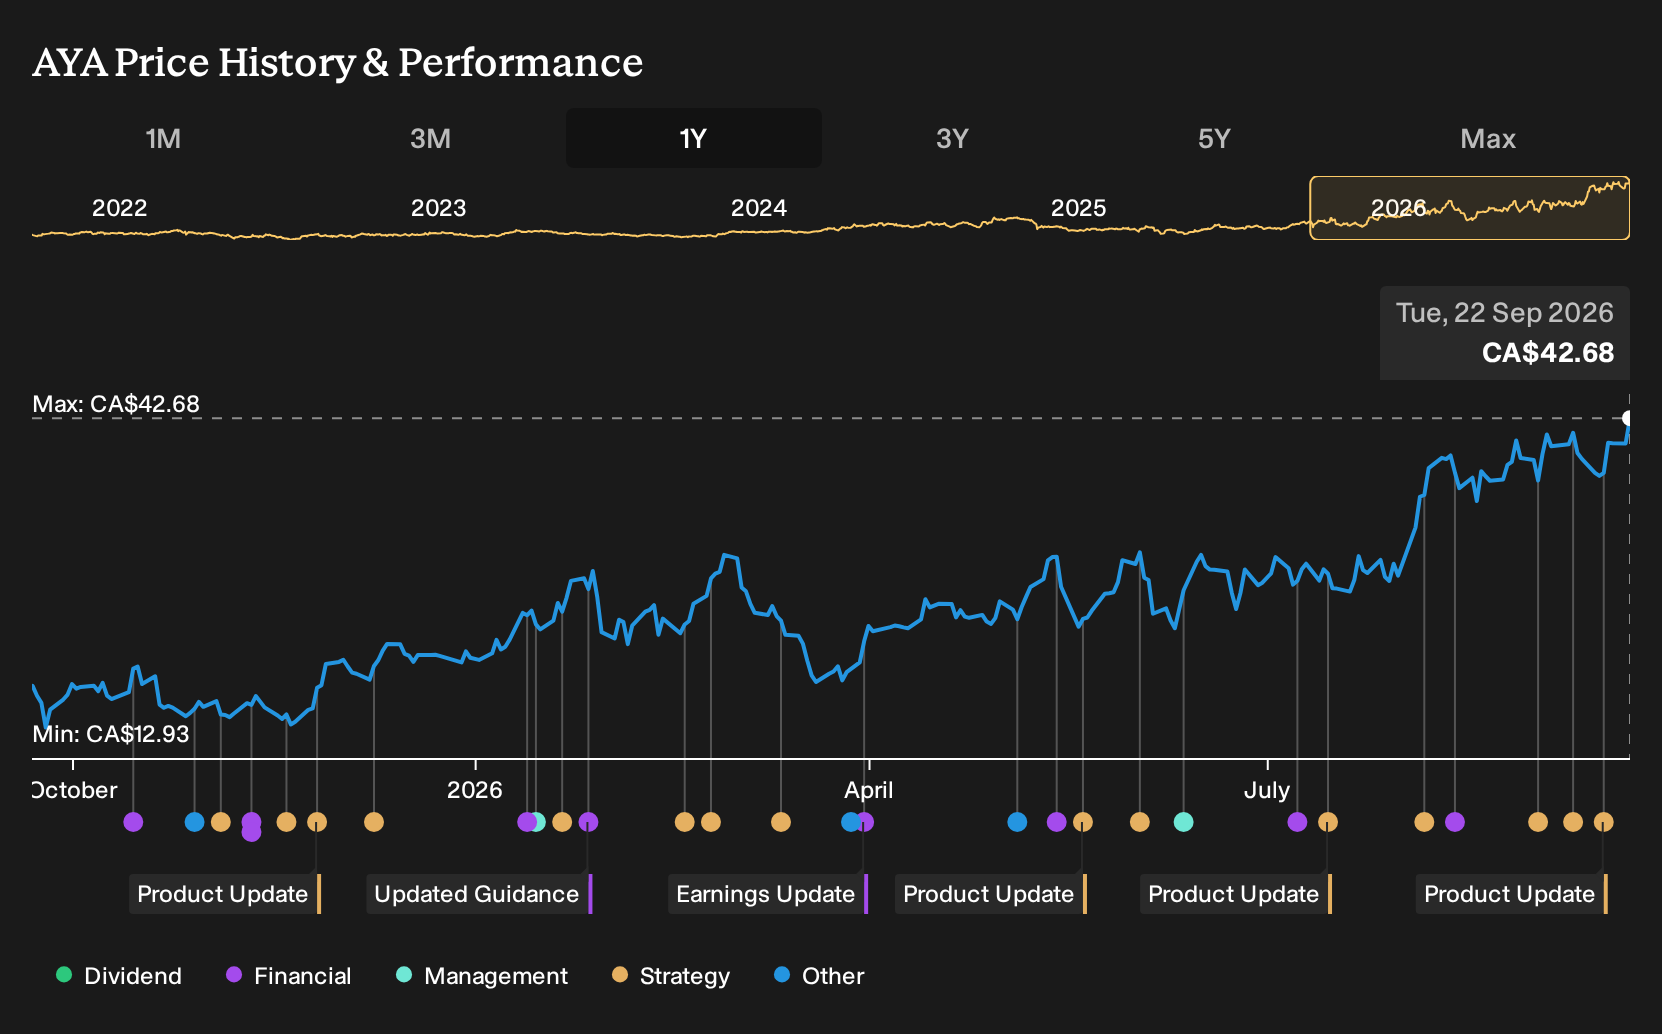
Exploring Other Perspectives
One alternate angle on Aya Gold & Silver focuses on ore dilution risk rather than Boumadine’s upside. The most cautious analysts were modelling 2028 revenue of about $191.4 million and earnings of $57.5 million, yet still arrived at a much lower CA$14.15 target. These views predate the latest Zgounder assays, so you may see those forecasts shift.
Explore 5 other Aya Gold & Silver fair value estimates, including one that suggests there could be as much as 90% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aya Gold & Silver research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aya Gold & Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aya Gold & Silver's overall financial health at a glance.
Looking For More Ideas Beyond Aya Gold & Silver?
If Aya Gold & Silver has sharpened your interest in precious metals and higher risk or higher quality setups, it can help to compare it against a wider watchlist built from consistent rules rather than headlines.
- If you want potential upside with tight budgets, scan a focused set of 17 elite penny stocks with strong financials that already clear basic financial quality checks.
- For investors who care most about buying strength at a discount, review a curated group of 7 high quality undervalued stocks with both healthy balance sheets and solid cash generation.
- If capital protection ranks higher than excitement, build a shortlist from 8 resilient stocks with low risk scores filtered for resilience and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com