


As Asian markets navigate a landscape of mixed economic signals and evolving geopolitical tensions, investors are increasingly focused on identifying opportunities that may be undervalued. In this context, stocks trading at significant discounts can offer potential value, especially when market conditions create disparities between price and intrinsic worth.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shizuki Electric (TSE:6994) | ¥1208.00 | ¥2298.73 | 47.4% |
| Rakus (TSE:3923) | ¥1082.00 | ¥2062.22 | 47.5% |
| PAL GROUP Holdings (TSE:2726) | ¥1486.00 | ¥2869.67 | 48.2% |
| Niterra (TSE:5334) | ¥7218.00 | ¥13807.45 | 47.7% |
| HD Hyundai Energy SolutionsLtd (KOSE:A322000) | ₩116800.00 | ₩222309.08 | 47.5% |
| Double Medical Technology (SZSE:002901) | CN¥40.57 | CN¥79.60 | 49% |
| Dongwon Industries (KOSE:A006040) | ₩35200.00 | ₩70372.87 | 50% |
| Cheil Worldwide (KOSE:A030000) | ₩17630.00 | ₩33818.96 | 47.9% |
| AK Medical Holdings (SEHK:1789) | HK$4.935 | HK$9.55 | 48.3% |
| 3SBio (SEHK:1530) | HK$16.77 | HK$32.14 | 47.8% |
Let's review some notable picks from our screened stocks.
Cheil Worldwide (KOSE:A030000)
Overview: Cheil Worldwide Inc. offers a range of marketing and advertising solutions globally, with a market cap of approximately ₩1.79 trillion.
Operations: Cheil Worldwide Inc.'s revenue is derived from its diverse marketing and advertising solutions offered on a global scale.
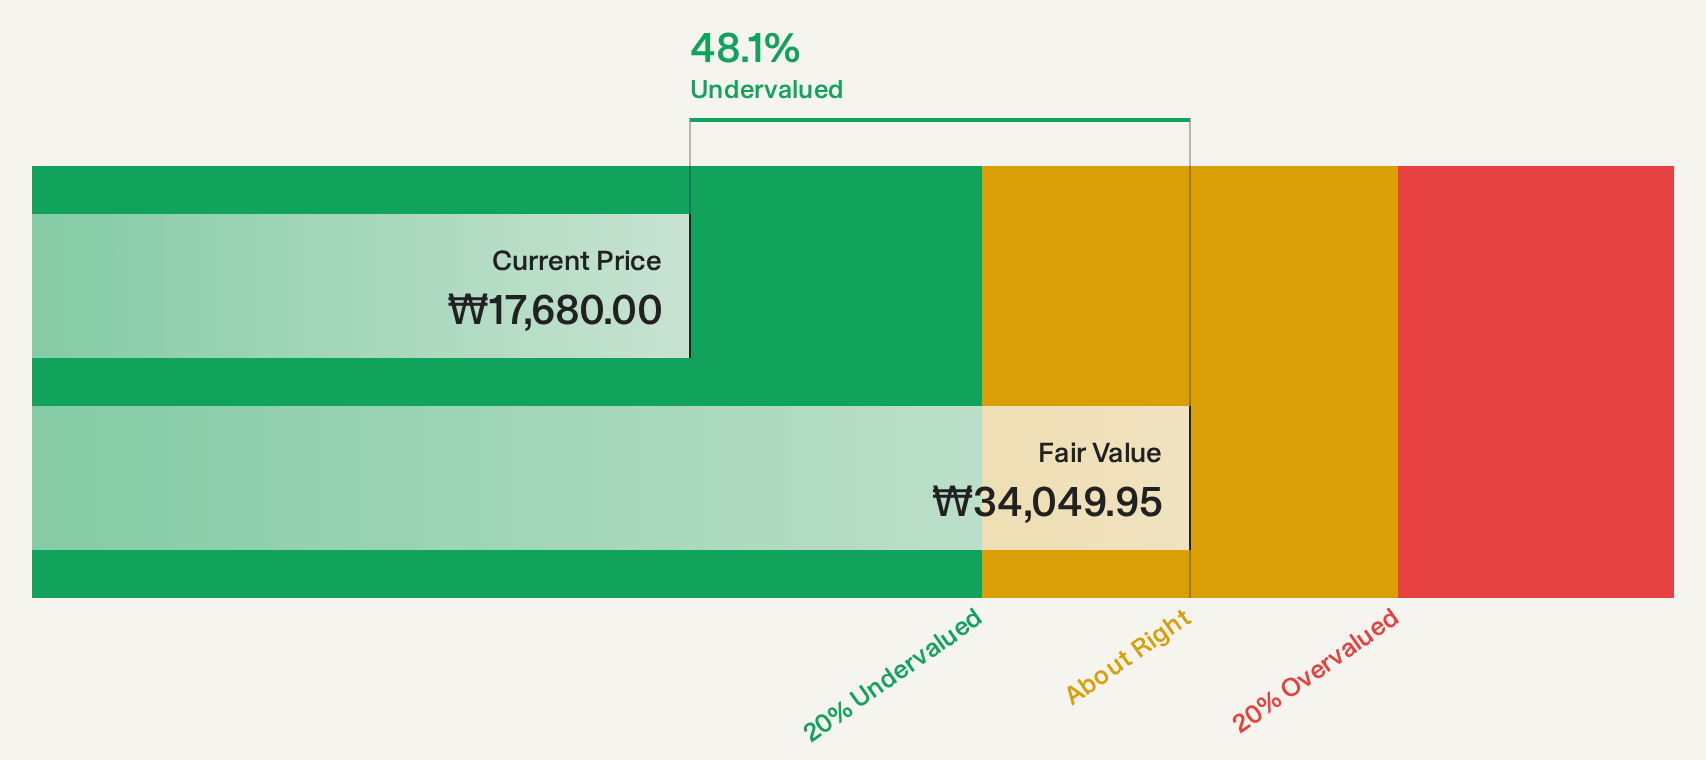
Estimated Discount To Fair Value: 47.9%
Cheil Worldwide is trading at ₩17,630, significantly below its estimated future cash flow value of ₩33,818.96, indicating potential undervaluation based on discounted cash flows. Despite a forecasted revenue growth of 4.3% per year—slower than the Korean market's 14.5%—analysts expect a 35.5% stock price rise. Recent removal from the FTSE All-World Index may impact sentiment but doesn't alter its fundamental valuation strengths relative to peers and industry benchmarks.
- Our comprehensive growth report raises the possibility that Cheil Worldwide is poised for substantial financial growth.
- Click to explore a detailed breakdown of our findings in Cheil Worldwide's balance sheet health report.
HD Hyundai Energy SolutionsLtd (KOSE:A322000)
Overview: HD Hyundai Energy Solutions Co., Ltd. specializes in the production of solar cells and modules, with a market capitalization of ₩1.31 trillion.
Operations: HD Hyundai Energy Solutions Co., Ltd. generates revenue primarily from the sale of solar cells and modules.
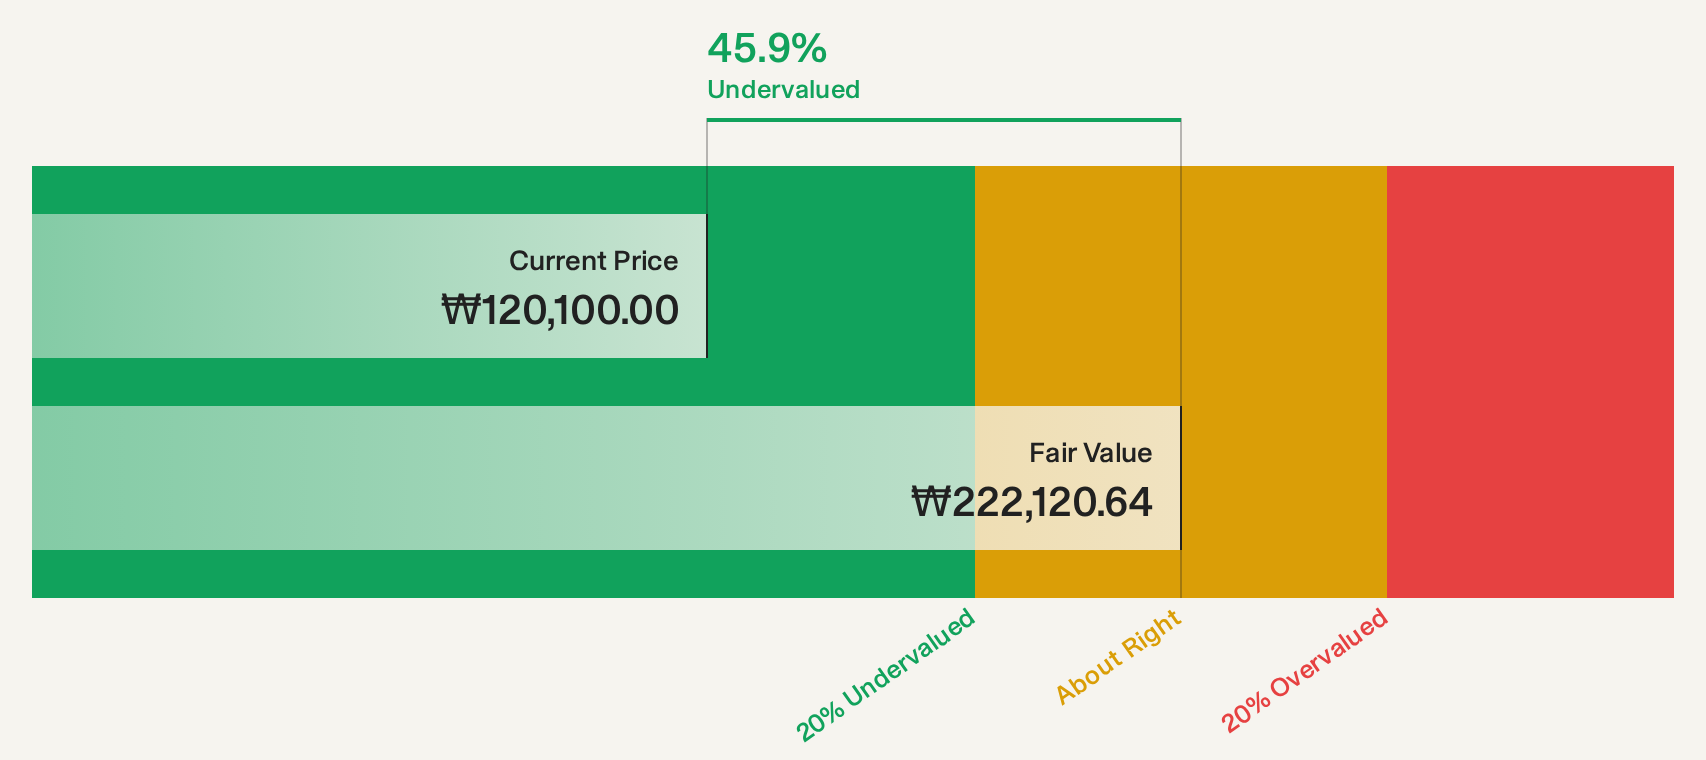
Estimated Discount To Fair Value: 47.5%
HD Hyundai Energy Solutions Ltd. is trading at ₩116,800, significantly below its estimated future cash flow value of ₩222,309.08, highlighting potential undervaluation based on discounted cash flows. The company's revenue is forecast to grow 20.8% annually—outpacing the Korean market's 14.5%—while earnings are expected to increase by 14.68% per year but remain slower than the market average of 28.2%. Despite recent share price volatility, it offers good relative value compared to peers and industry standards.
- Upon reviewing our latest growth report, HD Hyundai Energy SolutionsLtd's projected financial performance appears quite optimistic.
- Click here and access our complete balance sheet health report to understand the dynamics of HD Hyundai Energy SolutionsLtd.
Rakuten Bank (TSE:5838)
Overview: Rakuten Bank, Ltd. offers internet banking products and services to individual, corporate, and sole proprietor customers in Japan with a market cap of approximately ¥1.08 trillion.
Operations: The company generates its revenue primarily from its banking segment, which amounts to ¥207.73 billion.
Estimated Discount To Fair Value: 42.2%
Rakuten Bank is trading at ¥6,175, significantly below its estimated future cash flow value of ¥10,677.19, underscoring potential undervaluation. The company reported Q1 2026 net interest income of ¥43.75 billion and net income of ¥20.97 billion, both up from the previous year. Earnings are forecast to grow 17% annually—faster than Japan's market average—and revenue growth is expected at 11.4% per year, highlighting good relative value compared to peers and industry standards.
- The analysis detailed in our Rakuten Bank growth report hints at robust future financial performance.
- Take a closer look at Rakuten Bank's balance sheet health here in our report.

Next Steps
- Click through to start exploring the rest of the 74 Undervalued Asian Stocks Based On Cash Flows now.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com