


Oil has cooled, diplomatic channels are open, and the scare of a sudden energy shock has eased for now. That shift puts global oil importing, energy hungry businesses in a different light for anyone tracking costs and margins. This article uses that reset in crude prices as the backdrop to spotlight 3 stocks from our screener that are closely tied to this news and may warrant closer attention, whether you lean cautious or optimistic.
The three examples below are just a starting sample from this reset in energy costs, while the full screen surfaced 62 more companies with equally detailed stories that are not covered here. To identify and analyze the highest conviction ideas in this theme, go straight to the Global Oil-Importing, Energy-Intensive Industries screener.
Exchange Income (TSX:EIF)
Overview: Exchange Income runs fuel intensive aerospace, aviation and manufacturing businesses, where flight activity and energy costs directly shape profitability.
Operations: Exchange Income generates about CA$2.6b from Aerospace & Aviation and CA$1.1b from Manufacturing, reflecting a heavily aviation weighted mix.
Market Cap: CA$6.6b
Exchange Income gives this energy intensive screener a pure aviation angle, since jet fuel, flight hours and remote route economics all directly channel into how falling oil prices feed through to margins.
"The recent acquisition of Canadian North, combined with a long-term exclusive contract with the Government of Nunavut, uniquely positions the company as the primary provider of essential air services to remote Arctic regions. This leverages multi-decade demand for connectivity and government infrastructure investment in the North, creating a stable, recurring revenue base and supporting future revenue and EBITDA growth."
What happens to those cash flows if a single key assumption about cost pressures in this high fuel burn network quietly shifts.
If that cost equation matters to you, read the full narrative for Exchange Income to see how fuel trends, contract structure and acquisitions could be quietly reshaping Exchange Income’s trajectory.

Samsung Heavy Industries (KOSE:A010140)
Overview: Samsung Heavy Industries builds large, fuel hungry vessels and offshore energy platforms worldwide, serving LNG, container, tanker and specialty shipping.
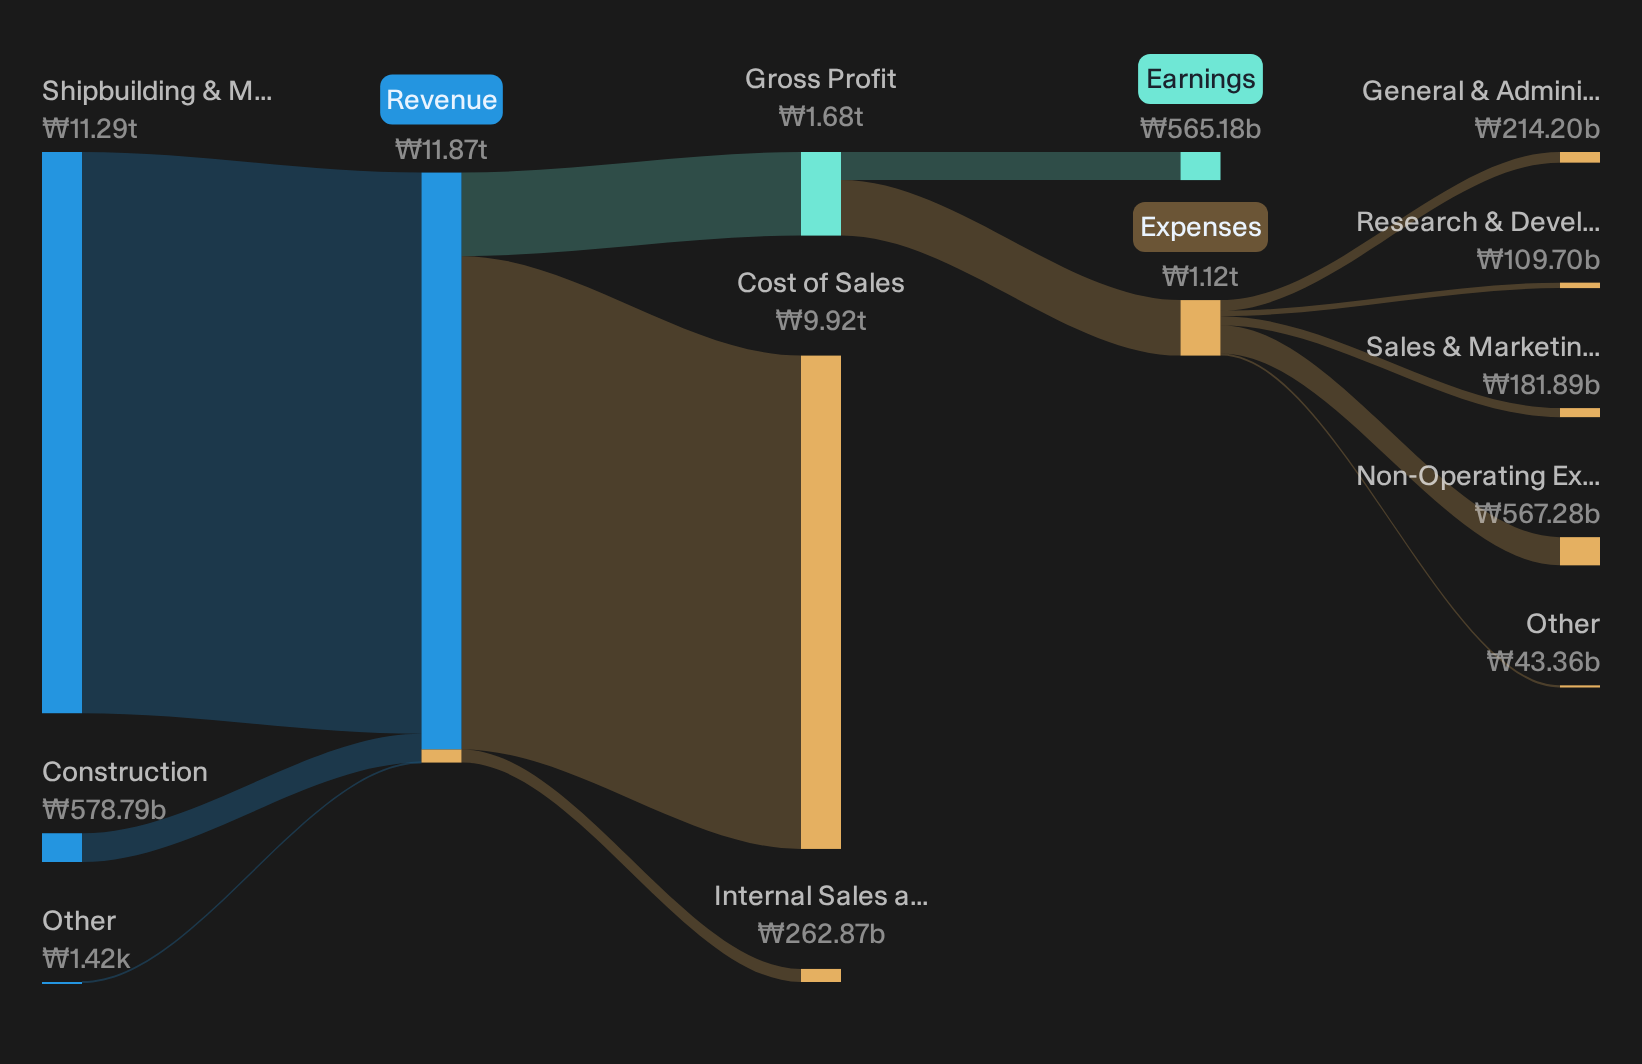
Operations: Samsung Heavy Industries generates about ₩11.3t from Shipbuilding & Marine Engineering and ₩0.6t from Construction, with smaller internal adjustments.
Market Cap: ₩17.6t
Samsung Heavy Industries sits squarely in the energy intensive shipping value chain, where lower oil prices ease marine fuel and input costs for both shipyards and future vessel operators. Recent profitability momentum, the quality of its earnings and its exposure to LNG and offshore projects make it an interesting way to play this screen, depending on how one unseen pressure on future project economics plays out.
That hinge factor is exactly what the analysis report for Samsung Heavy Industries unpacks, revealing where Samsung Heavy Industries could see project economics accelerate fastest.
CSSC Offshore & Marine Engineering (Group) (SEHK:317)
Overview: CSSC Offshore & Marine Engineering (Group) builds military vessels, commercial ships, offshore platforms and energy equipment for clients across global marine and defense markets.
Market Cap: HK$38.1b
CSSC Offshore & Marine Engineering (Group) fits into this energy intensive screener because shipbuilding, offshore platforms and defense projects all rely on fuel heavy operations, where softer crude prices can ease input and logistics costs. Forecast earnings growth of 49.17%, expanding revenue and improving net margins align with that theme with momentum, although future returns depend on how one key cost of doing business behaves over time.
That cost swing is exactly where the analyst forecasts for CSSC Offshore & Marine Engineering (Group) can sharpen your view of whether CSSC Offshore & Marine Engineering (Group) is gearing up or stalling.

Seeking Alternatives Before The Crowd?
Fresh ideas move first, and slow research gets caught watching the breakout from the sidelines while prices are already flying. Scan these under the radar themes while it matters and consider acting before conditions change.
- Spot potential cash rich compounds early by scanning the list of solid balance sheet and fundamentals (7 results), while others only react once the momentum is already obvious.
- Follow structural demand in electrification by tracking the 17 top copper producer stocks before changes in supply and sentiment reduce the most accessible entry points.
- Prepare for potential inflation or currency concerns by reviewing the 36 elite gold producer stocks while these producers remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com