


Eos Energy Enterprises (EOSE) drew an initial US$87 million advance under the second tranche of its U.S. Department of Energy loan, tied directly to the Thorn Hill battery manufacturing build out.
For context, Eos Energy Enterprises’ share price has slipped sharply over the year, with the year to date share price return down 68.7% and the 1 year total shareholder return down 60.0%, even though the 3 year total shareholder return is up 73.5% from a much lower base.
Scan beyond Eos Energy Enterprises and size up other grid and storage plays with the hand picked 40 power grid technology and infrastructure stocks that could benefit from increased energy infrastructure spending.
Eos Energy Enterprises trades far below both analyst targets and one intrinsic estimate range, creating a wide gap between recent price and implied worth. Where does a fair value anchor reasonably land in that spread?
Most Popular Narrative: 26.9% Overvalued
Eos Energy Enterprises last closed at $4.06, while the leading narrative on the stock pegs fair value at $3.20. This implies a meaningful premium to that anchor estimate and sharpens the question of what is already priced in.
EOSE is not an investment for value investors, dividend hunters, or conservative savers. Anyone who gets in here should have a clear profile. This includes a high willingness to take risks, including the acceptance of a total loss. The investment horizon should be at least three to five years. Furthermore, it requires an understanding that your own stake will be systematically diluted. Political awareness of the IRA, OBBBA, and DOE programs is mandatory. And finally, it takes the willingness to enter into an asymmetrical bet where the majority of scenarios turn out negative, but the positive scenario promises a multiple of the stake.
See why 9 investors see Eos Energy Enterprises as 27% overvalued.
Result: Fair Value of $3.20 (OVERVALUED)
Still, the Eos Energy Enterprises story can crack quickly if customer concentration bites or complex financing terms tighten instead of easing investor concerns.
Find out about the key risks to this Eos Energy Enterprises narrative.
Another View On Eos Energy Enterprises: Cash Flows Tell A Different Story
The earlier narrative-led fair value of $3.20 for Eos Energy Enterprises frames the stock as overvalued. A contrasting SWS DCF model points the other way, with an estimated future cash flow value of $22.59 per share. This lines up with the idea that EOSE is trading well below that cash flow anchor.
This split between a story driven fair value of $3.20 and a cash flow based mark of $22.59 leaves a wide range. The key question for any investor is simple: Which set of assumptions feels more realistic for how Eos Energy Enterprises might actually convert its project pipeline and forecasts into cash over time, and which feels too optimistic for your comfort level?
Look into how the SWS DCF model arrives at its fair value.
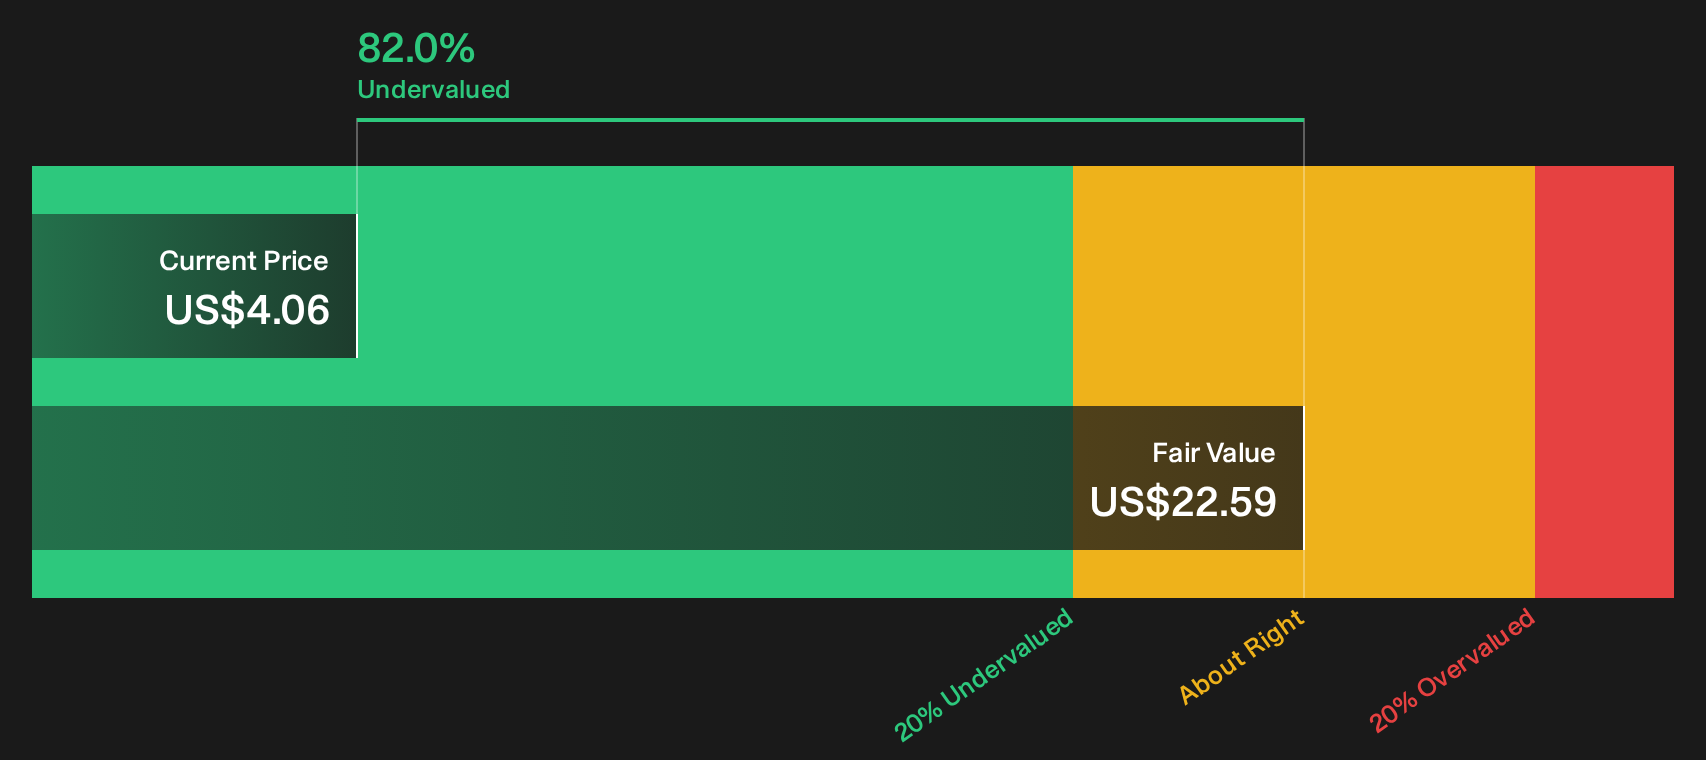
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eos Energy Enterprises for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on Eos Energy Enterprises leave you conflicted, use that as a prompt to move quickly, check the numbers, and build your own stance from the raw data and risk flags. Then weigh both the downside worries and upside potential through the 2 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Eos Energy Enterprises?
If Eos Energy Enterprises has you thinking harder about risk, reward, and timing, do not stop here. Cast the net wider with focused stock lists built for different goals.
- Target potential mispricing by scanning a curated spread of companies that screen as both financially robust and priced for value through the 29 high quality undervalued stocks.
- Strengthen your income focus by checking stocks that combine high yields with resilience using the 7 dividend fortresses.
- Dial down risk by reviewing shares that pass strict balance sheet and fundamentals filters in the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com