


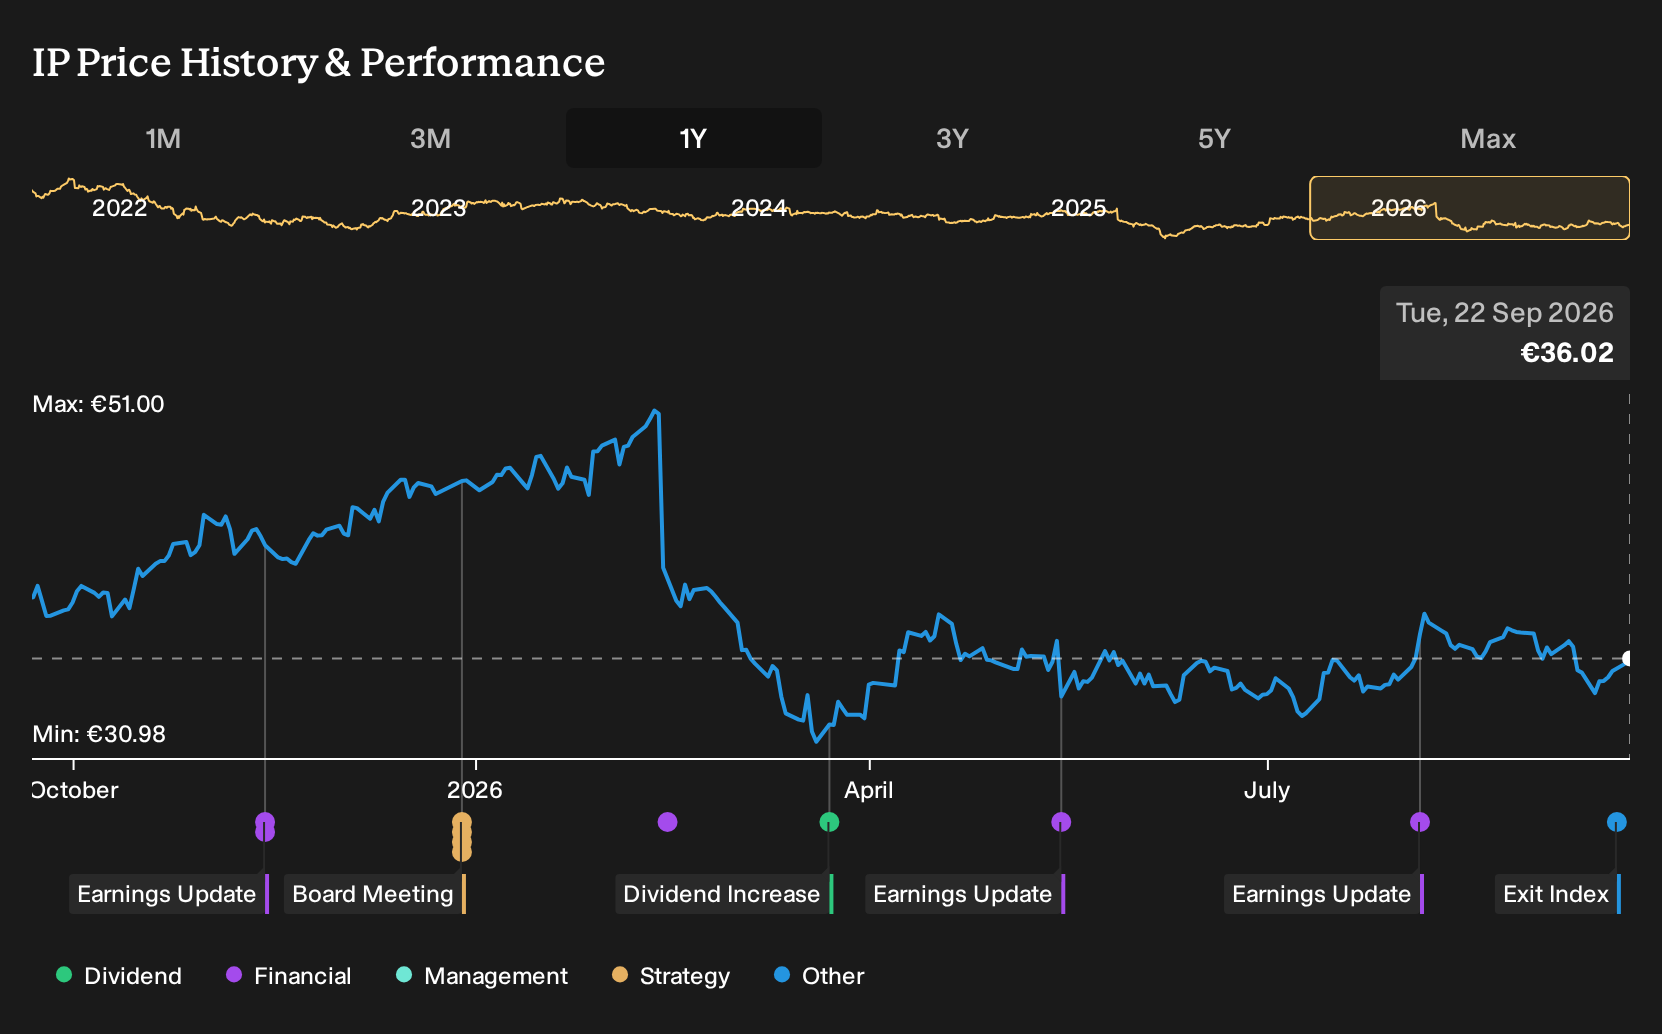
- Interpump Group was recently removed from the FTSE All-World Index, a broad global equity benchmark that many index-tracking funds follow.
- The exclusion could alter how large passive and institutional investors hold Interpump Group. This matters for liquidity, funding flexibility, and long-term capital allocation choices.
- We will now explore how Interpump Group's investment narrative could be affected by its recent exclusion from the FTSE All-World Index.
Pressure test your thesis on Interpump Group by comparing it with our hand-picked 171 high quality undervalued stocks that institutional flows may be slower to recognise after index reshuffles.
Interpump Group Investment Narrative Recap
To own Interpump Group, you need to believe its hydraulics and water-jetting businesses can steady and then gradually improve, even with mixed regional demand. The short term focus is on Hydraulics stabilizing after a long patch of organic revenue weakness and on Water-Jetting normalizing after a strong China contract. Being dropped from the FTSE All-World Index mostly affects how some passive funds trade the stock rather than how pumps, components, and systems sell day to day.
The biggest operational swing factor right now is whether Hydraulics demand and customer restocking hold up without fresh tariff or geopolitical shocks. Execution on acquisitions such as White Drive and Padoan also matters because any integration issues could weigh on margins that already sit in the low double digits. Index exclusion does not directly affect these operational tasks. It may simply influence how quickly large, benchmarked investors react to any improvement or setback.
There have been no major company announcements directly tied to this FTSE All-World Index removal, so your reference points are the existing operating trends. Hydraulics has seen several quarters of organic revenue pressure with only early signs of stabilization. At the same time, Water-Jetting benefited from a strong Chinese contract that management already flagged as a one off lift, so a cooler growth phase there would not be surprising.
Those earlier comments about fragile Hydraulics normalization, limited demand visibility, and ongoing M&A integration work remain highly relevant when thinking about the index change. The catalyst many investors are watching is a cleaner recovery in core Hydraulics and smoother earnings contribution from acquired units. The key risk is that external shocks or messy integrations interrupt that path just as large index-tracking holders are adjusting positions after the removal.
Interpump Group's narrative projects €2.3b revenue and €285.3 million earnings by 2029. This assumes 4.0% yearly revenue growth and an earnings increase of about €76.8 million from €208.5 million today.
Uncover why Interpump Group's fair value indicates a 26% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between €30.21 and €45.56 per share, which shows how far apart retail views on Interpump Group can be. These opinions ignore the FTSE All-World exit and the possibility that fragile Hydraulics demand or acquisition integration issues reshape how future performance is judged.
Explore 2 other Interpump Group fair value estimates, including one that suggests as much as 16% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Interpump Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Interpump Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interpump Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Interpump Group?
If you want to balance your view on Interpump Group with ideas in other corners of the market, the Simply Wall St Screener can help you surface stocks that fit very different risk and income profiles.
- For investors who care most about robust finances and resilient balance sheets, start with our list of solid balance sheet and fundamentals (198 results) to see which businesses may better withstand tough conditions.
- If you prefer to keep risk in check and still stay exposed to equities, consider screening through 229 resilient stocks with low risk scores that focus on stability and downside protection.
- Those looking for underfollowed opportunities can scan through our 619 high quality undiscovered gems that combine strong fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com