


BrightSpring Health Services (BTSG) drew fresh attention after Carillon Eagle Small Cap Growth Fund highlighted the company’s revenue and EBITDA outperformance versus IPO expectations in its second quarter 2026 investor letter.
BrightSpring Health Services shares have cooled off in recent weeks, with the 30 day share price return down 3.9% and the 90 day move down 16.4%. This comes even though the year to date share price return is 47.3% and the 1 year total shareholder return is 102.1%, pointing to strong longer term momentum despite a near term pause around the latest US$56.55 close.
Scan beyond BrightSpring Health Services and explore other healthcare operators showing strong business traction with our curated list of 37 healthcare AI stocks
BrightSpring Health Services now trades at a hefty discount to both intrinsic value estimates and analyst targets after that pullback. Is this caution a case of smart risk pricing, or is it an opening that valuation math struggles to justify?
Most Popular Narrative: 20% Undervalued
BrightSpring Health Services carries a narrative fair value of $70.59 against the latest $56.55 share price. This frames the recent pullback as a gap between current sentiment and the story followers of the company are using to price it.
The key inflection is this:
Earnings are no longer being suppressed by restructuring; they are now being driven by scale. The investment case is not “cheap stock” or “high-quality compounder.”
See why 8 investors see BrightSpring Health Services as 20% undervalued.
Result: Fair Value of $70.59 (UNDERVALUED)
Still, the BrightSpring Health Services story can strain if pharmacy churn rises, or if reimbursement pressure caps the margin and the deleveraging progress investors are banking on.
Find out about the key risks to this BrightSpring Health Services narrative.
Another View: BrightSpring Health Services Looks Expensive On Earnings
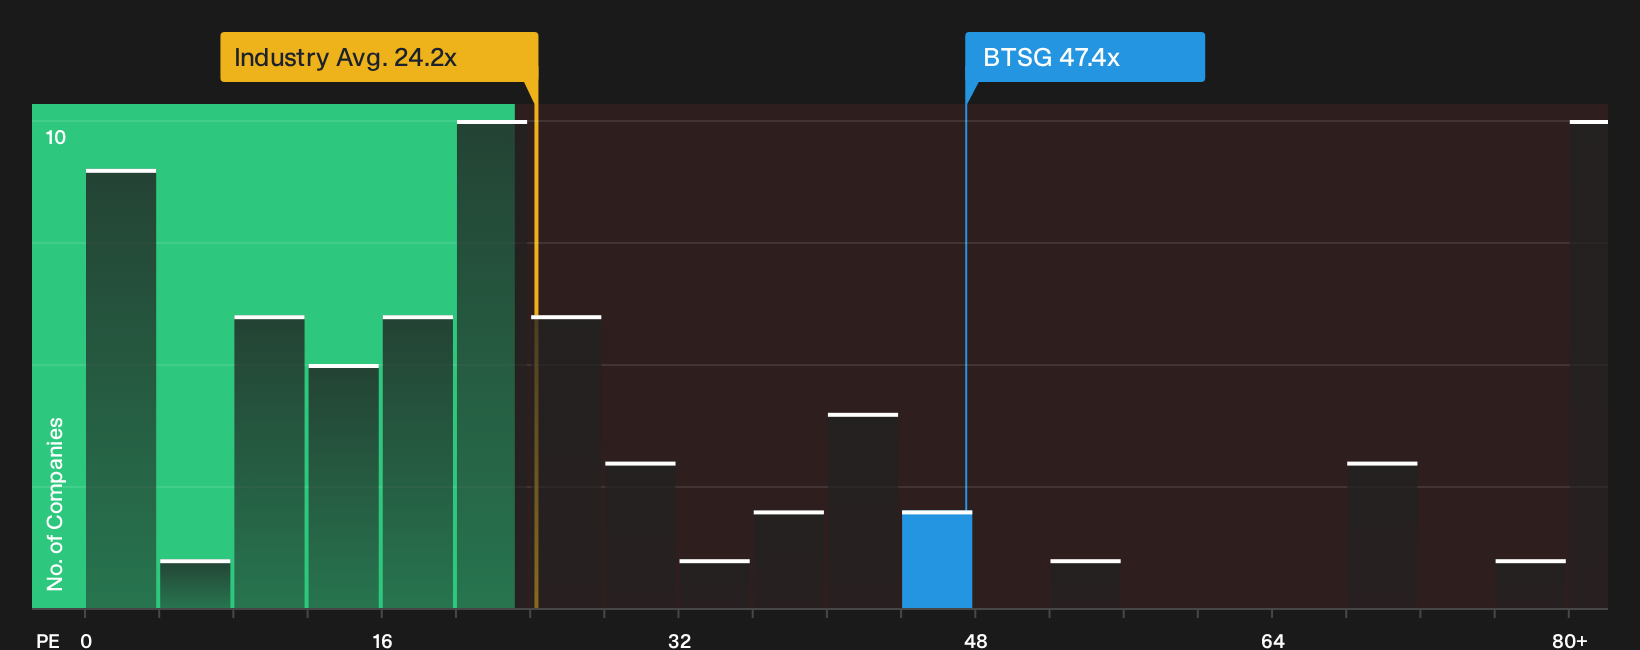
Look at BrightSpring Health Services through a simple P/E lens and the picture changes. The stock trades on a 47.4x P/E, compared with 24x for the wider US Healthcare group and a fair ratio of 36.3x, even though peers average 50.8x. That gap points to meaningful valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of enthusiasm and concern around BrightSpring Health Services is exactly what makes the debate interesting, and it rewards readers who move fast and review the full balance of data before opinions harden. To see both sides of the story in one place, start with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BrightSpring Health Services?
If BrightSpring Health Services has sharpened your focus on quality opportunities, do not stop here. Broaden your watchlist now and keep your options open.
- Target resilient balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) that meet strict financial strength checks.
- Hunt for potential mispricings by reviewing the 29 high quality undervalued stocks that pair business quality with compressed valuations.
- Spot companies quietly executing in the background by filtering through the 16 high quality undiscovered gems that many investors may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com