


When the Federal Reserve pushes rates higher and inflation stays stubborn, dividend stocks move from background income idea to front-row focus. Cash yields on offer today compete directly with bonds, and quality payouts can feel like a rare anchor in choppy markets. This article walks through three U.S. dividend stocks from our high-quality screener that appear closely tied to the latest Fed shift and wider macro shock.
The three dividend stocks covered below are only a sample of what fits this income and quality profile, and the full screen surfaced 26 more large U.S. companies with similarly robust dividend stories that are not included here. To widen your watchlist and zero in on the combinations of payout strength, balance sheet quality, and risk level that fit your approach, head straight to the High-Quality Dividend-Paying U.S. Equities screener.
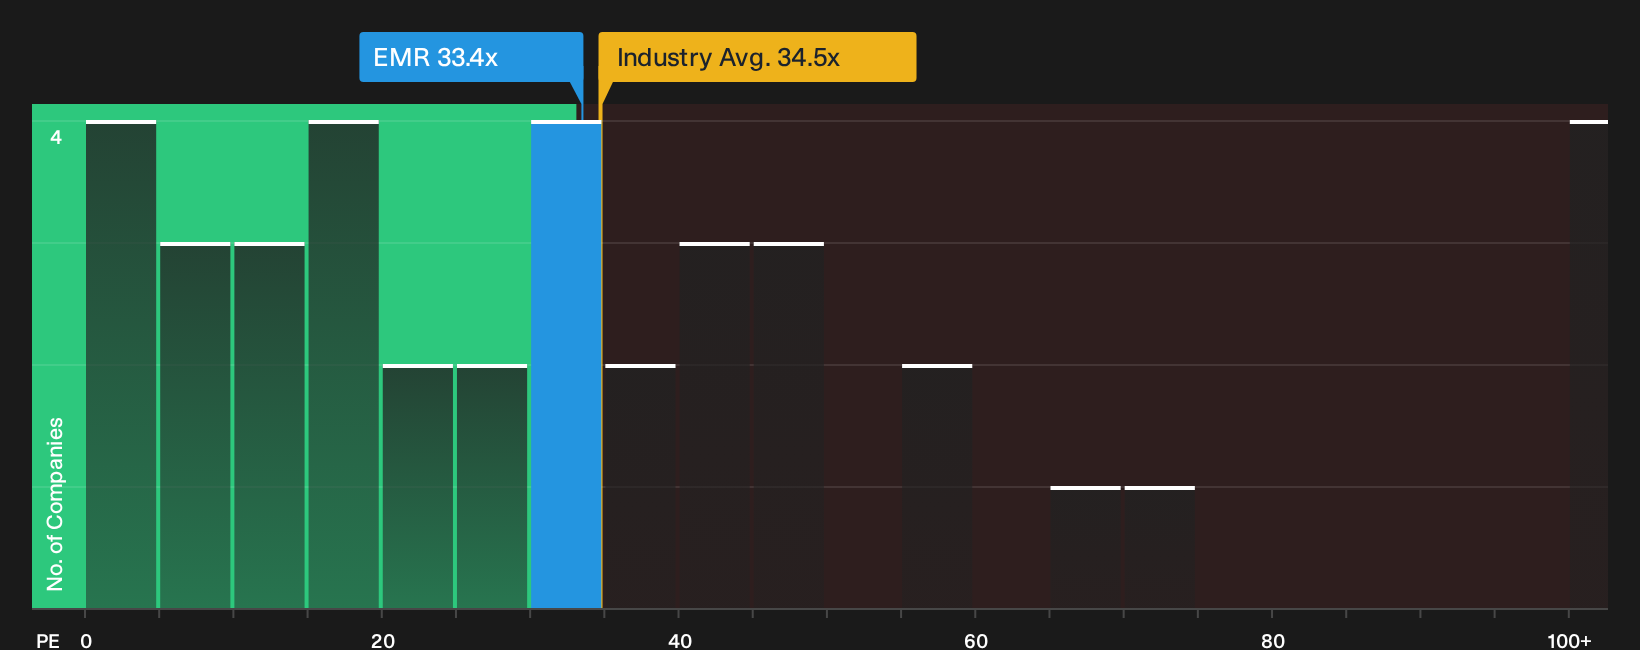
Emerson Electric (EMR)
Overview: Emerson Electric is a long-established U.S. industrial and software group that supplies automation, measurement, and control solutions to process plants, factories, and infrastructure customers worldwide. This aligns cleanly with the high-quality dividend payer theme.
Operations: Emerson Electric generates about US$11.3b from Segment Adjustment activities, US$4.3b from Intelligent Devices, US$1.7b from Software and System Test & Measurement, and US$1.4b from Safety & Productivity, with Europe contributing roughly US$3.6b.
Market Cap: US$84.6b
For income investors scanning higher rates and stickier inflation, Emerson Electric brings a mix of mature industrial exposure and software-driven cash flows that fits the high-quality dividend screen. Its automation focus provides a potentially interesting angle on the Fed driven shift toward dependable payers.
"The accelerating adoption of digital automation and artificial intelligence solutions in global industrial markets is fueling strong demand for Emerson's advanced software platforms and AI-enabled products, such as Ovation 4.0 and Nigel AI adviser, which is resulting in robust order growth and positions the company for sustained revenue expansion."
What really matters now is how one unresolved pressure on Emerson Electric’s balance sheet and funding costs shapes future dividend headroom.
That pressure point is exactly what the full narrative for Emerson Electric unpacks, showing how Emerson Electric’s automation push and funding profile could reshape its dividend resilience under higher rates.
Ferguson Enterprises (FERG)
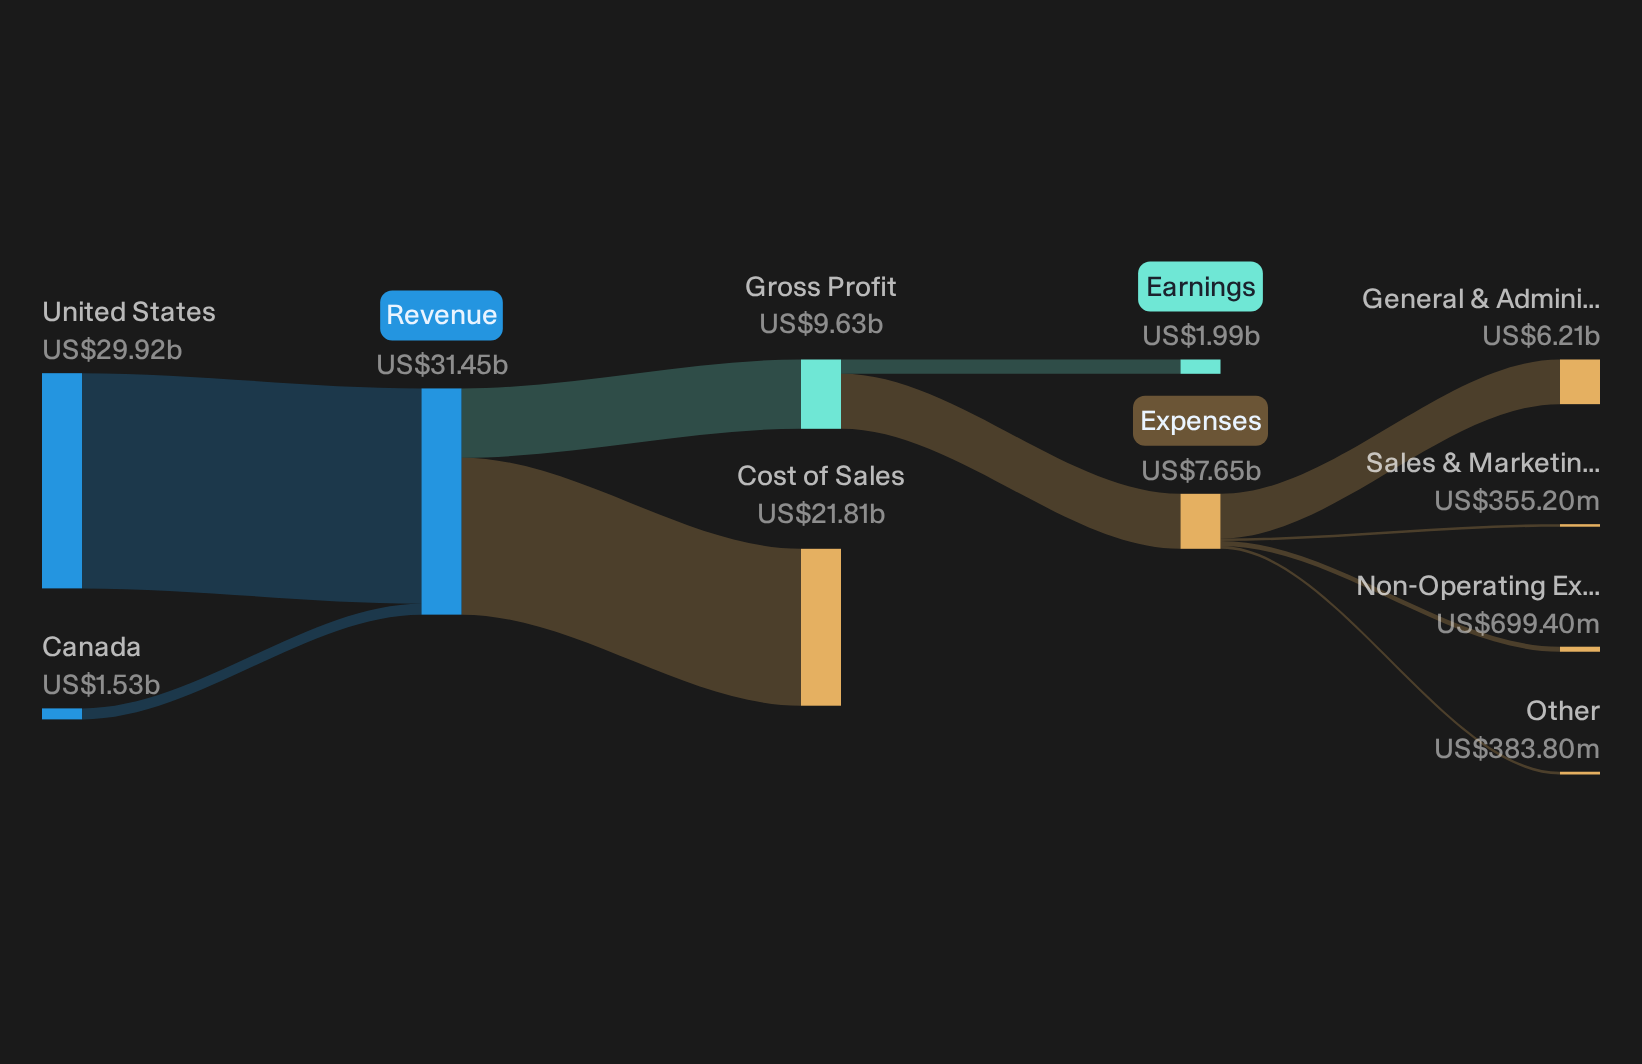
Overview: Ferguson Enterprises distributes plumbing, HVAC, water and wastewater products and related services to professional contractors across U.S. and Canadian construction and repair markets.
Operations: Ferguson generates about US$31.4b from distributing plumbing and heating products, with roughly US$29.9b in the United States and US$1.5b in Canada.
Market Cap: US$41.8b
For a high-quality dividend screen, Ferguson Enterprises matters because it sits at the junction of essential water and air infrastructure and steady, service-led cash generation that can support ongoing payouts even when rate policy tightens.
"Rising demand for large capital projects such as data centers, pharma and manufacturing facilities is feeding a growing project pipeline."
What investors really need to watch next is how one unseen constraint on Ferguson Enterprises’ balance sheet and funding costs shapes future margin strength.
That hidden pressure is exactly what the full narrative for Ferguson Enterprises lays out, tracing how Ferguson Enterprises could turn project demand into accelerating cash generation even as costs and financing reset.
Carrier Global (CARR)
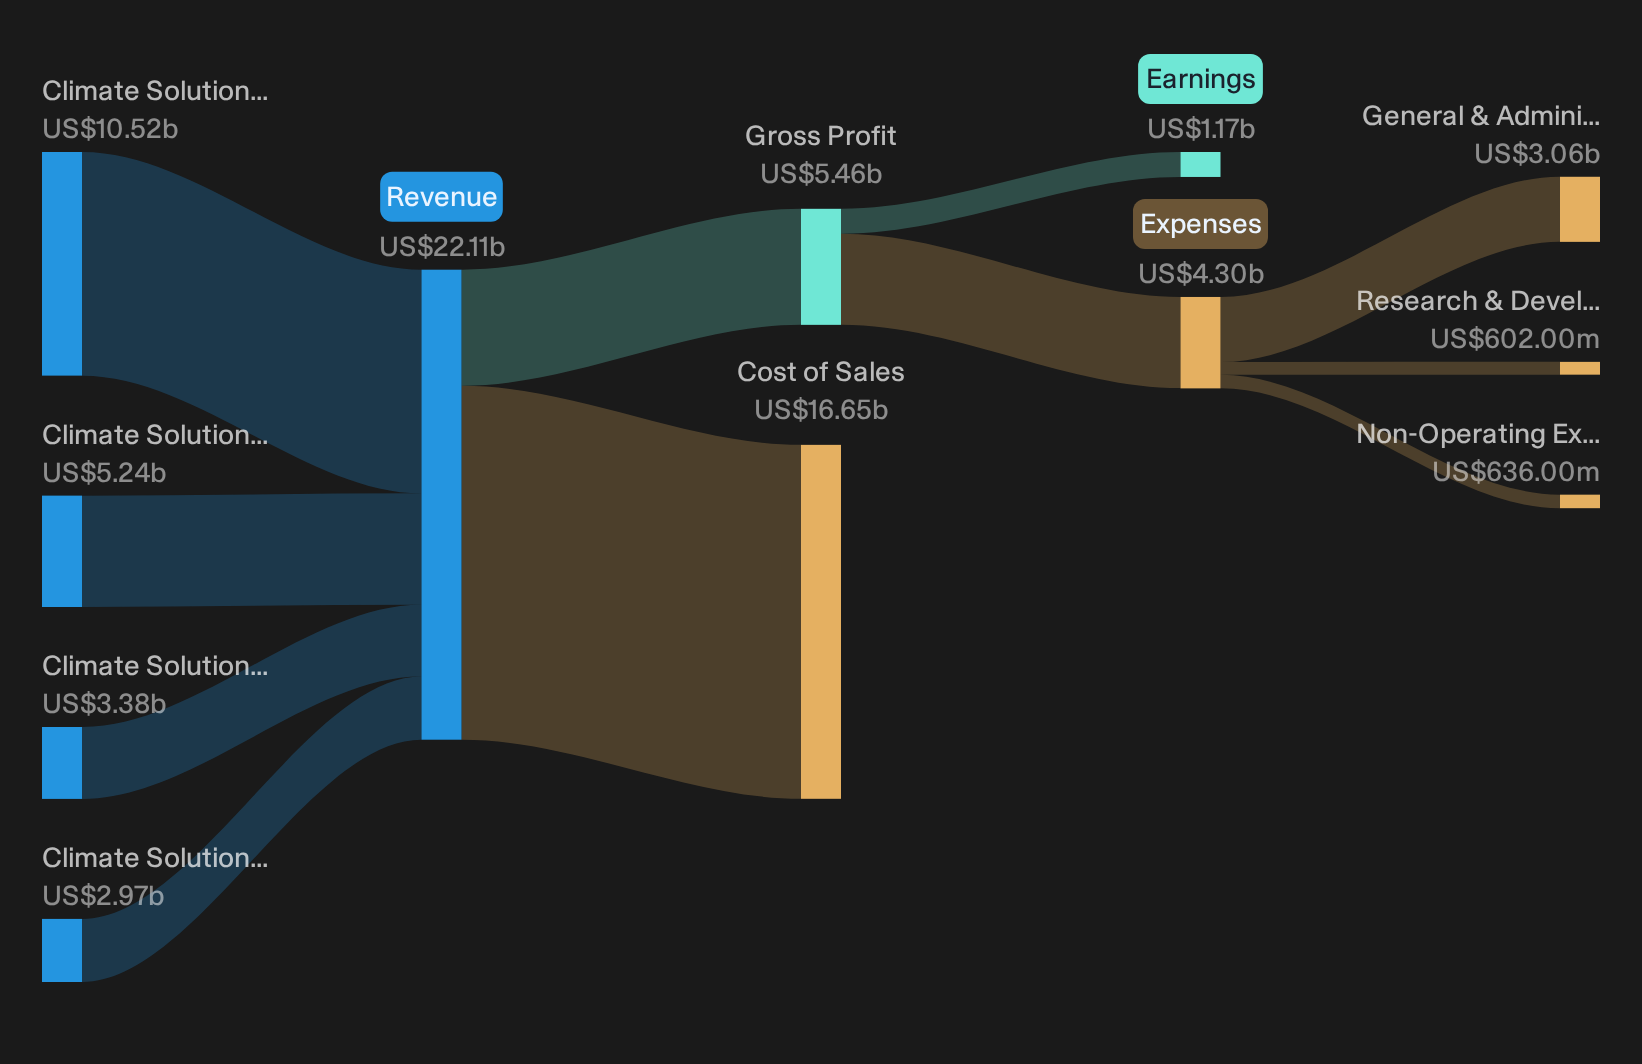
Overview: Carrier Global provides heating, cooling, refrigeration and energy management equipment and services for buildings and transport customers worldwide, supporting income focused investors through a mature, cash generative industrial profile.
Operations: Carrier Global generates about US$10.5b from Climate Solutions Americas, US$5.2b from Climate Solutions Europe, US$3.4b from Climate Solutions Asia Pacific, Middle East & Africa, and US$3.0b from Climate Solutions Transportation.
Market Cap: US$45.0b
Carrier Global matters for a high quality dividend screen because its recurring service work and long lived climate systems can translate into steadier cash flows as rates reset higher.
"Carrier Global is building a larger presence in AI and data center cooling, with about $2 billion of 2026 data center revenue already in backlog, an over $8 billion company backlog that is heavily tied to commercial and data center projects, and a dedicated U.S. manufacturing site planned to roughly double Americas data center capacity. This can support future revenue and earnings."
What really decides how well Carrier Global converts that backlog into dividend friendly cash flow is how one unresolved margin pressure plays out.
That margin question is exactly what the full narrative for Carrier Global unpacks, showing where Carrier Global’s backlog, capital needs, and pricing power could be quietly accelerating or capping future payout capacity.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move from quiet accumulation to full breakout before most investors even look up. Do not get caught chasing momentum after it runs. Act now.
- Target resilient income by scanning a curated mix of high-yield payers in the 7 dividend fortresses that balance elevated cash returns with robust underlying fundamentals.
- Hunt for under the radar growth stories using the curated 16 high quality undiscovered gems geared toward quality businesses that many investors have not fully priced in yet.
- Position for the next infrastructure and electrification wave by reviewing the focused 40 power grid technology and infrastructure stocks packed with potential beneficiaries of long term grid and energy upgrades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com