


IRADIMED (IRMD) drew fresh attention after its shares closed at US$86.51, with recent returns mixed between the past week, month, and past 3 months. Investors are weighing that share performance against longer-term gains.
In the short term, IRADIMED’s 1-day and 7-day share price returns of 4.91% and 4.98% suggest fresh buying interest after a weaker few months. Over longer periods, the 1-year, 3-year, and 5-year total shareholder returns of 22.54%, 109.04%, and 180.09% highlight a strong longer run for investors.
Scan beyond IRADIMED and size up other hospital and medtech players with solid balance sheets using our curated list of solid balance sheet and fundamentals (23 results)
The latest bounce in IRADIMED after a weaker 3 months leaves a fresh fork in the road. Is most of the upside already in the rear-view mirror, or does the recent move still leave meaningful value on the table as you look at valuation next?
Most Popular Narrative: 27% Undervalued
On the most followed narrative, IRADIMED screens as undervalued, with a fair value of $118 against the recent close at $86.51, and that view leans heavily on product-cycle and margin assumptions.
The introduction and FDA approval of the new 3870 MRI-compatible IV pump, with significantly enhanced usability and technology over the legacy product, is expected to catalyze a major replacement cycle among hospitals and imaging centers, unlocking large-scale, recurring device and consumable revenues. This supports a step-change in revenue growth as existing customers upgrade and potential new customers previously deterred by usability issues are attracted.
See why 7 investors see IRADIMED as 27% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, the bullish IRADIMED story leans heavily on a narrow MRI-focused product set and a smooth 3870 pump rollout, where any stumble could quickly challenge that 27% undervalued thesis.
Find out about the key risks to this IRADIMED narrative.
Another View On IRADIMED’s Valuation
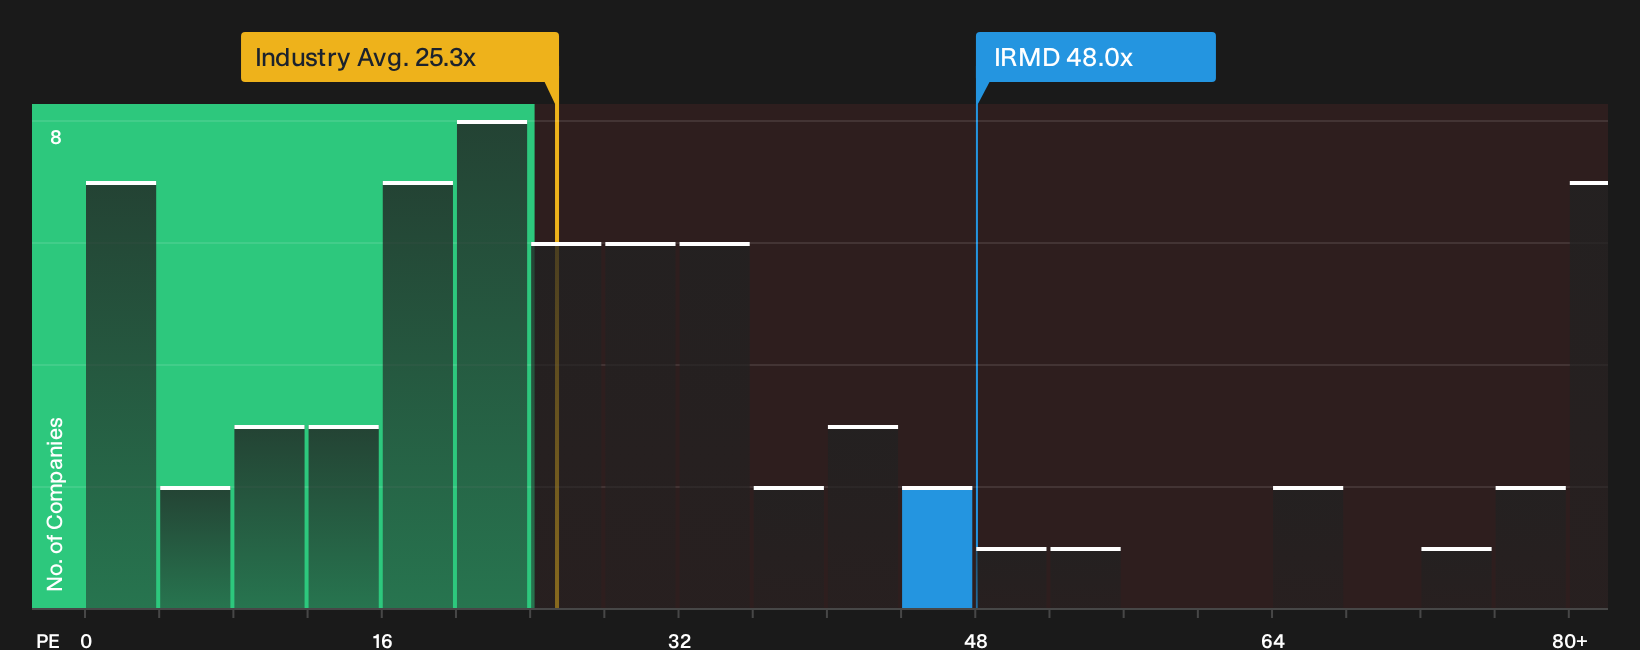
The story changes once you swap the analyst fair value for IRADIMED with a simple earnings multiple check. At a P/E of 48x, the stock trades well above the US Medical Equipment sector on 25.1x and a fair ratio of 21.9x, which points to a rich valuation and less room for error. Is that premium something you are comfortable paying for this growth profile?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Confident that the crowd has IRADIMED priced right, or think the story is being misread? Move quickly, review the optimism in the numbers, and pressure test the 2 key rewards.
Ready for more investment ideas beyond IRADIMED?
Do not stop your research with IRADIMED. Broaden your watchlist with a few focused idea lists that can surface opportunities you might otherwise miss.
- Target stability first by checking companies that score well on resilience using the 30 resilient stocks with low risk scores.
- Hunt for value by reviewing quality businesses that screen as attractively priced through the 29 high quality undervalued stocks.
- Spot potential future leaders early by scanning financially sound smaller stocks on the 9 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com