


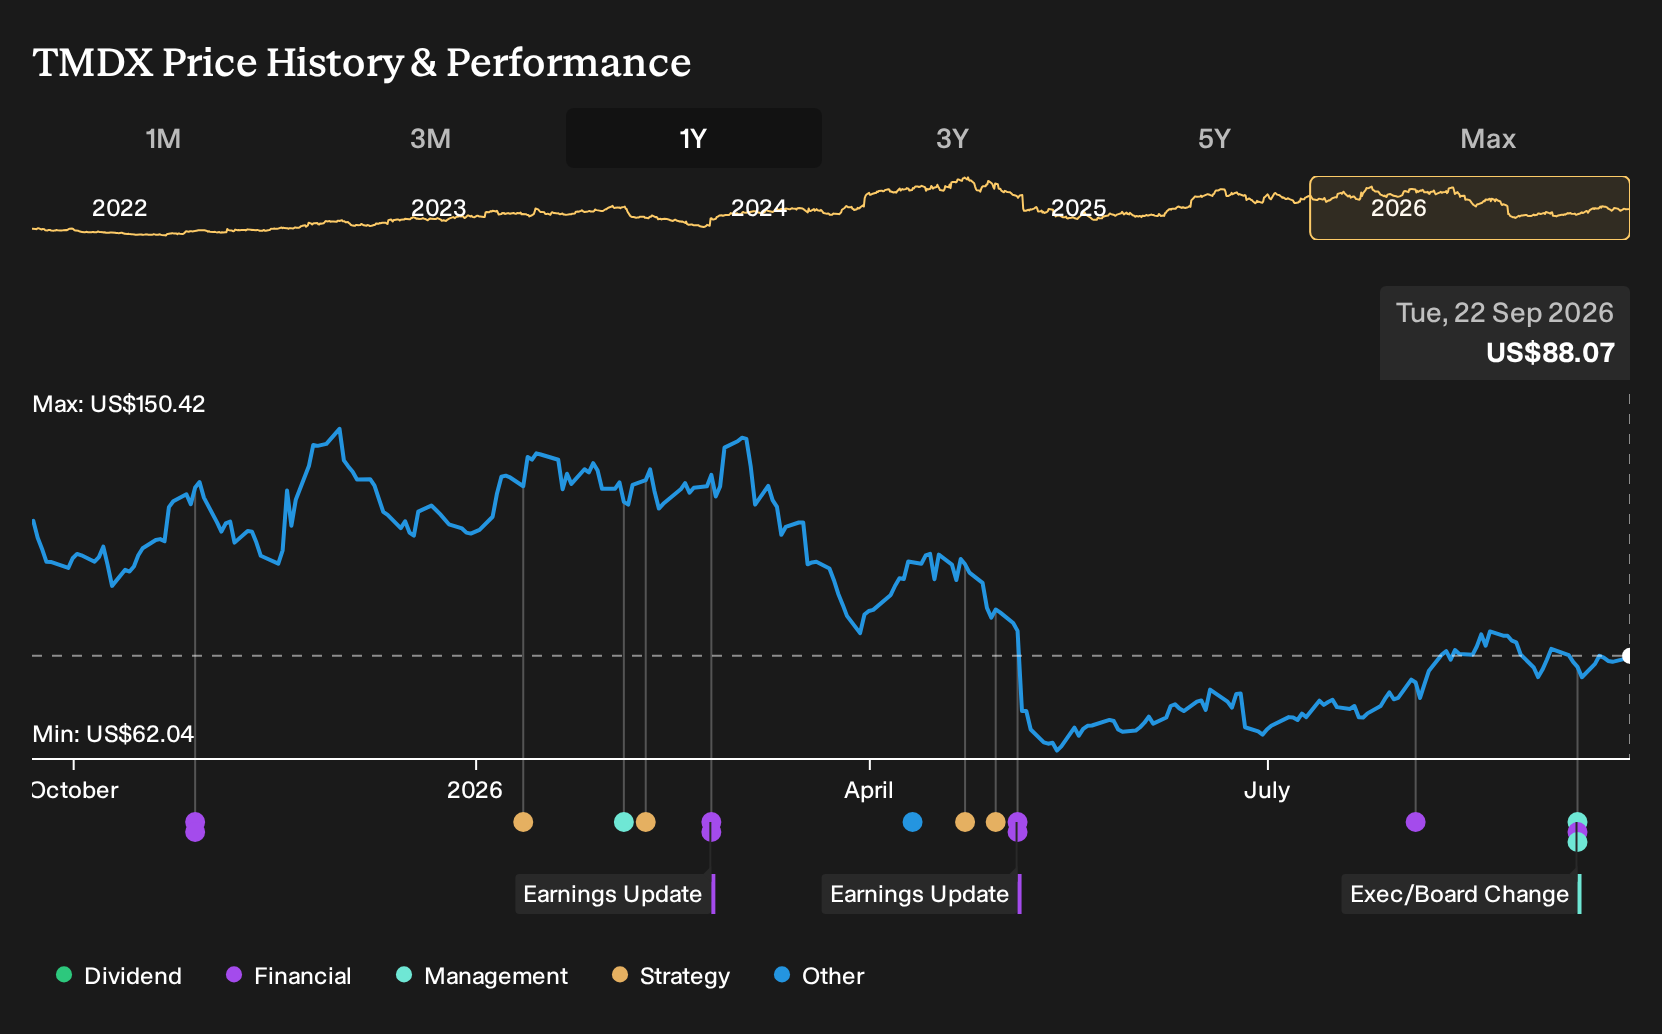
- TransMedics Group appointed Fernando Araujo as Chief Financial Officer and Treasurer, effective 21 September 2026, and kept outgoing CFO Gerardo Hernandez on in advisory roles to support a staged handover and Latin American expansion.
- The reaffirmed 2026 revenue outlook of US$737 million to US$757 million, excluding PAD Aviation Service GmbH contributions, highlights management’s focus on transplant demand execution rather than one off deal effects.
- We will now explore how TransMedics Group's reaffirmed 2026 revenue guidance could reshape its investment narrative and risk profile.
TransMedics Group Investment Narrative Recap
To own TransMedics Group, you need to believe the OCS platform and service model can keep gaining share as transplant volumes evolve globally. The reaffirmed 2026 revenue outlook of US$737 million to US$757 million keeps the near term story anchored on execution, not on PAD Aviation contributions. That makes transplant demand, utilization and hospital adoption the key levers to watch.
The biggest near term swing factor is whether TransMedics can scale internationally without significantly pressuring margins, especially as regulatory focus on organ procurement remains high. The CFO transition and phased handover look manageable, so the headline risk around this news event itself appears limited for the current operating outlook.
The most relevant update is the decision to keep 2026 revenue guidance unchanged while bringing in Fernando Araujo as Chief Financial Officer and Treasurer. That pairing signals management is running the business against a fixed operational yardstick in the near term, with any PAD Aviation upside kept separate for now. For you, it simplifies what to track.
Execution around that US$737 million to US$757 million range now sits beside a more complex capital allocation and scaling agenda that Araujo has faced in other healthcare settings. Hernandez shifting to a Latin America advisory role ties directly into international expansion, which remains both a potential catalyst and a risk if reimbursement, regulation or transplant infrastructure affect adoption.
What the TransMedics Group Forecasts Really Assume
TransMedics Group's narrative projects US$1.1b revenue and US$192.7 million earnings by 2029. This implies analysts are baking in 18.0% yearly revenue growth and an earnings increase of about US$41 million from US$151.7 million today.
Uncover why TransMedics Group's fair value indicates a 10% potential upside to its current price before the discount to expectations closes.
Exploring Other Perspectives
One alternate storyline around TransMedics Group focuses on margin pressure rather than transplant demand. The most cautious analysts were penciling in profit margins near 10.6% and earnings of about US$111.1 million by 2029, versus today’s US$151.7 million. That is a very different picture. This CFO change and reiterated guidance may eventually shift those views, so treat them as moving pieces, not fixed facts.
Explore 6 other TransMedics Group fair value estimates, including one that suggests as much as 26% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TransMedics Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for TransMedics Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TransMedics Group's overall financial health at a glance.
Looking for more TransMedics Group sized ideas?
If TransMedics Group is already on your radar, it can help to put it alongside a watchlist of other candidates that match your risk, income, and quality preferences. The Simply Wall St Screener is built for exactly that kind of comparison so you can stress test your thesis across a wider field.
- If you care most about quality at a sensible entry point, start by scanning our 29 high quality undervalued stocks that combine fundamentals with price appeal.
- If capital protection and steadier profiles matter more to you than headline growth, filter the market using a 30 resilient stocks with low risk scores that score well on resilience.
- If you want to broaden your watchlist with financially sound operators, expand your search through a list of solid balance sheet and fundamentals (23 results) that already clear basic strength checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com