


Brady has had a strong multi‑year run, so the recent pullback naturally raises the question of whether the current share price still lines up with what its earnings can support. With the story now shaped by both a longer track record and fresh expectations around its new business segment, the valuation conversation is getting more focused.
- Over the past 5 years, Brady has delivered a 77.9% share price gain, which puts real pressure on today’s P/E to be backed by equally resilient earnings power.
- Management is pointing to higher adjusted earnings helped by the Intelligent Productivity Solutions unit and planned cost synergies, which can influence how much investors are willing to pay for each dollar of profit.
- There is a second opinion on Brady worth weighing. See what analysts think Brady's shares could be worth.
The issue now is whether Brady's current valuation can be justified by its earnings when set against the Fair Ratio benchmark and the stock’s recent price swings.
If you want to test the same earnings based valuation question beyond Brady, compare it with companies in the 29 high quality undervalued stocks.
Does Brady Look Undervalued on Earnings?
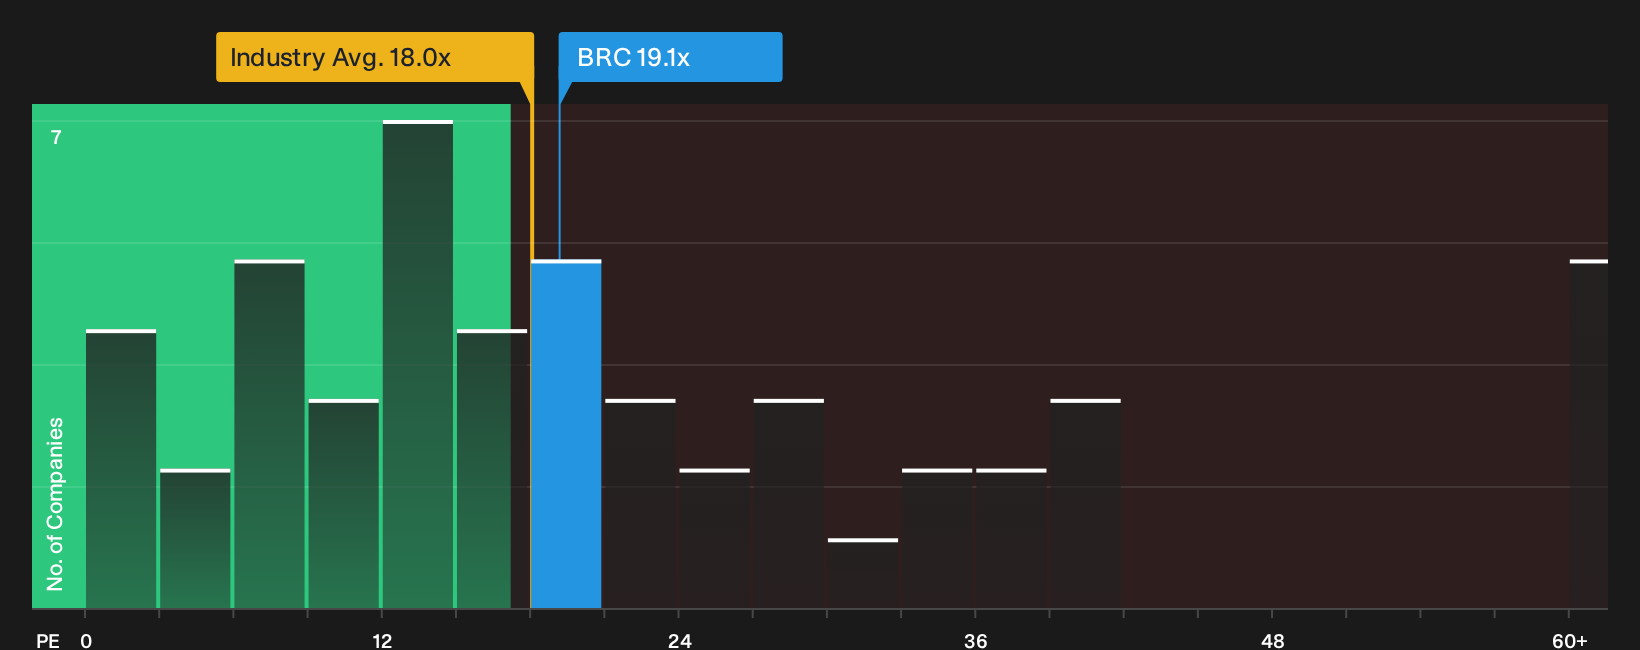
The P/E ratio fits Brady because adjusted earnings per share are central to how management itself frames progress. Brady trades on roughly 19.1x earnings, which is above the Commercial Services sector average of about 18.0x and also above the peer group on roughly 15.3x. On the face of it, the stock carries a clear premium to a typical industry listing on this measure.
That premium still leaves Brady below the multiple that the Fair Ratio framework suggests for a business with its mix of margins, growth profile, scale and risk. As a result, the current P/E screens as undervalued on that tailored yardstick. Because the recent guidance calls for adjusted EPS of US$6.25 to US$6.75, helped by accretion from Intelligent Productivity Solutions, the gap between what investors currently pay for each dollar of earnings and what the model points to as fair will be important to track. Explore the numbers behind Brady's P/E valuation.
The Brady Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Brady P/E puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to look meaningfully more expensive or cheaper than it does today. They sit on the platform's Community page so you can see how different views line up. Each narrative ties its number to a specific take on how Brady's growth, margins and risks might evolve, which you can revisit as fresh results and guidance emerge.
One of the top community narratives on Brady: 22% undervalued
"Strong R&D investments and strategic acquisitions are driving growth in automation, traceability, and compliance solutions, expanding Brady's presence in higher-margin markets..."
Discover why this Narrative puts Brady at 22% undervalued.
One more Brady check that sits outside the earnings math
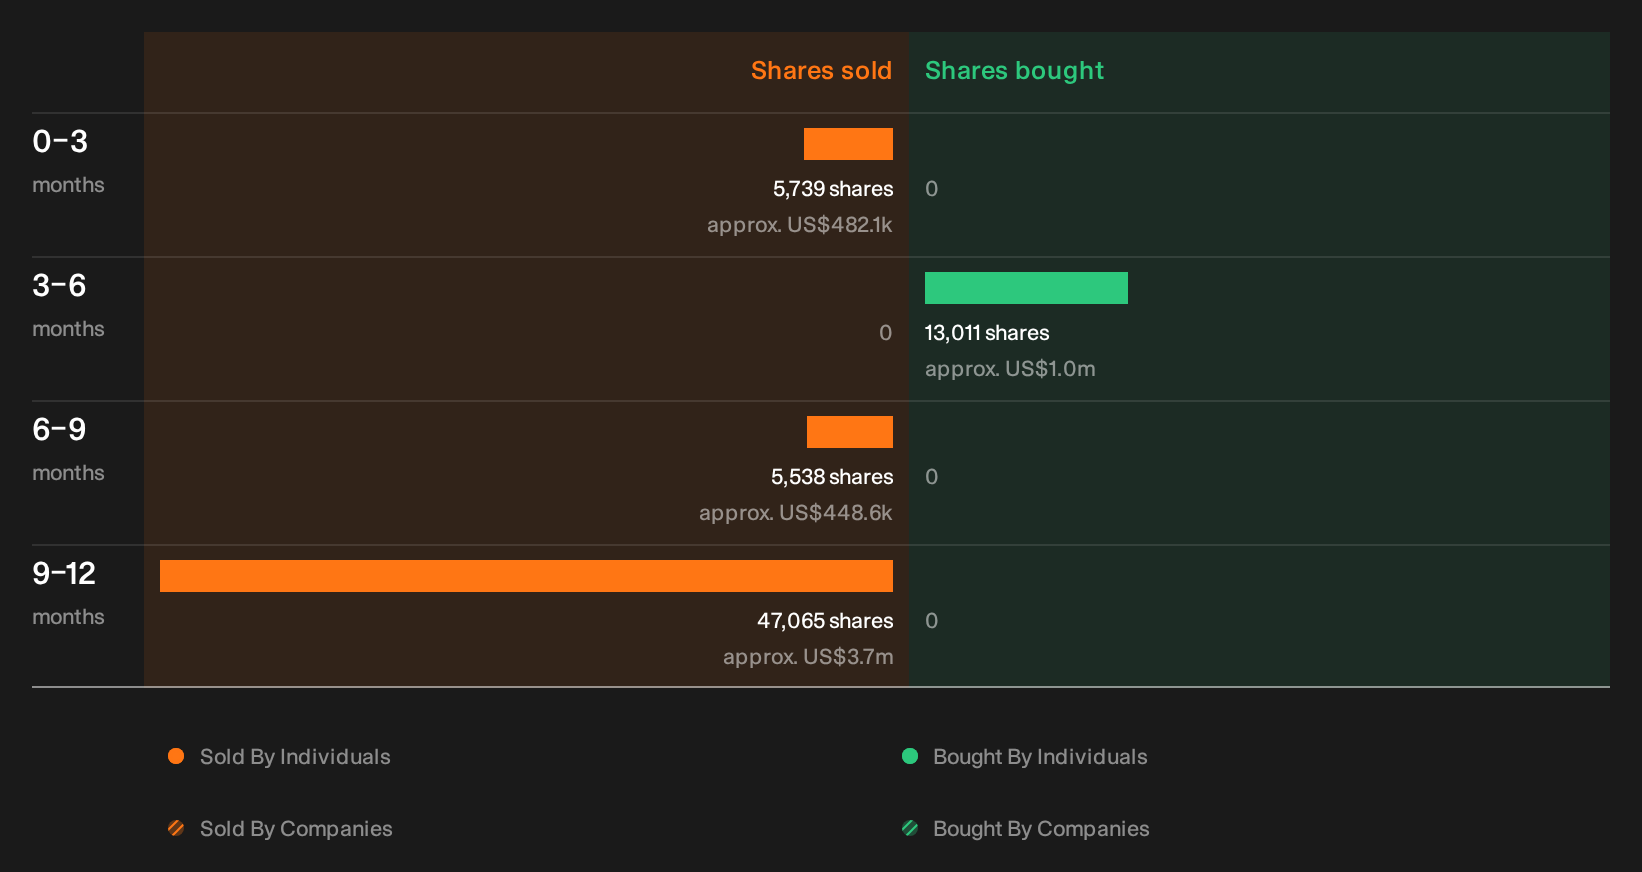
Price multiples tell one story, but the recent trading activity by people inside Brady adds a different layer that is only visible once you look at who has been selling, how much, and when. See the recent insider selling flagged for Brady.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com