


Syndax Pharmaceuticals has delivered a 21.2% gain over the past year, which puts fresh attention on what investors are paying for its current level of sales. After that move, the question is how well the share price lines up with the revenue base that supports it.
- The stock's 21.2% return over the last 12 months puts recent buyers in profit, which raises the stakes on whether its sales footprint can support the current valuation.
- The business model relies on turning its research portfolio into commercial products, so expectations for future revenue and the timing of cash inflows can heavily influence how investors judge what its present sales are worth.
- The analysts covering Syndax Pharmaceuticals have run their own numbers. See what analysts think Syndax Pharmaceuticals's shares could be worth.
The issue now is whether Syndax Pharmaceuticals' current share price is justified by the value investors place on its sales today.
If you are weighing Syndax Pharmaceuticals against other opportunities that trade on the strength of their current sales, it can help to line it up beside 29 high quality undervalued stocks.
Is Syndax Pharmaceuticals Getting Expensive on Sales?
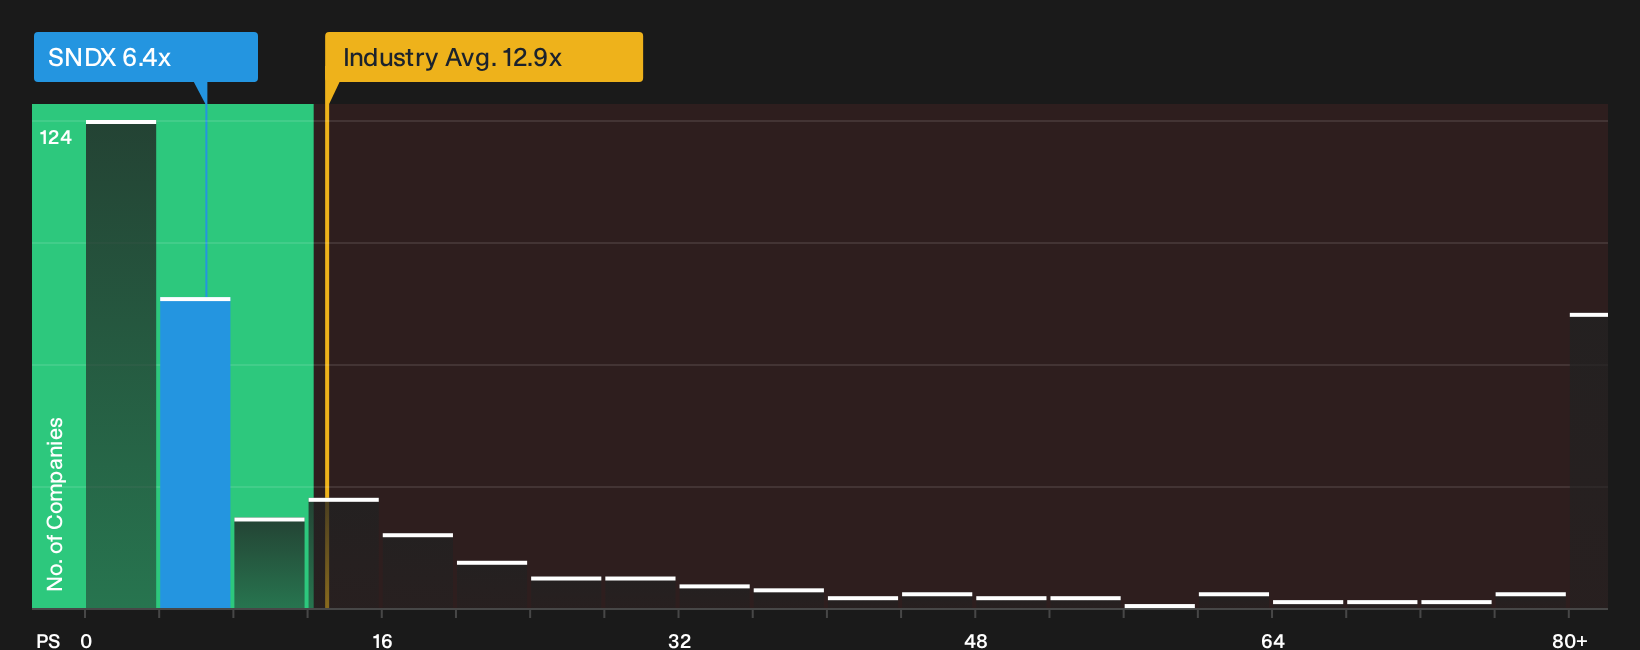
The P/S ratio fits Syndax Pharmaceuticals because the story is still about commercialising its pipeline rather than current profits. The stock trades on a P/S of 6.4x, which is below the Biotechs sector average of 12.9x and also below the peer group at 26.5x. That alone indicates the market is not assigning the same revenue premium to Syndax as it is to many comparable drug developers.
The fair multiple implied by the valuation framework suggests Syndax Pharmaceuticals would trade on a lower P/S than today, so the shares screen as overvalued on this metric despite the discount to peers. That gap reflects how the model balances revenue against factors such as cash burn, risk and execution uncertainty, rather than simply matching the wider sector. If you hold or are considering the stock, the question is whether your conviction on the pipeline and commercial ramp justifies paying above that modelled P/S level. Explore the numbers behind Syndax Pharmaceuticals's P/S valuation.
The Syndax Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives pick up where the P/S puzzle for Syndax Pharmaceuticals leaves off, by spelling out the specific expectations for future growth, margins and earnings that would need to hold for the stock to be worth materially more or less than today’s market price. They sit on Simply Wall St’s Community page so you can see the real-world story that sits behind a single valuation number and track whether those conditions actually play out over time.
One of the top community narratives on Syndax Pharmaceuticals: 30% undervalued
"Heavy dependence on a few lead assets exposes Syndax to significant clinical, competitive, and regulatory risks that could disrupt future revenue and margin growth..."
Discover why this Narrative puts Syndax Pharmaceuticals at 30% undervalued.
Before acting on Syndax Pharmaceuticals’ valuation, there is one more angle to check
The figures only tell part of the story for Syndax Pharmaceuticals, because the people setting priorities and how they are rewarded can tilt the whole risk and reward profile. See who runs Syndax Pharmaceuticals and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com