


The commodity complex was largely in the red early Wednesday morning, though rather than erasing Monday's explosive rally this is likely the calm before algorithms are triggered once again.
In the Grains sector, both Corn and Soybeans were under pressure on what could be commercial harvest selling following the recent noncommercial-led rally in futures markets.
Since SRW fundamentals continue to lean bearish, noncommercial interests have possibly moved back to a net-short futures position.
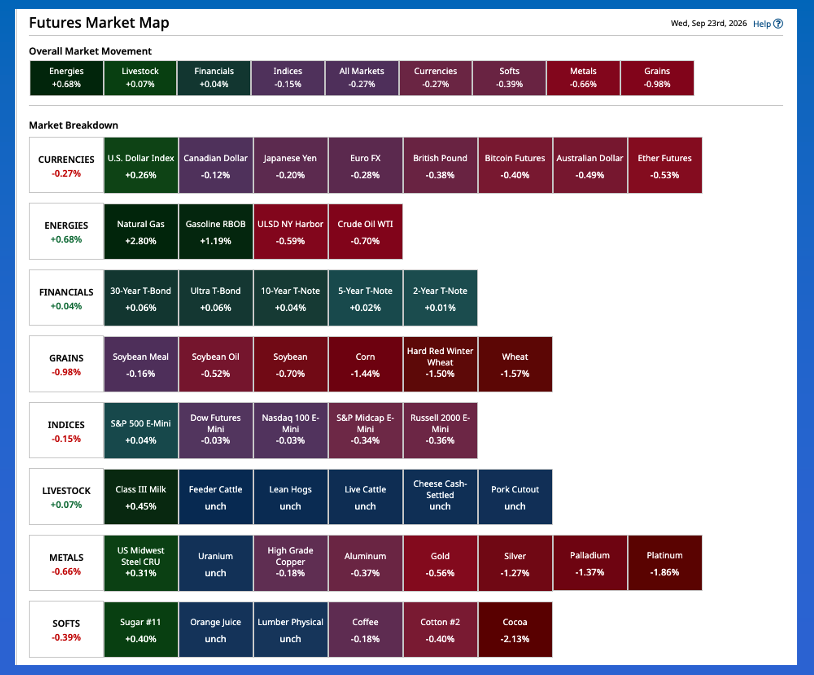
Morning Summary: I wasn’t sure what to expect from markets early Wednesday morning, so I dawdled a bit over a second cup of coffee, checked the baseball box scores (Yes, the Kansas City Royals lost again, this time to the hated Chicago White Sox, but at least the Damn Yankees lost as well.), and killed as much time as possible before firing up the quote screen. There is a time for everything, and it was time to get started on Morning Commentary. What I found was most markets in the commodity complex were in the red as a new noncommercial positioning week got under way. Does this erase what we saw with the explosive buying nearly across the board this past Monday? No. With but a few exceptions, I think we can throw out what we see early Wednesday morning, and probably the rest of the day, as algorithms wait to be fed the next round of untruths following Thursday’s meeting between the US president and China’s President Xi. We know – KNOW – the US side will claim victory by saying “it was a great meeting” and that “China will buy everything the US can produce from now until the end of time”. Meanwhile, the Chinese delegation will leave town quietly and things will go on as they have the past decade.
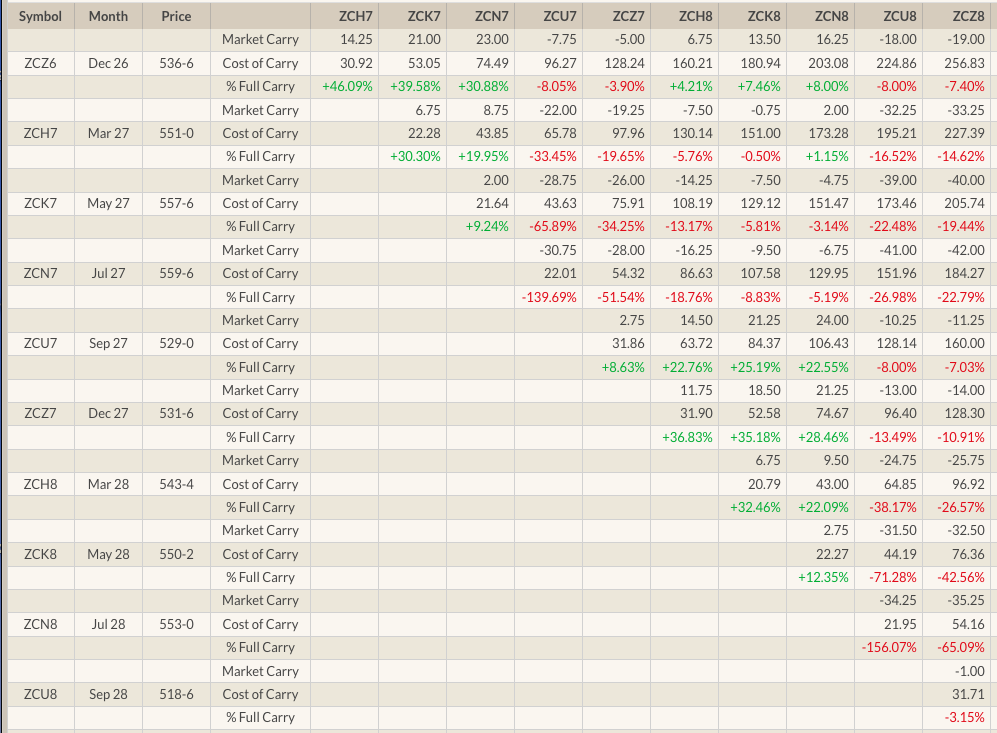
Corn: Based on the theme of this morning’s conversation, “A time for everything”, a look at the corn market and we might jump to the conclusion that harvest has finally arrived. Yes, I know, according to NASS’ weekly updates the US corn harvest was supposedly 13% complete as of last Sunday, but if folks are naïve enough to see those numbers as anything but nonsense, I still have that mountain-top villa in southwest Kansas to sell you. What have I heard about harvest this season? Recall my friend in central Illinois reported a solid decrease in yield from the last few years, while friends from central Nebraska are reporting strong yields so far this year. As for the market, national average basis remains weak meaning there was plenty of leftover corn on hand as harvest got under way, with supplies being replenished by sales of bushels coming across the scales due to the recent rally. As for futures spreads, the Dec-March remains neutral, covering 46% calculated full commercial carry at Tuesday’s close. Further out, the commercial view remains bullish as the March-May covered 30% and the May-July 9%. For the record, Dec26 (ZCZ26) was down 7.0 cents at this writing.
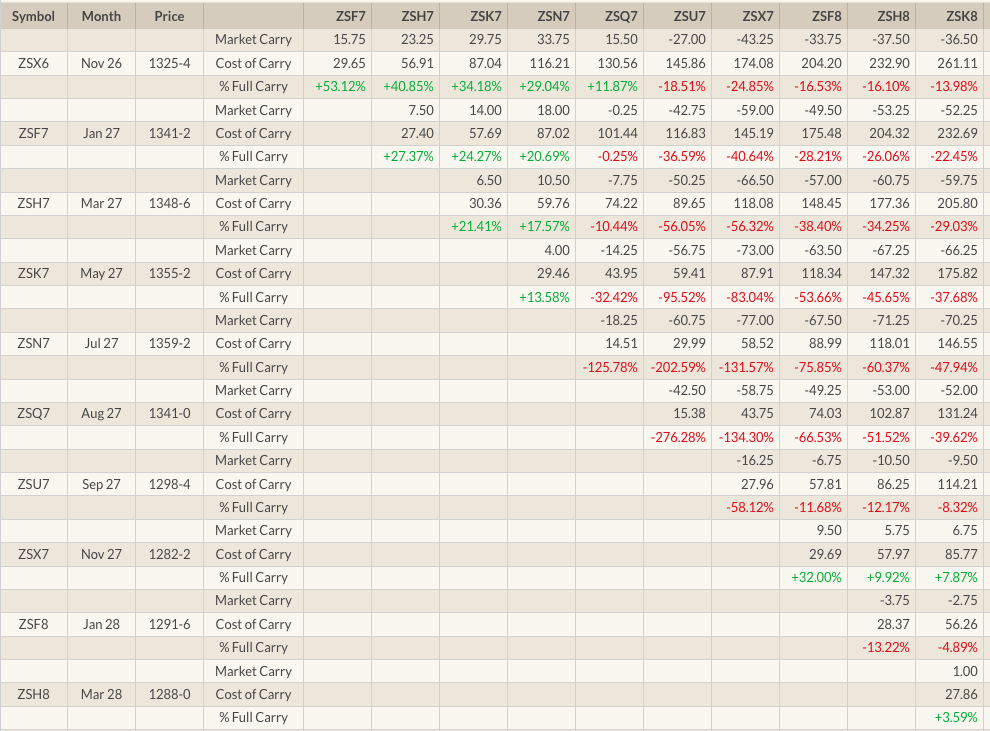
Soybeans: The soybean market was also under pressure early Wednesday morning, also on what looked to be possible harvest-related commercial selling. Again, NASS has been telling us the past couple weeks combines were rolling across the US, most notably the southeast growing area of the country, but since we don’t actually know acres, the estimate of how much harvest has progressed is, again, an imaginary number. But I digress. The November contract (ZSX26) lost as much as 9.25 cents overnight and was sitting 8.5 cents lower at this writing. A look back at Tuesday’s close and we see the Nov-January futures spread covered a still neutral 53% calculated full commercial carry while the Jan-March, March-May, and May-July were all in bullish territory below 30%. What should we expect with the US soybean market over the coming days? Again, we know the US administration will brag about how it made China buy as much as it has recently. Given the administration doesn’t believe in science, including the study of weather patterns, it will pay no attention to the reality Chinese buyers are securing secondary supplies on the idea Brazil’s 2027 crop could face weather issues. This could lead to another round of buying from algorithms, calling into question the lack of intelligence.
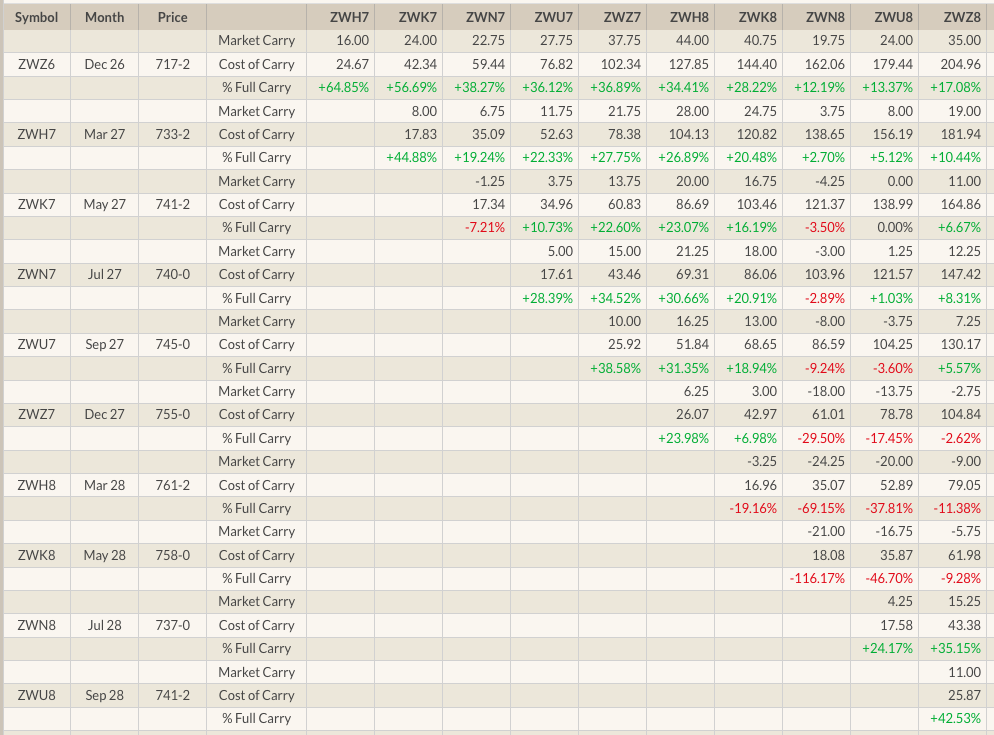
Wheat: The wheat sub-sector was deep in the red to start another day. A look at the more heavily traded SRW market and we see the December issue (ZWZ26) dropped as much as 10.75 cents and was one tick off its session low at this writing, albeit on trade volume of only 11,100 contracts. As I mentioned yesterday, this is light activity meaning a simple sneeze (computer virus?) from Watson could spark a rally. Unless Market Rule #6 still matters. If fundamentals do win in the end, and SRW remains fundamentally bearish, despite what the BRACE Industry continues to tell us, then Waston actually has no reason to defend what’s left of its net-long futures position. Let me stop myself there: Last Friday’s Commitments of Traders report showed funds held a net-long SRW futures position of only 1,230 contracts as of Tuesday, September 15. At yesterday’s close, the Dec SRW issue was down 11.25 cents for the Tuesday-to-Tuesday positioning week while the carry in the Dec-March futures spread was unchanged at 16.0 cents during that same time frame. For the record, the 16.0 cents covered a bearish leaning 65% calculated full commercial carry. This indicates funds have likely liquidated the net-long futures position and possibly gone net-short again.
On the date of publication, Darin Newsom did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.