


Western Digital has delivered an extraordinary run in recent years, which puts a bright spotlight on whether the current share price lines up with what its earnings can support. After such a move, the key issue for investors is whether the business is now priced mainly on hard profit power or on optimism about what comes next.
- Western Digital has returned roughly 13x over the past 3 years, so a lot of future profit expectations are already embedded in the current valuation debate.
- Fresh headlines around memory makers exploring new partnerships and capacity moves may support expectations for stronger earnings power at Western Digital if demand for advanced storage holds up.
- The analysts covering Western Digital have run their own numbers. See what analysts think Western Digital's shares could be worth.
The stock's next move may depend on whether Western Digital's earnings are strong enough to justify the price investors are paying today.
To see how Western Digital compares with other storage and chip makers being priced on big earnings stories, it helps to line it up against 86 AI infrastructure stocks.
Is Western Digital Still Cheap on Earnings?
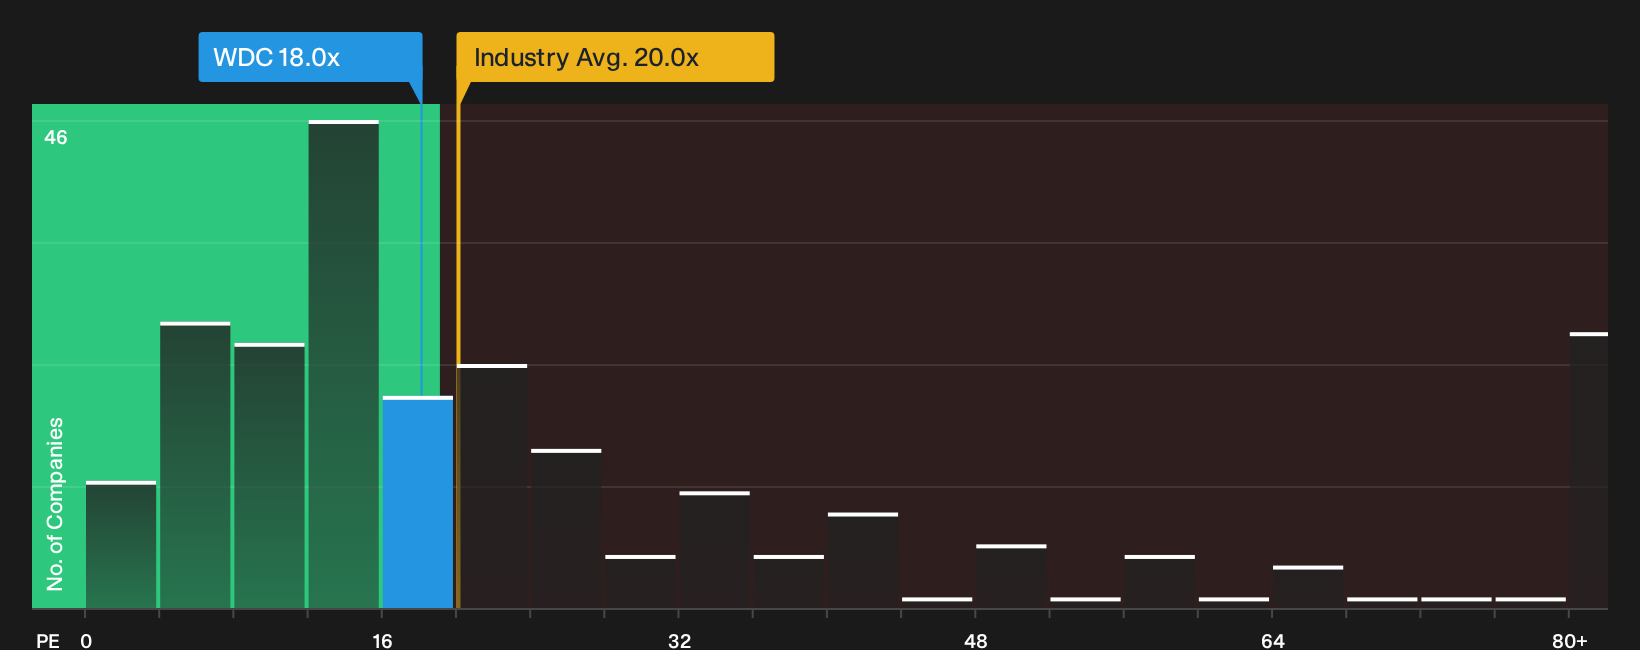
The P/E ratio is a useful way to think about what you are paying today for Western Digital's earnings power. On this measure, the stock trades at about 18.0x, which is slightly below the broader Tech sector average of roughly 20.0x and sits at a wide discount to peers on roughly 37.7x.
Because the recent SK Hynix and Intel discussions have pushed memory valuations into focus, that gap to peer pricing is hard to ignore. The fair value model, which adjusts the P/E investors might expect for Western Digital given its margins, growth profile, scale and risk, points to a higher ratio than where the shares trade now. On this framework, the current P/E screens as undervalued. That leaves the market multiple suggesting the stock is priced below what similar earnings stories and the tailored fair value yardstick might imply. Explore the numbers behind Western Digital's P/E valuation.
The Western Digital Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where this valuation puzzle for Western Digital leaves off. They spell out which future paths for revenue, profitability and earnings would need to play out for the stock to look meaningfully stronger or weaker than today’s price. Rather than a single multiple or fair value output, each narrative lays out the underlying assumptions so you can compare them with Western Digital's actual results as they are reported.
Western Digital brings out sharply different views, with some holders leaning into the AI storage upside while others focus on how long current conditions last.
Bull case: 30% undervalued
"The explosive increase in unstructured data generated by AI applications, Agentic AI, and cloud-based services across industries is still driving unprecedented storage needs…"
Discover why this Narrative puts Western Digital at 30% undervalued.
Bear case: 41% overvalued
"Here is the tension. That golden hour is priced as if it lasts…"
Explore why this Narrative puts Western Digital at 41% overvalued.
For Western Digital, the share price is only half the story
Western Digital's future will not just depend on storage demand or P/E ratios. It will also hinge on who is steering the ship and how their incentives line up with yours. See who runs Western Digital and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com