


As the Canadian market navigates the implications of recent U.S. Federal Reserve rate hikes and anticipates a potentially faster pace of tightening by the Bank of Canada, investors are closely watching for opportunities that can thrive in a higher-yield environment. In this context, growth companies with high insider ownership often stand out as compelling options, as they may benefit from strong internal confidence and alignment with shareholder interests amidst evolving economic conditions.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 16.9% | 130% |
| Propel Holdings (TSX:PRL) | 25.7% | 39.7% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32% |
| Firan Technology Group (TSX:FTG) | 12.6% | 22% |
| Electrovaya (TSX:ELVA) | 34.9% | 47.9% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.9% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
| Aritzia (TSX:ATZ) | 16.2% | 20.3% |
| Allied Gold (TSX:AAUC) | 15.4% | 39.4% |
Here's a peek at a few of the choices from the screener.
Allied Gold (TSX:AAUC)
Simply Wall St Growth Rating: ★★★★★★
Overview: Allied Gold Corporation, along with its subsidiaries, is a gold mining company operating in Africa with a market capitalization of approximately CA$4.38 billion.
Operations: The company generates revenue from its operations at the Agbaou Mine ($342.65 million), Bonikro Mine ($417.75 million), and Sadiola Mine ($733.45 million).
Insider Ownership: 15.4%
Revenue Growth Forecast: 20.1% p.a.
Allied Gold is poised for significant growth with the Kurmuk Mine in Ethiopia nearing operational status, enhancing gold production and cash flows. Despite recent insider selling, the company benefits from high insider ownership and strategic investments like Zijin Gold's 9.2% stake. Allied trades significantly below its estimated fair value while analysts forecast revenue growth of over 20% annually, surpassing market averages. Recent board changes add financial expertise to support its expansion strategy.
- Dive into the specifics of Allied Gold here with our thorough growth forecast report.
- Insights from our recent valuation report point to the potential undervaluation of Allied Gold shares in the market.
Kits Eyecare (TSX:KITS)
Simply Wall St Growth Rating: ★★★★☆☆
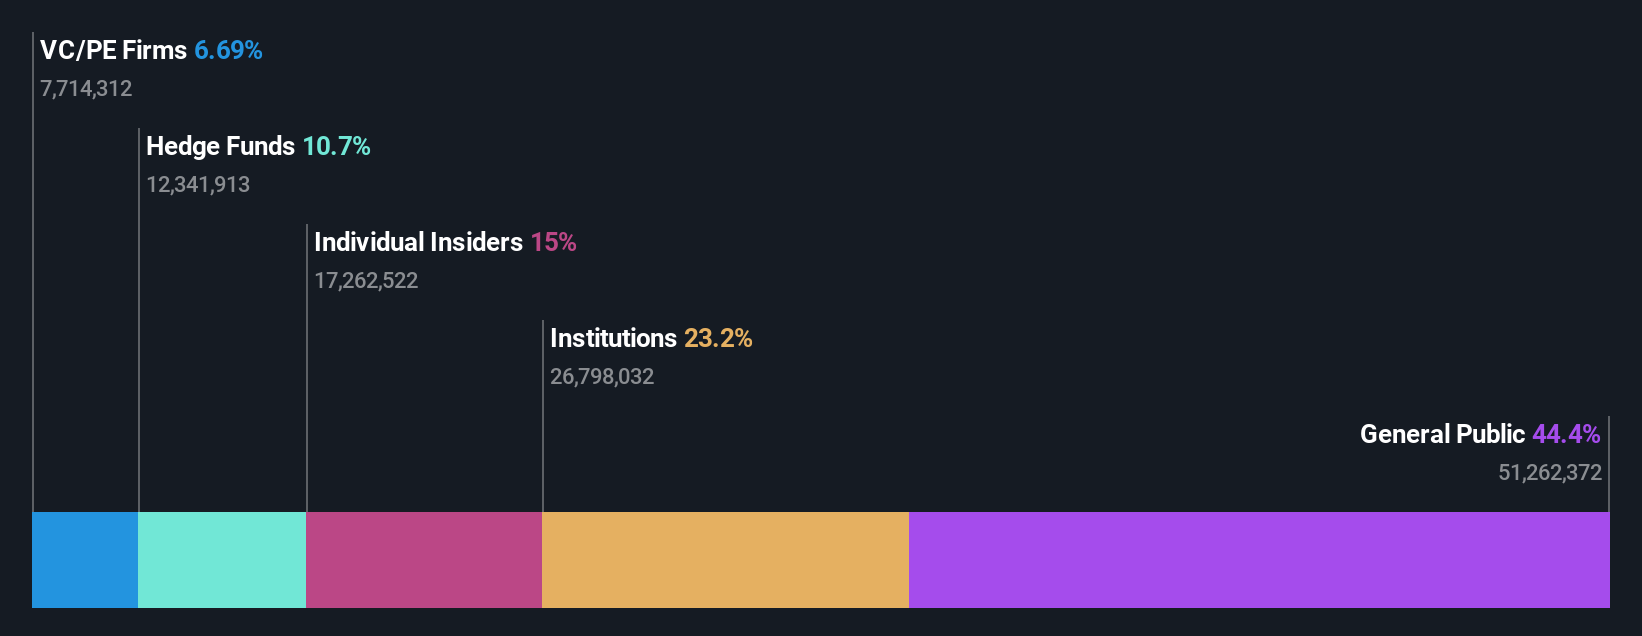
Overview: Kits Eyecare Ltd. operates a digital eyecare platform in the United States and Canada, with a market cap of CA$538.32 million.
Operations: Revenue from the sale of eyewear products amounts to CA$222.18 million.
Insider Ownership: 26.5%
Revenue Growth Forecast: 18.1% p.a.
Kits Eyecare's inclusion in the S&P Global BMI Index highlights its growth trajectory, supported by strong insider ownership. The company reported improved financial performance with a net income of C$1.46 million for Q2 2026, reversing a loss from the previous year. Analysts forecast significant earnings growth at 41.37% annually, outpacing the Canadian market average of 11.3%. Despite no recent insider trading activity, Kits Eyecare's strategic positioning suggests potential for continued expansion.
- Get an in-depth perspective on Kits Eyecare's performance by reading our analyst estimates report here.
- The analysis detailed in our Kits Eyecare valuation report hints at an inflated share price compared to its estimated value.
VersaBank (TSX:VBNK)
Simply Wall St Growth Rating: ★★★★★☆
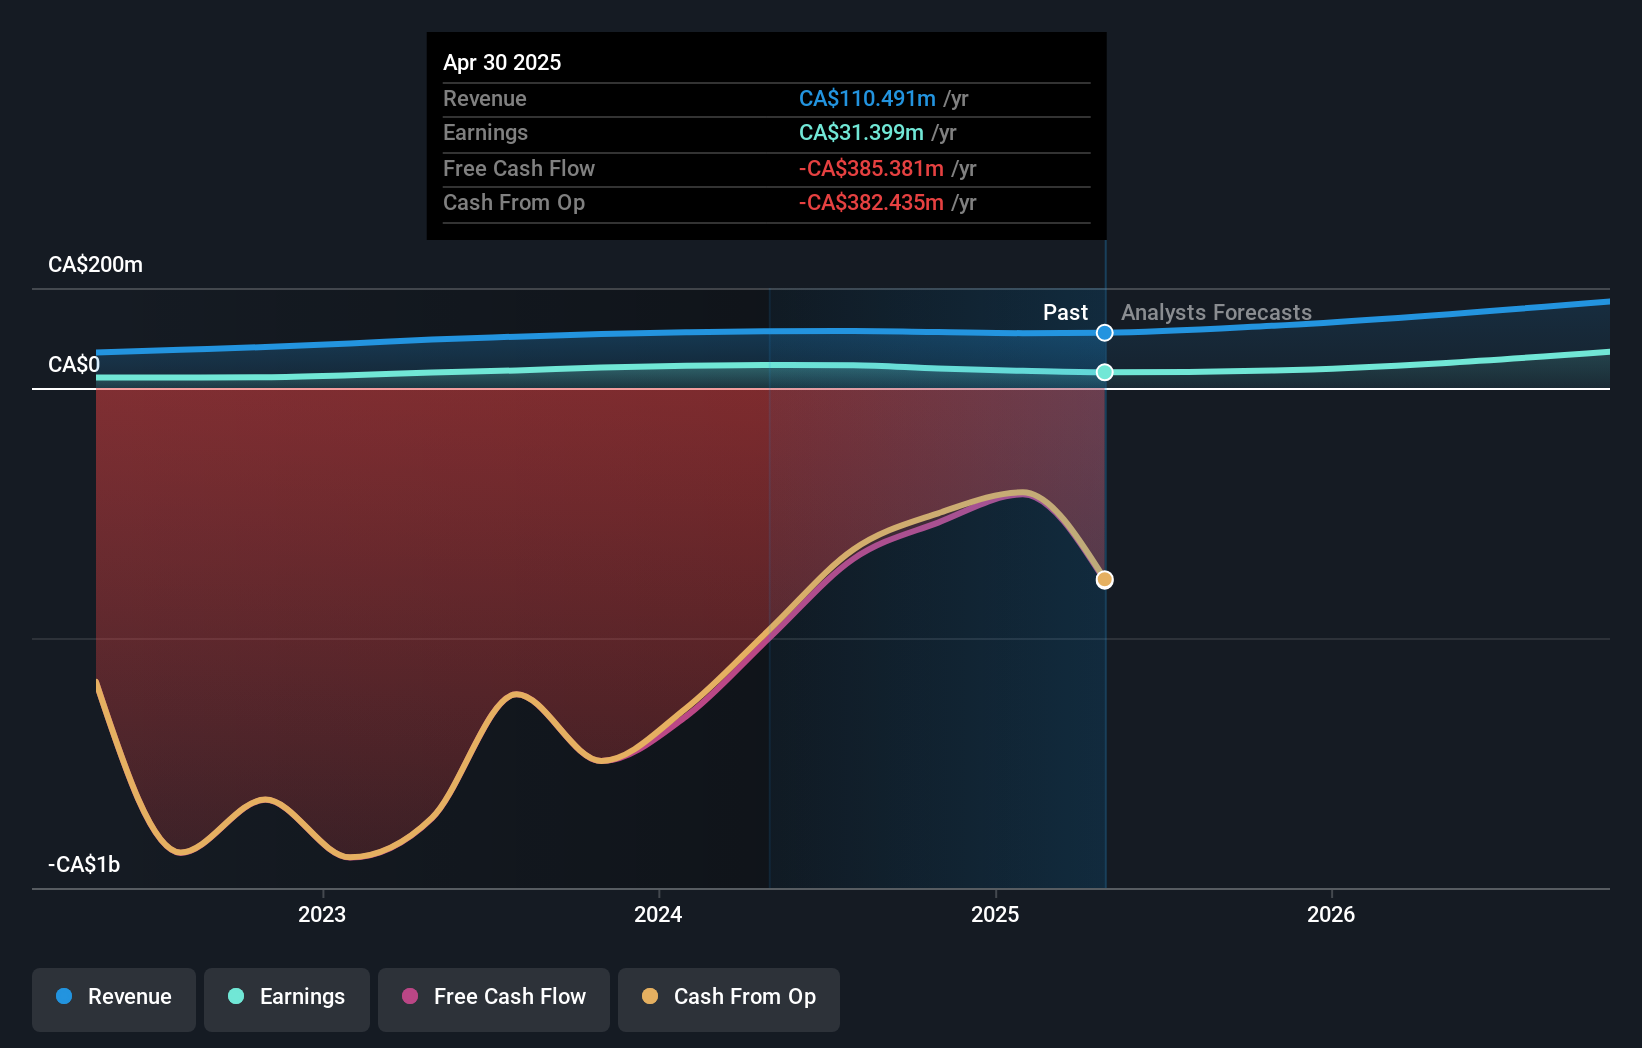
Overview: VersaBank offers a range of banking products and services in Canada and the United States, with a market cap of CA$1.03 billion.
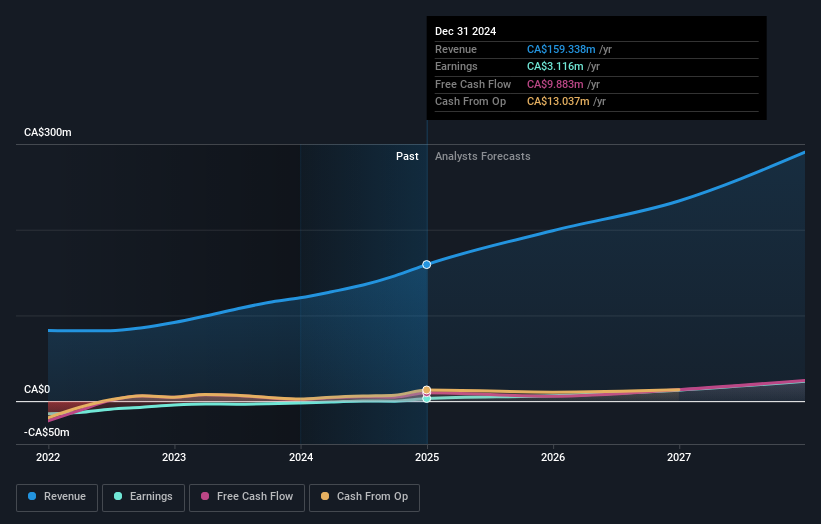
Operations: The company's revenue segments include Digital Meteor at CA$2.36 million, Digital Banking USA at CA$29.52 million, Digital Banking Canada at CA$108.39 million, and DRTC services encompassing cybersecurity and financial technology development at CA$7.60 million.
Insider Ownership: 11%
Revenue Growth Forecast: 26.9% p.a.
VersaBank's expansion of its Structured Receivable Program (SRP) into the U.S. small business sector marks a significant growth opportunity, leveraging its innovative Real-Time SRP to reduce financing costs for partners. Despite low allowance for bad loans and substantial insider selling recently, earnings are expected to grow significantly at 55.9% annually, outpacing the Canadian market average. The reorganization into a U.S.-based holding company could further enhance strategic positioning and operational efficiency.
- Navigate through the intricacies of VersaBank with our comprehensive analyst estimates report here.
- According our valuation report, there's an indication that VersaBank's share price might be on the expensive side.
Where To Now?
- Dive into all 48 of the Fast Growing TSX Companies With High Insider Ownership we have identified here.
- Ready For A Different Approach? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com