


SharkNinja (SN) has drawn fresh attention after announcing a global partnership with McLaren Racing, linking its consumer appliances to motorsport engineering, alongside recent product launches in cookware and cutlery that expand the Ninja branded kitchen range.
SharkNinja’s latest moves land against a backdrop of strong share price momentum. The stock has delivered a 20.56% 90 day share price return and a 48.45% year to date share price return, while three year total shareholder return sits above 3x.
Capitalize on SharkNinja’s momentum by scanning a hand picked 16 high quality undiscovered gems built around durable brands and strong fundamentals.SharkNinja’s share price has already rewarded early believers, yet the McLaren tie up and new product ranges are still bedding in. Does paying up today make more sense than waiting for a pullback and a cheaper entry?
Most Popular Narrative: 53% Overvalued
SharkNinja’s most followed valuation narrative pegs fair value at $110.73, well below the last close of $169.01, which puts today’s enthusiasm in a very different light.
SharkNinja makes products people genuinely seem to love. My brother-in-law hasn't stopped talking about his Ninja coffee machine. Every gym-goer seems to own a Ninja ice cream maker churning out protein ice cream. And don't get me started on how everyone now owns an air fryer. This is a brand that has quietly embedded itself into daily life and that kind of word-of-mouth loyalty is genuinely hard to manufacture.
See why 8 investors see SharkNinja as 53% overvalued.
According to AshleighG, that popularity supports a quality label, but not any price. The narrative applies a 9% discount rate, assumes revenue growth easing to 6% by 2030 and uses an 11% profit margin with a 21x future earnings multiple, which leads to the $110.73 estimate. With the share price well above that figure, the story leans more toward enthusiasm than a clear bargain.
Result: Fair Value of $110.73 (OVERVALUED)
Still, SharkNinja’s story could shift quickly if consumer budgets tighten further or if tariff and cost pressures squeeze the 11% margin assumption that underpins that fair value.
Find out about the key risks to this SharkNinja narrative.
Another View: SWS DCF Model Says Undervalued
The user narrative pegs SharkNinja at $110.73 and labels the stock as 53% overvalued. Our SWS DCF model points in the opposite direction. On that framework, SN at $169.01 trades at a 28.7% discount to an implied future cash flow value of $236.94, which raises a simple question: Which set of assumptions do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
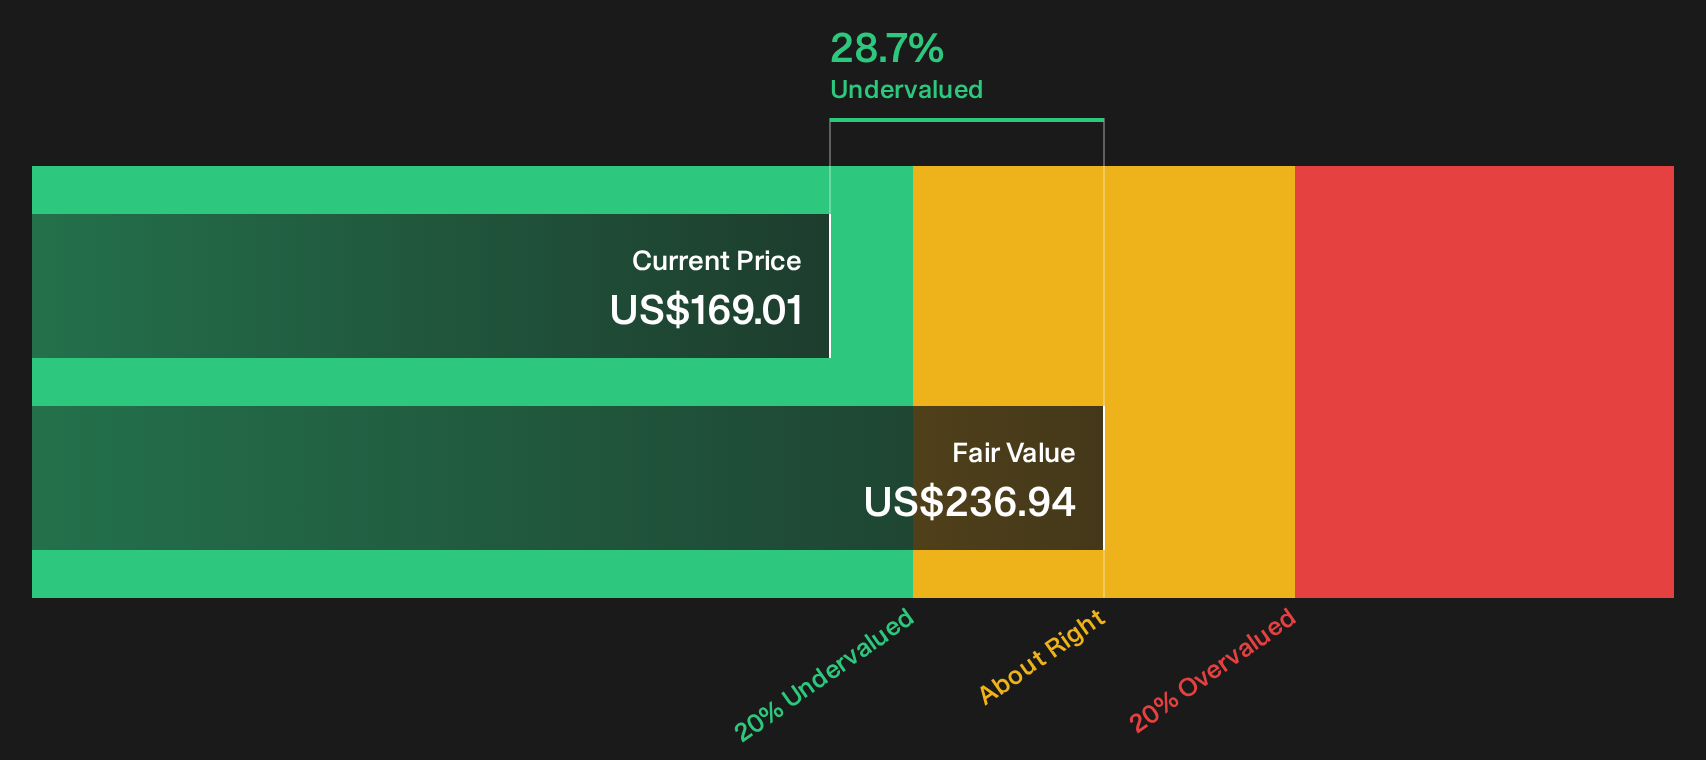
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SharkNinja for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on SharkNinja’s value story. If you want to move fast but stay grounded in the data, start by weighing both the potential upside and the known pressure points. Then stress test your own thesis against the 4 key rewards and 1 important warning sign.
Looking for more SharkNinja style ideas?
If SharkNinja has sharpened your focus on quality, do not stop here. The Simply Wall Street Screener can surface fresh opportunities that fit your own playbook.
- Target potential value opportunities by scanning a curated 29 high quality undervalued stocks that combine solid fundamentals with prices that may lag underlying business strength.
- Lock in income focused ideas through a hand picked 7 dividend fortresses that aim to pair higher yields with resilient cash generation.
- Prioritise resilience first by filtering a 30 resilient stocks with low risk scores that scores well on balance sheet strength and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com