


Valaris (VAL) is back in focus after management highlighted a US$4.7b contract backlog, the largest in a decade. This has drawn fresh attention to the offshore driller’s earnings visibility and recent share price swings.
Recent trading has been choppy for Valaris, with the share price at US$82.72 after a 1-day share price return of 1.14% but a 7-day share price return that declined 6.25%. Over a longer stretch, momentum still leans positive, with a 90-day share price return of 9.53% and a year-to-date share price return of 58.62%. Total shareholder return sits at 63.87% over 1 year and 137.02% over 5 years, pointing to strong longer term gains even after the latest pullback.
Scan rigs-related opportunities beyond Valaris by comparing its US$4.7b backlog and offshore exposure with peers on our curated list of 40 power grid technology and infrastructure stocks
Valaris now trades above the average analyst target while internal fair value estimates imply a wide discount. Is the recent jump stretching reality, or does it still leave meaningful upside on the table?
Most Popular Narrative: 23% Overvalued
On Simply Wall St's widely followed narrative, Valaris screens as materially above its inferred fair value of $67.27 compared with the last close at $82.72. The gap comes from analysts baking in slower profit ahead despite the strong contract backlog that is in the spotlight today.
The industry is experiencing a tightening supply-demand dynamic for technologically advanced rigs, as evidenced by seventh-generation drillship utilization expected to exceed 90% by 2026 and day rates for these rigs averaging 25% higher than prior generations, setting up Valaris's fleet for higher pricing power, increased margins, and improved fleet utilization.
See why 30 investors see Valaris as 23% overvalued.
Result: Fair Value of $67.27 (OVERVALUED)
Still, faster regulatory pressure on offshore drilling or a prolonged period of idle rigs could quickly weaken the bullish Valaris narrative that is currently in play.
Find out about the key risks to this Valaris narrative.
Another View on Valaris Valuation
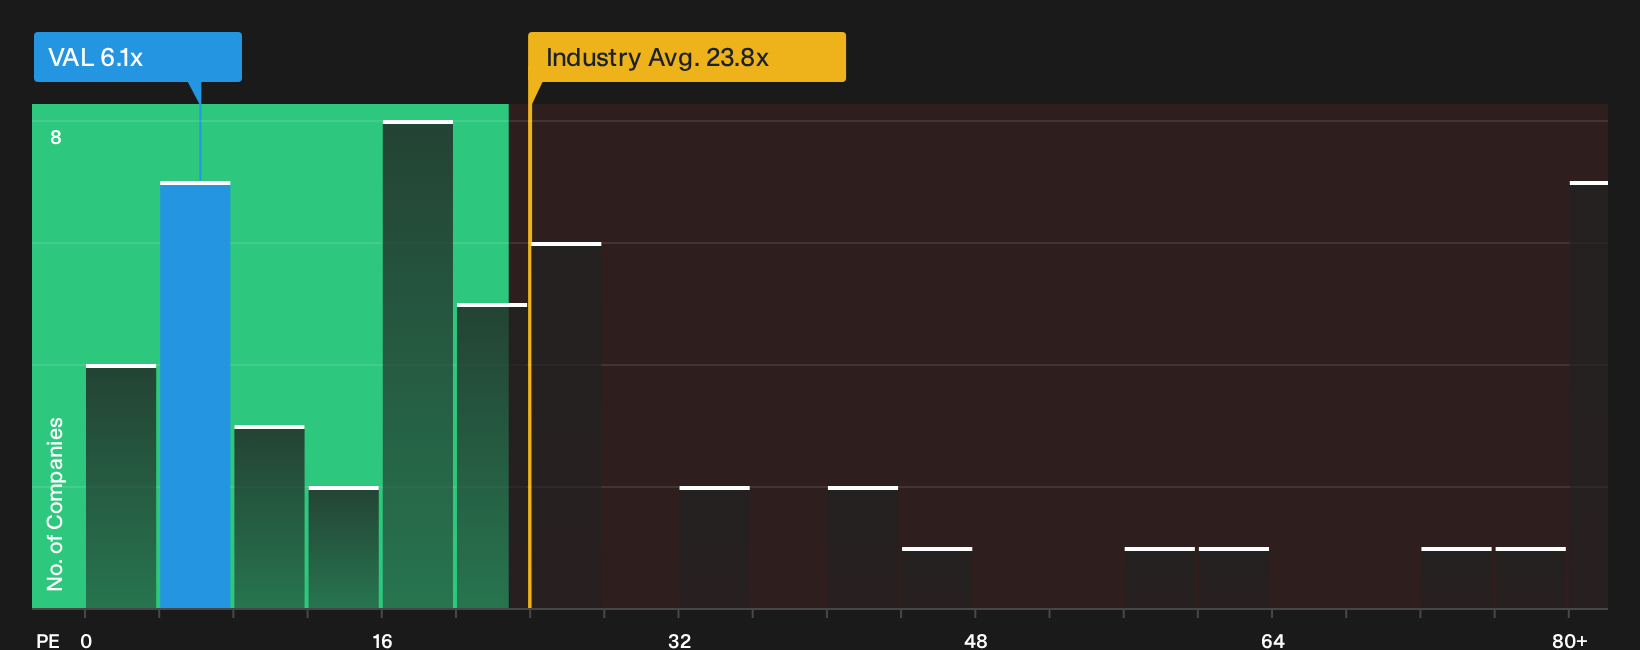
A second lens on Valaris looks at the current P/E of 6.1x versus a fair ratio of 4.4x. That is meaningfully above where the market model suggests it could trade, even though the multiple is far below the US Energy Services average of 24.3x and a peer mark of 31.7x. Is that gap a margin of safety, or a signal that expectations have run ahead of fundamentals?
To see how this pricing compares against the earnings profile and peer group in more detail, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Valaris for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Valaris valuation and risk reward profile. If you want to move quickly and form your own stance, start by weighing its 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Valaris?
If Valaris has sharpened your thinking, do not stop here. Use fresh data driven lists to quickly surface new opportunities that match your own investing style.
- Target proven quality by scanning a list of solid balance sheet and fundamentals (23 results) that highlights companies pairing stronger balance sheets with solid underlying fundamentals.
- Hunt for mispriced opportunities through the 16 high quality undiscovered gems that filters for financially robust businesses still flying under most investors' radar.
- Protect your downside first and let upside follow by starting with the 30 resilient stocks with low risk scores that screens for stocks with more resilient risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com