


Horace Mann Educators has delivered a strong share price run over the past few years, which raises a simple question for investors. Is the current US$47.21 price tag adequately backed by the returns the insurer earns on its capital base?
- Over the past 3 years, Horace Mann Educators has returned 75.7%, which puts real weight on whether those gains are supported by durable returns on the capital it deploys.
- The business model focuses on insurance and financial products for educators, so the quality of its underwriting decisions, expense discipline and investment returns can shape how efficiently each dollar of capital is put to work over time.
- What if you looked at Horace Mann Educators through its earnings instead? See why Horace Mann Educators's 10.8x P/E tells a different valuation story.
The stock's next move may depend on whether the returns Horace Mann Educators earns on its capital are strong enough to justify where the shares trade today.
If you are weighing whether Horace Mann Educators' 75.7% three year return is well supported by the capital it employs, it can help to compare that profile with 30 resilient stocks with low risk scores.
Has Horace Mann Educators Run Too Far on Excess Returns?
The Excess Returns model looks at how efficiently Horace Mann Educators turns its equity base into profits above the cost of that capital. In this view, the business is modeled with a Book Value of $37.11 per share and a Stable EPS of $2.56 per share, both anchored to median figures from the past five years. The Cost of Equity is set at $2.29 per share, leaving an Excess Return of $0.27 per share, with an Average Return on Equity of 8.09%.
The framework also uses a Stable Book Value of $31.60 per share as a long run anchor for the balance sheet. That combination of moderate excess returns on equity and steady book value assumptions leads the Excess Returns model to an estimated intrinsic value that is meaningfully below the current $47.21 share price. This gap suggests the market is assigning a richer multiple to Horace Mann Educators than the modeled stream of excess profits alone might support. Find out what Horace Mann Educators could be worth using our Excess Returns estimate.
The Horace Mann Educators Narrative: What Would Justify Today's Price?
Narratives on Horace Mann Educators pick up where this valuation puzzle leaves off and explain which growth, profitability and earnings paths would need to occur for the stock to be worth meaningfully more or less than it is today, all within Simply Wall St's Community page. Each narrative links its number to a clear view on how Horace Mann Educators' revenue mix, margins and risk profile might change over time, so you can revisit those assumptions as fresh information becomes available.
One of the top community narratives on Horace Mann Educators: 16% undervalued
"Extension of product offerings into supplemental and group benefits, combined with growing sales force and new strategic partnerships, is delivering record supplemental sales growth…"
Discover why this Narrative puts Horace Mann Educators at 16% undervalued.
For Horace Mann Educators, the share price is only one piece of the decision
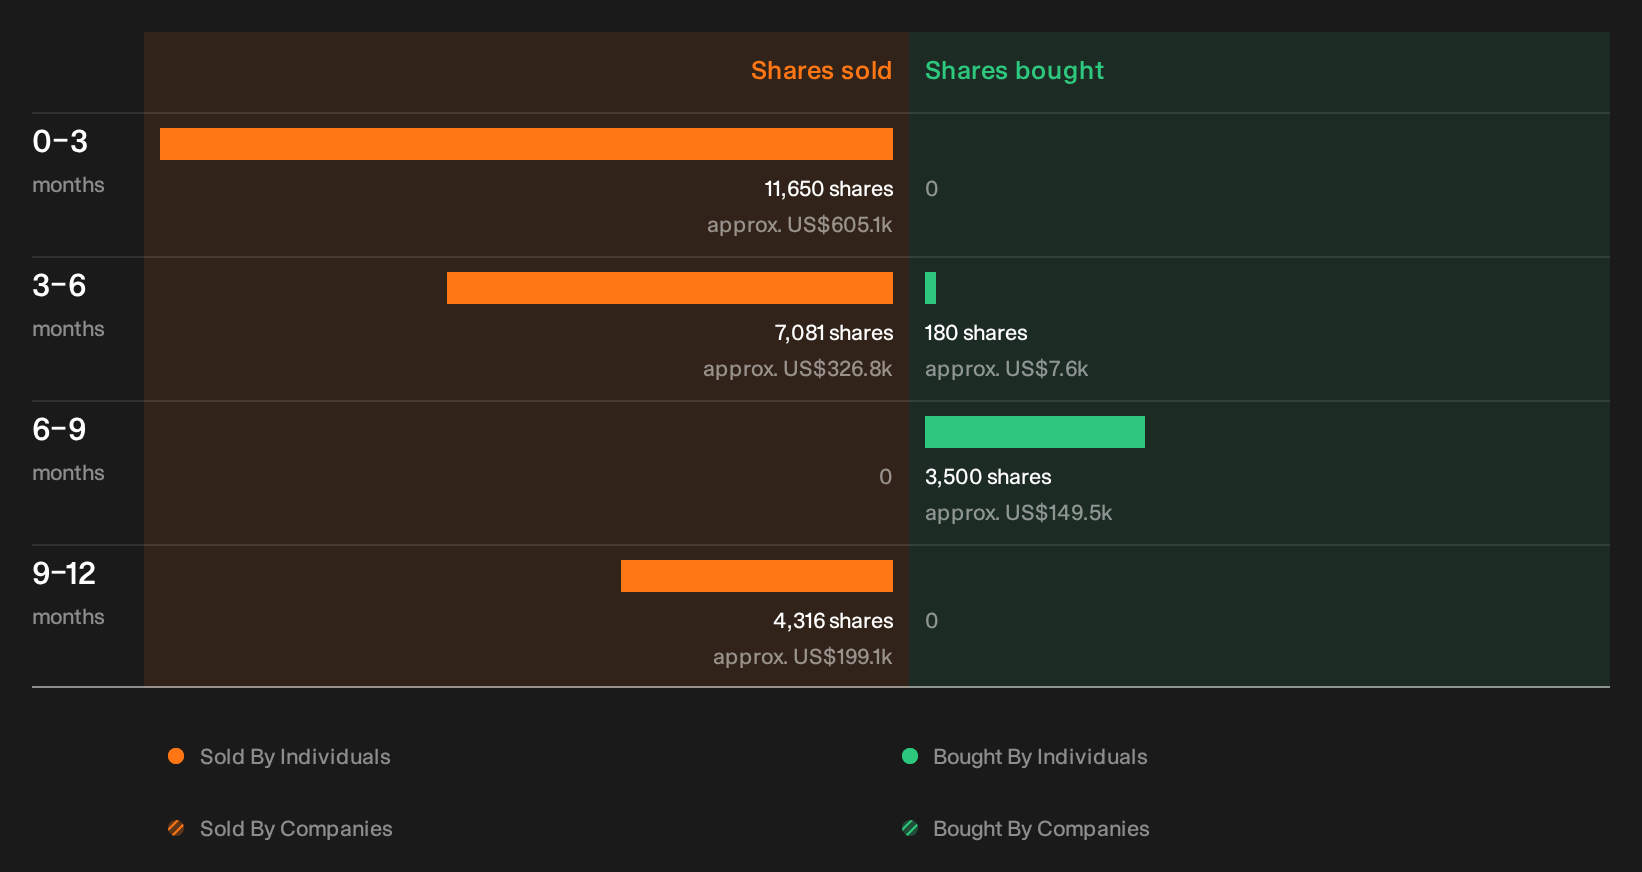
Before forming a full view on Horace Mann Educators, it helps to see what insiders have been doing with their own holdings, including who has been selling and in what amounts. See the recent insider selling flagged for Horace Mann Educators.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com