


Kiniksa Pharmaceuticals International (KNSA) has drawn fresh attention after its recent rebranding from Kiniksa Pharmaceuticals, Ltd. Investors are now weighing what the new identity and international focus might mean for the business.
Recent trading tells a story of strong momentum. Kiniksa Pharmaceuticals International has delivered an 85.69% year-to-date share price return and a 114.70% total shareholder return over the past year. The $78.0 share price sits on top of a very large 5-year total shareholder return that is close to 6x for long-term holders.
Scan beyond Kiniksa Pharmaceuticals International's surge and compare it with a curated 16 high quality undiscovered gems that have strong fundamentals but far less attention on the market radar.
Kiniksa Pharmaceuticals International now carries a market value of about US$6.1b and a US$78 share price built on strong recent gains. The tougher question is whether that reflects fair value or overenthusiasm.
Most Popular Narrative: 20% Undervalued
The most followed valuation story for Kiniksa Pharmaceuticals International pins fair value around $98, above the recent $78 close. This frames the current debate about how much of its pipeline and product potential is already reflected in the share price.
Significant expansion opportunities for ARCALYST remain, as market penetration into the recurrent pericarditis population is still only 15%, with a large additional segment (first recurrence patients) representing another untapped 26,000 patients. This is likely to continue to accelerate topline revenue growth as adoption widens across a growing addressable market due to population aging and rising prevalence of autoimmune/inflammatory disorders.
See why 23 investors see Kiniksa Pharmaceuticals International as 20% undervalued.
Result: Fair Value of $98 (UNDERVALUED)
Still, the story breaks quickly if ARCALYST uptake slows or if KPL-387 stumbles in development. This would challenge the upbeat Kiniksa Pharmaceuticals International narrative.
Find out about the key risks to this Kiniksa Pharmaceuticals International narrative.
Another View: Kiniksa Pharmaceuticals International Looks Expensive On Earnings
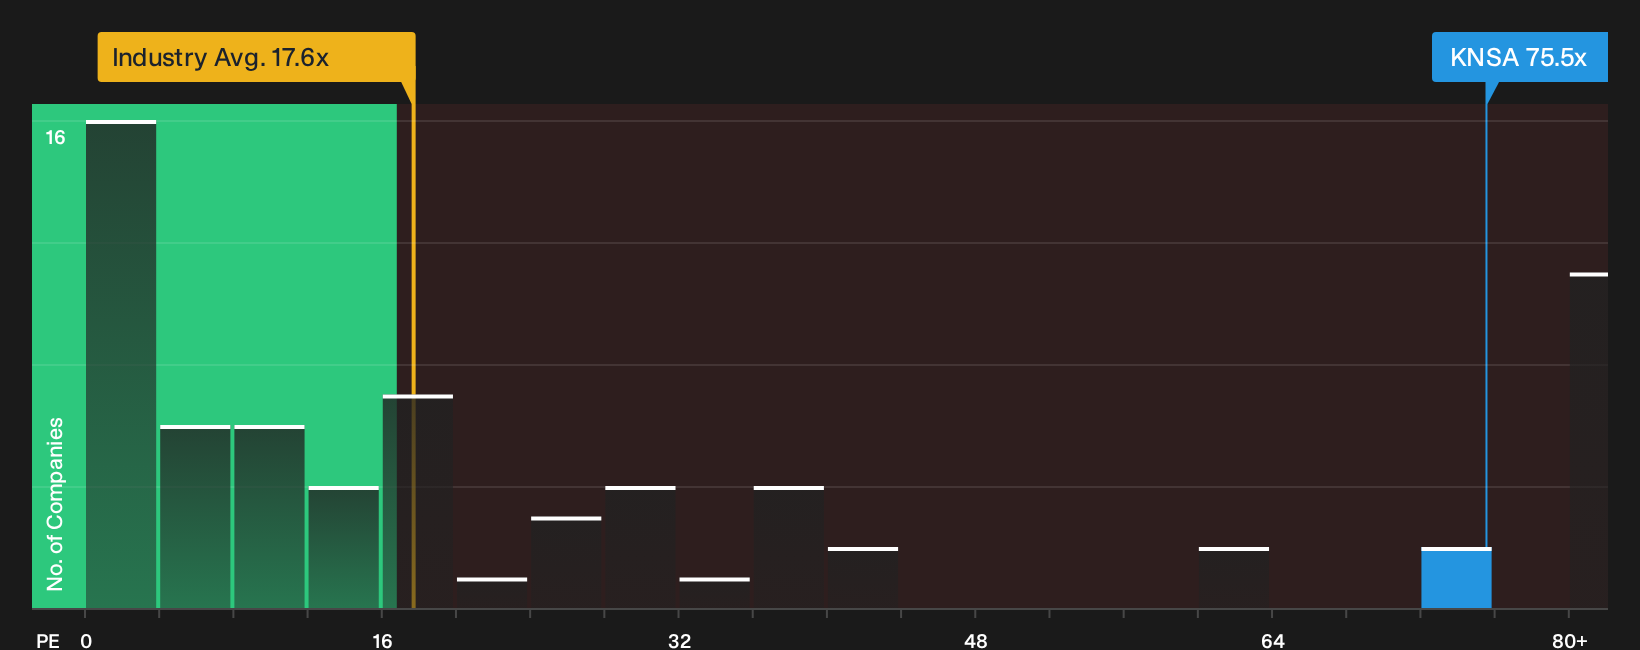
The 20% undervalued story leans heavily on future cash flows and narrative. On a simple P/E check today, Kiniksa Pharmaceuticals International trades on roughly 75.5x earnings, compared with 46.7x for peers and 18.3x for the broader US biotechs group. The fair ratio for KNSA is estimated at 31.7x.
That gap points to a rich valuation on current profits rather than a clear discount. The question for anyone looking at Kiniksa Pharmaceuticals International is whether the future can justify paying more than double the fair ratio and more than four times the wider industry level.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Are you confident that the Kiniksa Pharmaceuticals International story is as straightforward as it appears, or do you believe the risk and reward balance is more complex? Act while the data is fresh and pressure test the upside by reviewing the 4 key rewards.
Looking for more investment ideas beyond Kiniksa Pharmaceuticals International?
If Kiniksa Pharmaceuticals International has sharpened your focus on opportunity and risk, use that momentum to hunt for fresh ideas before they move without you.
- Target dependable upside by reviewing companies that feature a 29 high quality undervalued stocks with stronger fundamentals than their current prices suggest.
- Prioritize resilience by scanning a 30 resilient stocks with low risk scores that may help you keep downside in check while you search for upside.
- Protect your capital first by checking a list of solid balance sheet and fundamentals (23 results) and focus on businesses with healthier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com