


Sanmina has seen its share price climb sharply in recent years, which puts the focus squarely on what investors are paying for its earnings today. With that kind of move in the rear-view mirror, the key issue is whether the current valuation still lines up with the profit engine of the business.
- Over the past 5 years the stock has returned about 445.3%, which raises the question of how much future earnings strength is already built into the price.
- The company’s role as an electronics manufacturing partner means profitability and cash generation hinge on how efficiently it turns complex customer programs into steady earnings, which can affect how much investors are willing to pay for each dollar of profit.
- Your read on Sanmina is one view; the desks covering it have another. See what analysts think Sanmina's shares could be worth.
The stock's next move may depend on whether Sanmina's current share price is well supported by the earnings it is producing today.
If you want to cross-check Sanmina against other opportunities where earnings are a key focus, a good next step is to run a focused screen using 29 high quality undervalued stocks.
Is Sanmina Still Cheap on Earnings?
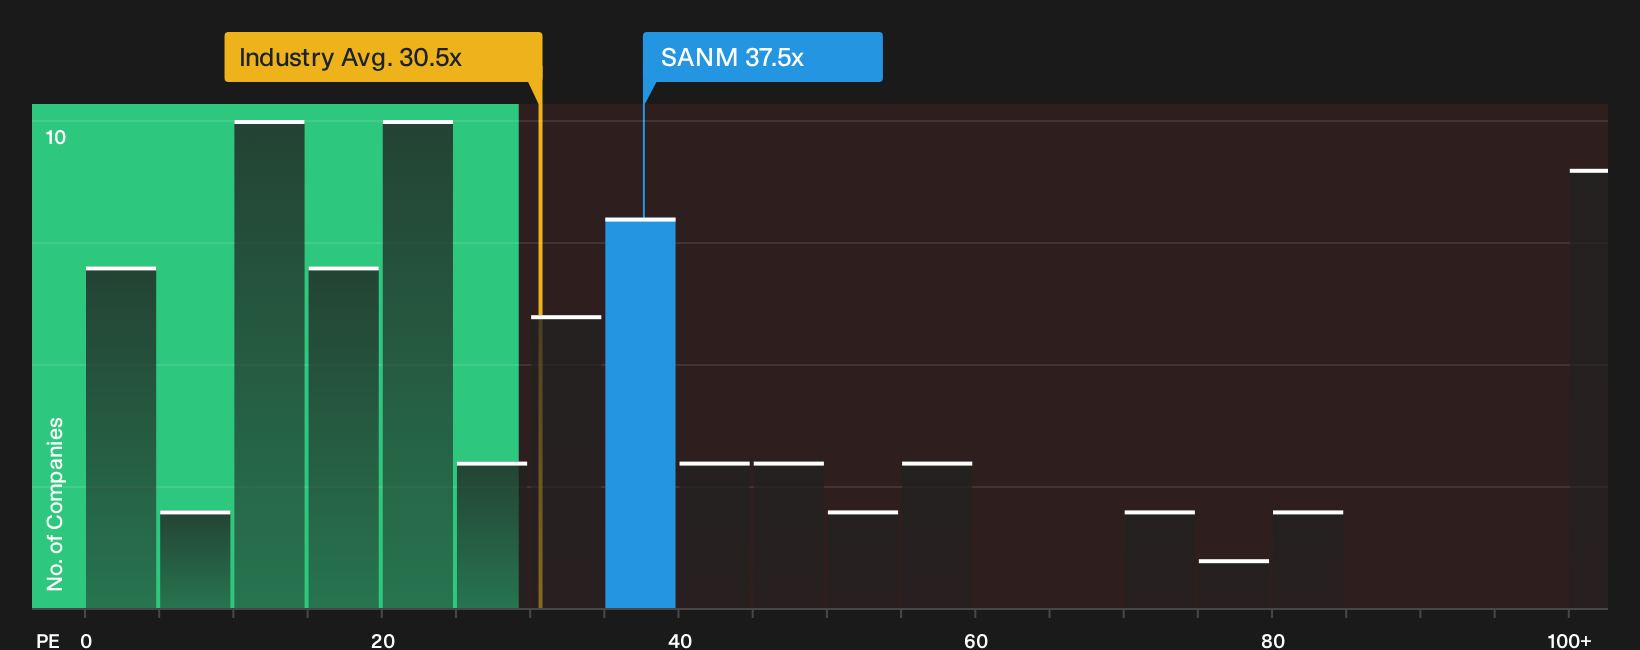
P/E suits Sanmina because earnings are the main yardstick most investors use for a manufacturing partner like this. The stock trades on a P/E of about 37.5x, which is above the Electronic industry average of roughly 30.5x but slightly below the peer group on about 40.7x. That combination suggests the market is willing to pay more for each dollar of profit than for the sector as a whole, while still not assigning the highest multiples in its immediate peer set.
The fair value model points to a P/E that would usually apply to Sanmina given its sector, business economics and risk profile, and the current 37.5x sits below that reference level. For a reader, that means the shares do not look overvalued on this specific metric, even after the strong share price run, although the absolute multiple remains well into premium territory versus the wider industry. Explore the numbers behind Sanmina's P/E valuation.
The Sanmina Narrative: What Would Justify Today's Price?
Sanmina's strong share price move raises a simple question for you as an investor. What future earnings power would need to show up for today's P/E to look either restrained or excessive? Simply Wall St Narratives on the Community page pick up that thread and turn it into specific, testable views on Sanmina's future growth, margins and profitability so you can see how each thesis holds up as fresh information comes through.
Community views on Sanmina split between those who see more upside left in the story and others who think expectations already look full.
Bull case: 17% undervalued
"The imminent acquisition of ZT Systems is expected to add $5–6 billion of annual run-rate revenue, positioning Sanmina to double its net revenue within three years…"
Discover why this Narrative puts Sanmina at 17% undervalued.
Bear case: roughly fairly valued
"Sanmina is increasingly tied to a few very large cloud and AI data center customers through the ZT Systems acquisition…"
Explore why this Narrative puts Sanmina at roughly fairly valued.
One more Sanmina check that belongs beside the valuation work
Price and earnings only tell part of the story for Sanmina, since recent research has also flagged specific risk checks that could change how you weigh everything you have just read. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com