


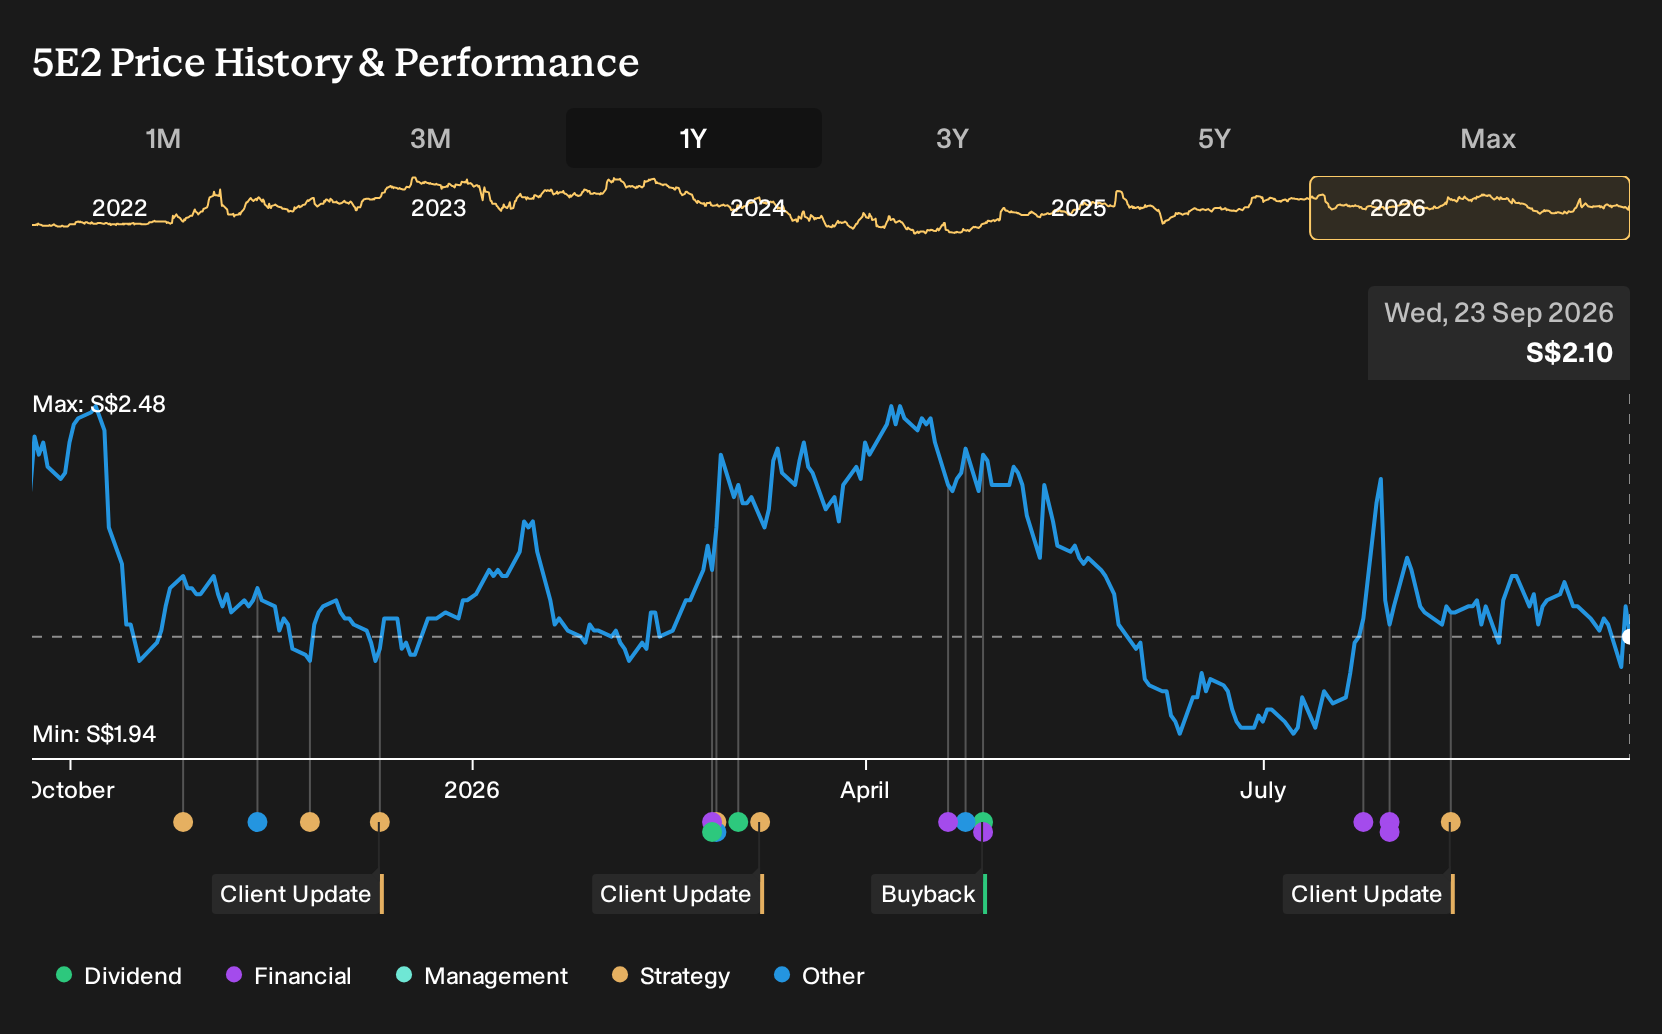
- Seatrium recently announced a new S$200 million share buyback programme, doubling the size of its earlier scheme and allowing repurchases of up to 2% of its issued shares. The buyback is funded from existing cash and remains subject to ongoing shareholder approval at each annual general meeting.
- The enlarged buyback signals that Seatrium is choosing to allocate part of its balance sheet to reducing share count. This may matter for per share metrics as the group pursues energy transition and offshore wind projects alongside its traditional oil and gas work.
- We will now look at how Seatrium's broader investment narrative could be affected by the larger S$200 million buyback commitment.
Scan beyond Seatrium's S$200 million buyback and compare it with hand picked companies returning capital to shareholders through the 162 dividend fortresses.
Seatrium Investment Narrative Recap
Owning Seatrium today means believing the project pipeline in offshore energy, including renewables, can support earnings even as revenue is expected to contract by 8.6% a year over the next three years. The key near term swing factor is execution quality on its large S$18.6b order book and whether recent margin gains, with net margin at 4.7%, can be sustained.
The expanded S$200 million buyback does not change that core thesis. It marginally tightens the share base while operational risks remain around oil and gas cyclicality, Final Investment Decision delays and competition from lower cost yards. Integration progress and cost discipline still matter more than the repurchase itself.
One data point that frames this buyback is Seatrium’s recent earnings performance. Profit grew 108.2% over the past year, helped by a large one off gain of S$255.7 million, and net margin improved from 2.5% to 4.7%. The repurchase programme sits on top of this, using existing cash rather than changing the operational plan.
For you as a shareholder, the interesting tension is between that strong recent profit growth and consensus expectations for slower 2.2% annual earnings expansion and falling revenue. The buyback may slightly improve per share metrics if it is executed, but order intake quality, FPSO and renewables project delivery and margin resilience remain the real catalysts to watch.
Seatrium's current earnings are SGD 552.2 million, and analysts collectively project revenue of SGD 8.8 billion and earnings of SGD 594.3 million by 2029. That outlook assumes revenue declines by 9.0% each year and implies an earnings increase of about SGD 42.1 million from today to the forecast year.
Uncover why Seatrium's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The real swing factor some analysts worry about is order conversion. The most pessimistic group saw Seatrium’s revenue sliding toward about S$6.8b by 2029, with earnings closer to S$418.8 million. That is far below consensus. Opinions clearly diverge, so use this buyback news to recheck which scenario you find more convincing.
Explore 4 other Seatrium fair value estimates, including one that suggests as much as 22% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Seatrium research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Seatrium. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Seatrium's overall financial health at a glance.
Looking for more Seatrium sized investment ideas?
If Seatrium is already on your radar, it can help to line it up against other opportunities and see how it stacks up on income, quality and risk. The Simply Wall St Screener lets you filter the market quickly, so you can spend more time judging the businesses that actually fit your approach.
- For investors who want income to do more of the heavy lifting, compare Seatrium with companies returning cash through reliable payouts using our 162 dividend fortresses.
- If balance sheet strength is non negotiable for you, start with a list of solid balance sheet and fundamentals (198 results).
- Readers hunting for the next potential opportunity off the beaten track can scan a 620 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com