


Honeywell International has dropped sharply year to date, even as it continues to win complex projects across aerospace and defense. That mix of share price weakness and ongoing contract activity puts the focus squarely on one thing for investors: whether the current US$211.85 price tag lines up with what the company earns.
- The stock is down 45.9% year to date, which raises the question of whether the earnings multiple now reflects a reset in expectations or a short term overshoot.
- Recent work on access control for the U.S. Marine Corps and exposure to aircraft lightning protection may support longer term earnings power if these programs translate into durable, higher margin orders.
- There is a second opinion on Honeywell International worth weighing. See what analysts think Honeywell International's shares could be worth.
The stock's next move may depend on whether Honeywell International's current earnings are strong enough to justify where the market is pricing it today.
If you are weighing whether Honeywell International's earnings still justify the US$211.85 price after a 45.9% year to date drop, it can help to see how the theme compares with 40 power grid technology and infrastructure stocks.
Is Honeywell International a Bargain on Earnings?
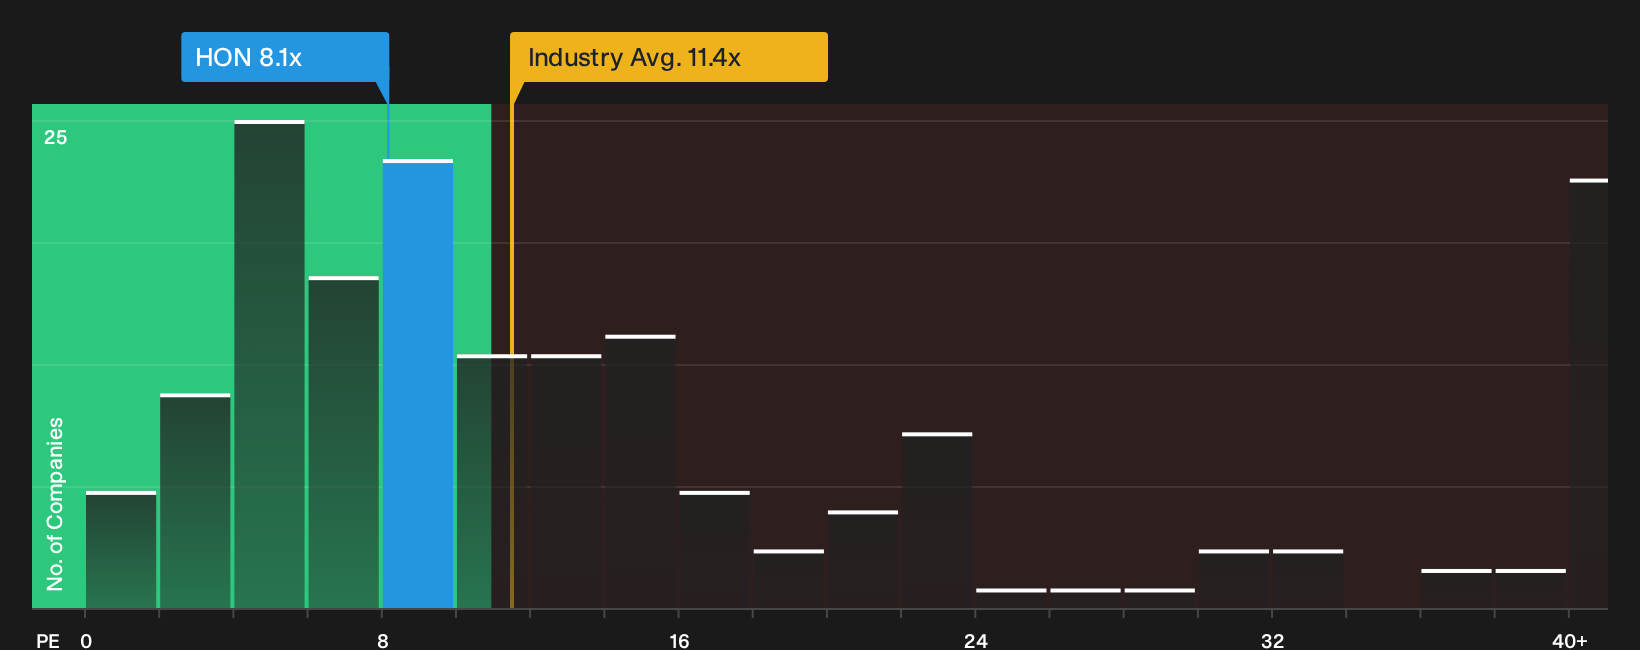
The P/E ratio fits Honeywell International because earnings remain a core way investors frame this kind of diversified industrial group. At a current P/E of 8.1x, the stock is trading well below both the Industrials sector average of 11.4x and the peer set on roughly 34.6x, which points to a sizeable discount on headline earnings.
Because the fair P/E multiple that adjusts for Honeywell International's mix of growth prospects, margins, size and risk screens above today's 8.1x, the market is pricing the shares below what this framework suggests could be justified by its fundamentals. Despite the recent access control wins with the U.S. Marine Corps, that lower multiple indicates investors are still treating the earnings stream cautiously rather than paying up for those contracts. This is the gap you need to weigh when deciding whether the current earnings power of Honeywell International is being fully recognised in the share price. Explore the numbers behind Honeywell International's P/E valuation.
The Honeywell International Narrative: What Would Justify Today's Price?
Narratives for Honeywell International pick up where the valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to play out for the shares to be worth materially more or meaningfully less than the current price, and they sit on Simply Wall St's Community page. Rather than stopping at a single P/E or model outcome, they unpack the future that number rests on so you can watch whether those assumptions actually hold over time.
One of the top community narratives on Honeywell International: 34% undervalued
"Recent shifts in U.S. industrial policy and public-private investment toward quantum computing further reinforce Honeywell’s strategic positioning beyond traditional industrial automation..."
Discover why this Narrative puts Honeywell International at 34% undervalued.
Before acting on Honeywell International's valuation, there is one more factor to check
Honeywell International's pricing story only goes so far without understanding the concerns our research has picked up in the background, and those potential red flags can meaningfully change how you view the whole picture. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com