


Trex Company (TREX) is back in focus after its latest quarterly earnings, where revenue landed at expectations, guidance for the coming quarter pointed higher, and a sharp EPS miss knocked the share price lower.
Trex Company’s recent earnings reaction sits against a choppy backdrop, with the share price up 23.16% year to date but giving back ground over the last quarter as the 90 day share price return declined 9.72% and the 1 year total shareholder return fell 15.54%.
Scan how Trex Company compares to other construction and materials stocks by reviewing a curated set of list of solid balance sheet and fundamentals (23 results)
After a strong year to date run, a weaker 90 day stretch and that earnings-driven pullback leave Trex Company at a crossroads. Does the balance between downside risk and upside potential still appeal at this valuation?
Most Popular Narrative: 19% Undervalued
On the Simply Wall St fair value framework, Trex Company screens as undervalued, with a narrative fair value of $54.67 against a last close of $44.13. That gap rests on a story about steady demand for composite decking, efficiency gains in production, and modestly higher profitability over time.
The ongoing shift in consumer preference toward sustainable, eco-friendly materials is boosting Trex's appeal, as demonstrated by strong demand for its 95% recycled content composite decking and success in taking market share from traditional wood. This should drive long-term revenue growth.
See why 6 investors see Trex Company as 19% undervalued.
In this widely followed narrative, analysts anchor their $54.67 fair value on Trex Company growing revenue at roughly 6.6% a year, lifting profit margins from 14.7% to around 16.0%, and applying a future P/E of 26.0x while using an 8.61% discount rate. Those inputs sit above the current building industry P/E of 21.3x, so the story assumes investors will continue to pay a premium for composite decking exposure and improved earnings quality.
The same view also points to share count declining by just over 5% a year for the next three years, which supports per share earnings, while still flagging softer repair and remodel demand, elevated capital spending, and heavy reliance on decking and railing as key swing factors for the thesis.
Result: Fair Value of $54.67 (UNDERVALUED)
Still, Trex Company’s reliance on decking and railing, together with softer repair and remodel demand, could pressure revenue expectations and challenge the current undervaluation narrative.
Find out about the key risks to this Trex Company narrative.
Another View: Trex Company Through The P/E Lens
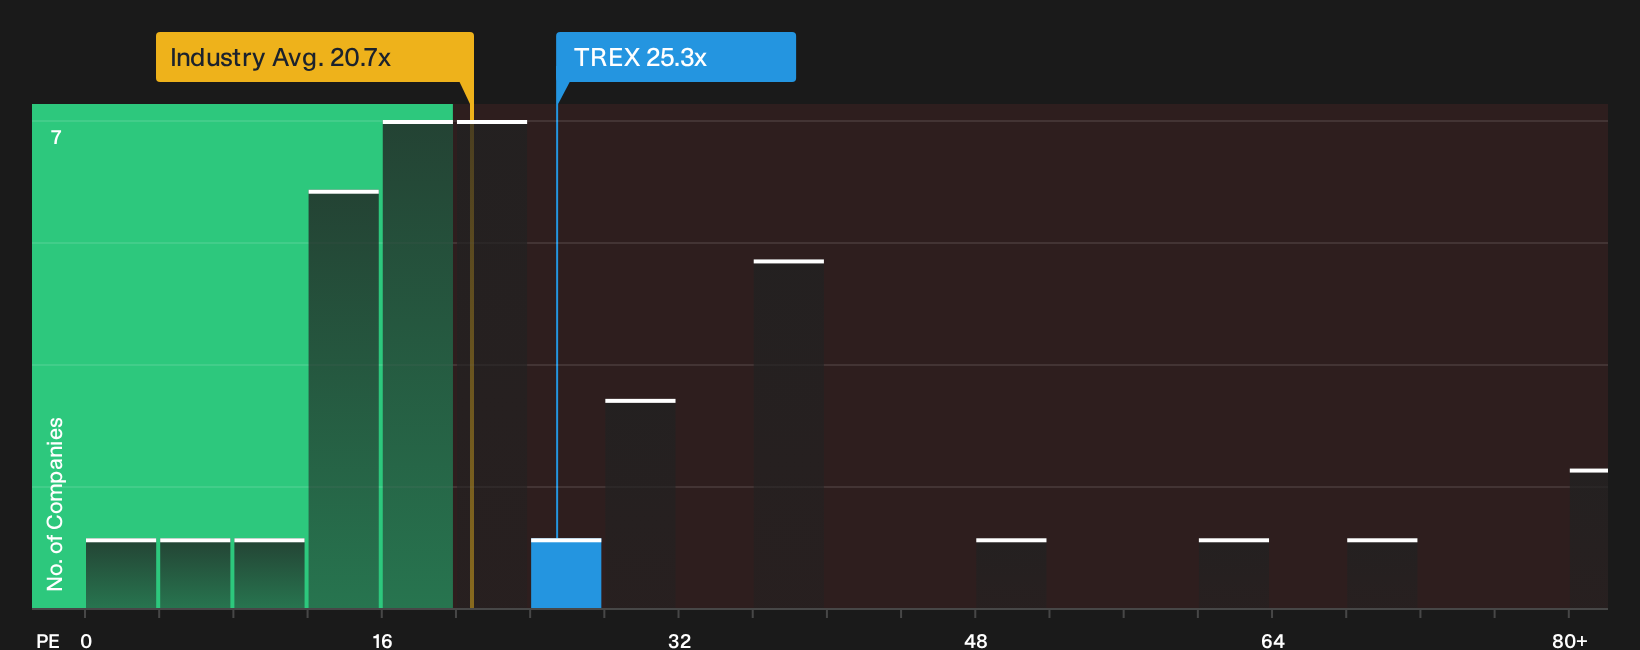
A different lens on Trex Company comes from its P/E ratio. The stock trades on 25.3x earnings, compared with 20.2x for the broader US Building group and a fair ratio estimate of 22.5x. That premium suggests investors are already paying up, which raises the risk that any disappointment on execution or end demand could hit the share price harder than the fair value narrative implies.
See what the numbers say about this price in our valuation breakdown by reviewing the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the Trex Company story skews more bullish or cautious overall? Act while the latest earnings and valuation data are fresh, then pressure test the optimism using the 3 key rewards.
Looking For More Investment Ideas Beyond Trex Company?
If Trex Company has your attention, do not stop with a single ticker. Broaden your watchlist now so you are not late to the next setup.
- Target dependable cash generators by scanning a 7 dividend fortresses that focuses on higher yield payouts backed by solid fundamentals.
- Hunt for quality at a discount by reviewing a curated 29 high quality undervalued stocks list where strong businesses trade at valuations that may look appealing.
- Zero in on sturdier balance sheets by running a 30 resilient stocks with low risk scores filter that highlights companies with lower risk profiles and resilient financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com