


Teleflex (TFX) is back on watch after fresh performance data showed annual revenue of US$2.25b alongside a reported net loss of US$25.05m. This has sharpened investor focus on profitability and product mix resilience.
The Teleflex share price sits at US$124.90 after a 30-day share price return that is down 10.03%, with shorter term moves also under pressure and hinting at fading momentum despite a slightly positive year-to-date share price return of 2.04% and a 1-year total shareholder return of 3.42%. Over longer horizons the picture is tougher, with the 3-year total shareholder return down 35.83% and the 5-year total shareholder return down 66.53%. This keeps recent revenue headlines squarely in the context of a stock where investors have already absorbed a lot of pain and may now be reassessing both risk and potential recovery.
Compare Teleflex's reset with a curated group of resilient healthcare peers by scanning the 37 healthcare AI stocks that are already attracting fresh attention.
Bulls point to Teleflex’s revenue base and valuation gap, while bears fixate on the recent net loss and long term share price damage. Which side do the current numbers lean toward as you weigh what the stock may be worth?
Most Popular Narrative: 19% Undervalued
Teleflex is framed by the most followed narrative as trading below a fair value of $153.55 compared with the last close at $124.90. This puts the focus squarely on whether margin repair and capital deployment can justify that gap under an 8.35% discount rate.
The recent acquisition of BIOTRONIK's Vascular Intervention business is expected to drive sustainable revenue growth of 6% or better annually beginning in 2026 and provide near-term EPS accretion by expanding Teleflex's presence in the high-growth interventional cardiology and endovascular procedures market. Improved access to the cath lab and cross-selling opportunities are likely to boost topline revenue and margins.
See why 8 investors see Teleflex as 19% undervalued.
Result: Fair Value of $153.55 (UNDERVALUED)
Still, the Teleflex story can break if UroLift weakness drags on or if BIOTRONIK integration problems keep margins and earnings below current analyst assumptions.
Find out about the key risks to this Teleflex narrative.
Another View on Teleflex Valuation
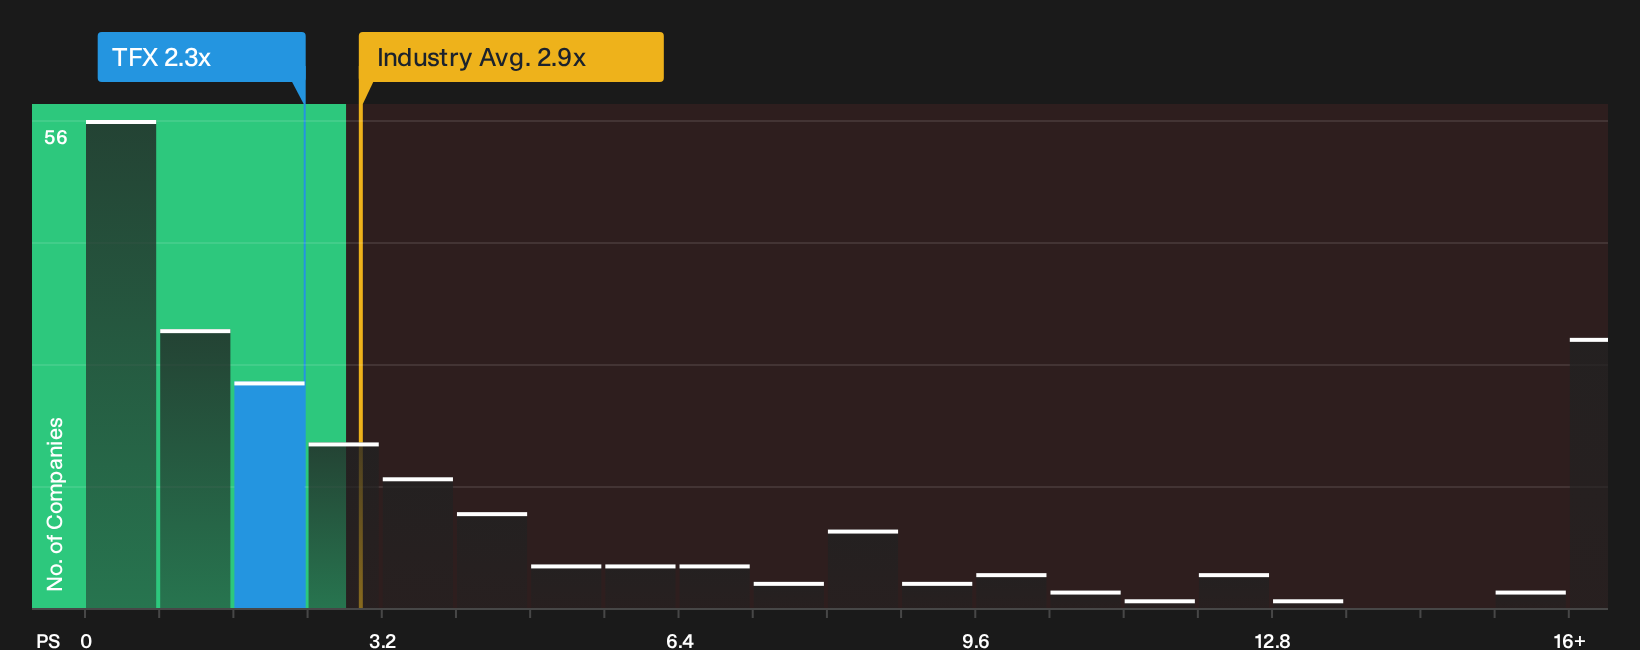
Teleflex screens very differently once you shift from the analyst fair value narrative to the price to sales lens. The stock trades on a P/S of 2.3x, above a fair ratio of 2.1x and above close peers on 1.9x, yet below the broader US Medical Equipment group at 2.9x. That mix points to some valuation risk if investor attention shifts from long term cash flow recovery toward nearer term revenue multiples.
Our P/S based fair ratio work incorporates both peer averages and Teleflex specific fundamentals, which can highlight where sentiment or expectations may be running ahead of the underlying sales base. For a deeper look at how this ratio based view compares with the rest of the toolkit, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Teleflex is clearly mixed, with meaningful worries sitting right beside real upside arguments, so it makes sense to review the evidence yourself and move quickly while the picture is fresh by weighing up the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Teleflex?
If Teleflex has you rethinking your watchlist, use this moment to refresh your broader opportunity set with a few focused screeners built around quality and risk.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio.
- Hunt for potential value opportunities by scanning the 29 high quality undervalued stocks before other investors start paying closer attention.
- Prioritize stability and capital preservation by checking the 30 resilient stocks with low risk scores so you are not the last to react when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com