


- Industria de Diseño Textil has committed to a significant logistics investment program and a wider in-store technology rollout, targeting more scalable distribution and leaner day-to-day operations across its global retail network.
- The push to integrate tools such as soft tags and self-checkout terminals signals a direct attempt to tighten cost control while keeping the in-store experience fast and consistent across regions.
- We will now see how Industria de Diseño Textil’s logistics expansion and store technology push could reshape its broader investment narrative.
Scan list of solid balance sheet and fundamentals (198 results), which is built around retailers like Industria de Diseño Textil that are leaning on logistics and in-store tech to keep operations efficient as conditions change.
Industria de Diseño Textil Investment Narrative Recap
To own Industria de Diseño Textil, you need to believe its mix of global reach, tight operations and strong brands can keep turning scale into healthy profitability. The current logistics and in store tech push fits that story by aiming to keep stores productive and online demand flowing efficiently, even as store traffic and fashion cycles remain unpredictable.
The key near term swing factor is execution on that logistics expansion without letting the planned €1.8b in 2025 capex squeeze free cash flow too hard. The biggest risk still sits with external pressures, particularly FX headwinds, tariffs and the inventory position, which already sits about 12% above the prior year.
The most relevant recent update is the commitment to expand logistics capacity while rolling out tools such as soft tags and self checkout. This directly touches the core thesis for Industria de Diseño Textil, that better distribution and faster store processes can help protect net profit margins even when revenue growth is relatively modest.
For you as a shareholder, the operational story now hinges on whether these projects genuinely lower unit costs and keep stock moving cleanly across regions. Any stumble in inventory discipline or capital allocation would matter more, given earnings growth is expected to be steady rather than rapid and the P/E multiple already screens above the wider European specialty retail group.
What The Current Forecasts Assume For Industria de Diseño Textil
Analyst expectations around Industria de Diseño Textil put hard numbers behind the logistics build out and in store tech push that management is funding. The consensus view assumes revenue rising at 7.4% a year over the next three years, with profit margins shifting from 15.6% today to 16.5% by around 2029 if everything goes to plan.
On earnings, the analyst group projects profit of €8.3b by 2029, compared with about €6.3b today. That is an increase of roughly €2.0b in absolute terms, and it underpins the idea that more efficient distribution and faster store processes can add incremental profitability even if trading conditions stay mixed from year to year.
Valuation work in the consensus report links those earnings projections to a price tag through the P/E multiple. To reach their price target framework, Industria de Diseño Textil would need to support a P/E of 29.4x on those 2029 earnings, compared with about 28.4x on current numbers and against an industry reference near 21.4x. In simple terms, the market would be paying a higher multiple than the broader GB specialty retail group if these forecasts play out.
On the revenue line, the same models point to top line of around €50.0b in 2029 paired with the €8.3b profit figure. Those two numbers together imply that analysts are banking not only on steady expansion in sales but also on operational tweaks like logistics upgrades and soft tags feeding through into a slightly richer profit margin profile over time.
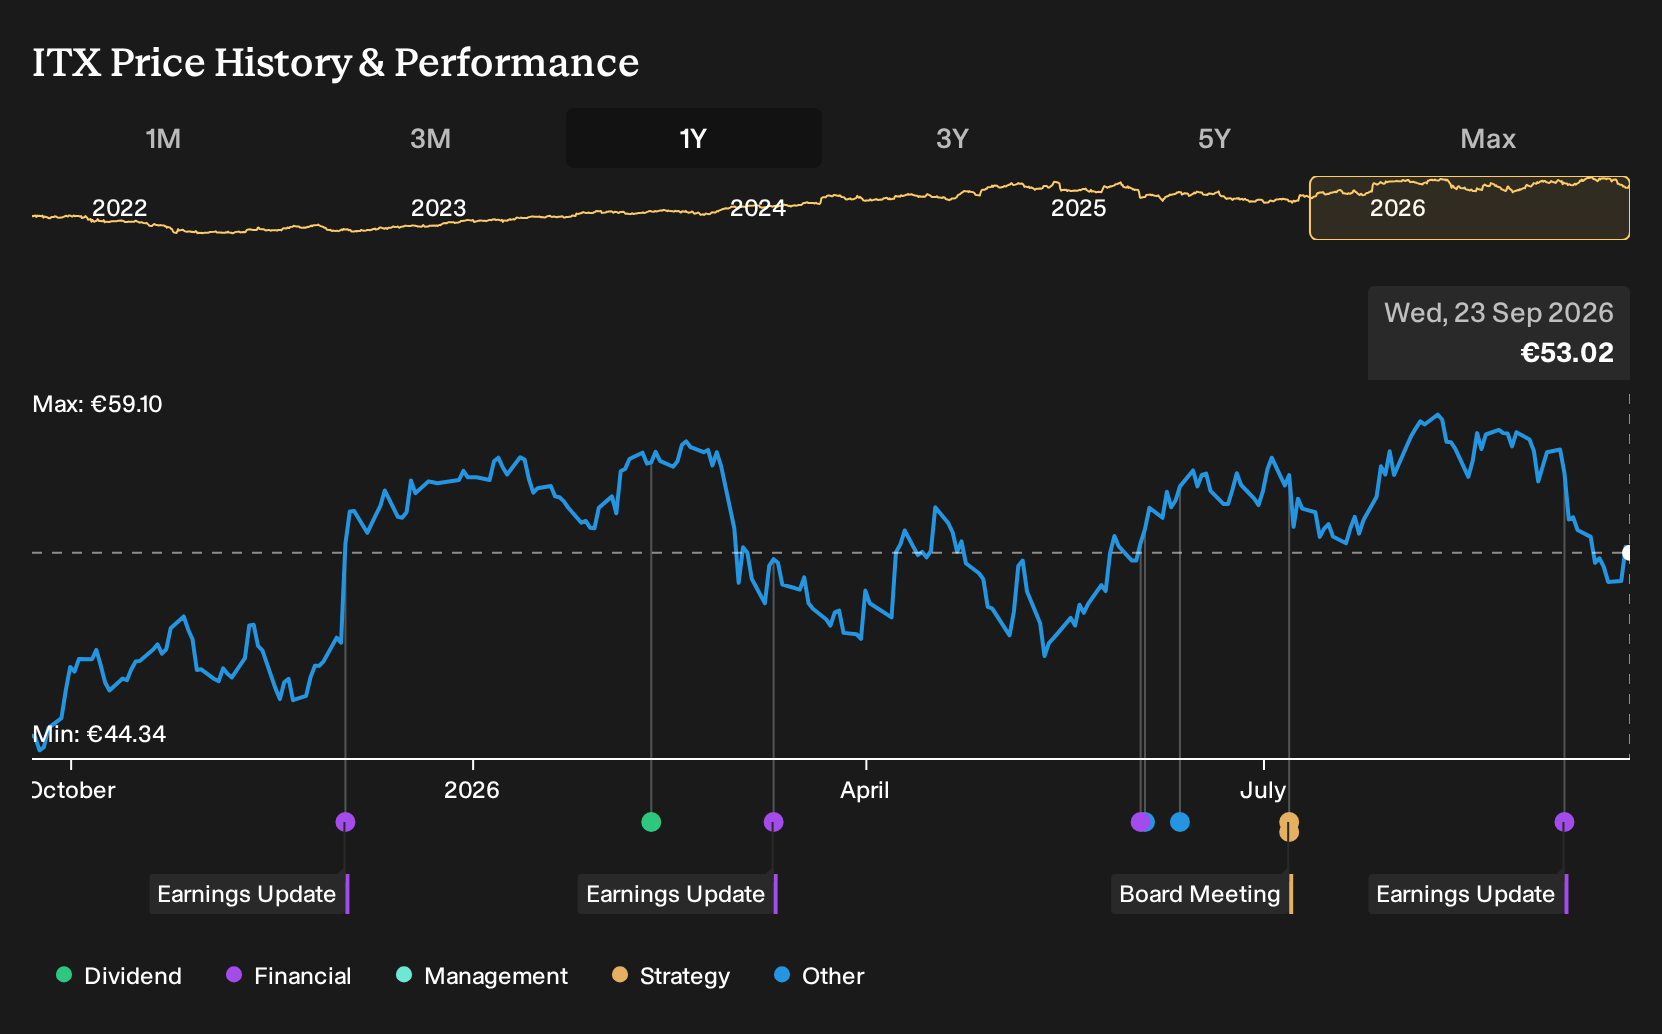
The Industria de Diseño Textil share price already reflects a lot of this work. At €57.44, it sits only about 4.9% below the consensus price target of €60.38, with individual analyst views running from €41.50 to €67.00. For you as an investor, that narrow gap suggests the market is already pricing the logistics and tech program as reasonably likely, which raises the bar on execution and leaves less room for disappointment if capex or inventory decisions misfire.
Industria de Diseño Textil's narrative projects €50.0b revenue and €8.3b earnings by 2029. This requires 7.4% yearly revenue growth and an earnings increase of about €2.0b from €6.3b today.
Uncover why Industria de Diseño Textil's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Industria de Diseño Textil from four Simply Wall St Community members span roughly €46 to just over €60, so retail views already cover a wide valuation band. When you set that against currency, tariff and inventory risks, it serves as a reminder that opinions differ sharply. Explore those competing narratives before deciding how you feel.
Explore 3 other Industria de Diseño Textil fair value estimates, including one that suggests as much as 13% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your Industria de Diseño Textil research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Industria de Diseño Textil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Industria de Diseño Textil's overall financial health at a glance.
Looking For More Investment Ideas Beyond Industria de Diseño Textil?
Once you have a view on Industria de Diseño Textil, it often helps to compare it with a wider pool of businesses that match the kind of balance sheet strength, valuation profile or income stream you are looking for. The Simply Wall St Screener can help you do that quickly by filtering companies using the same fundamentals that matter to you.
- If capital preservation matters most to you, focus on resilience first and then use the 229 resilient stocks with low risk scores to find stocks that fit a lower risk profile.
- If you prefer dependable cash dividends as part of your return, scan the 161 dividend fortresses to see which companies offer higher yields with supporting fundamentals.
- If you want to back quality that is not widely followed, search through the 620 high quality undiscovered gems and spot lesser known businesses with stronger numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com