


- Myers Industries reported Q2 2026 results with revenue from continuing operations up 9.8% year over year, a 300 basis point gross margin gain, a 520 basis point operating margin improvement, and extended debt maturities to 2031 following a refinancing completed earlier this year.
- The quarter showed how the Focused Transformation program can translate into higher profitability and a stronger balance sheet at the same time, which matters for investors tracking both earnings quality and financial flexibility.
- We will now explore how Myers Industries' sharper margins and extended debt runway could reshape the longer term investment narrative.
Scan how Myers Industries' margin and balance sheet reset compares with other financially resilient companies by reviewing our hand picked 30 resilient stocks with low risk scores.
Myers Industries Investment Narrative Recap
For Myers Industries, the long term belief is that a tighter focus on higher value material handling and infrastructure solutions can support solid profitability even if some end markets stay sluggish. The recent Q2 2026 report, with revenue from continuing operations up 9.8% and sharper margins, points to better execution of that plan rather than a new story.
In the near term, the key swing factor is whether this margin structure holds if automotive and vehicle aftermarket demand stays weak or worsens. The biggest risk still sits in those softer core markets and the potential revenue impact from any Myers Tire Supply divestiture. The latest quarter improves confidence in execution, but does not remove those pressures.
The refinancing that pushed Myers Industries' debt maturities out to 2031 feels especially relevant here. Longer dated obligations reduce near term refinancing pressure and give the business more room to run its Focused Transformation program without constant balance sheet noise. For a company flagged as having a high level of debt, extra runway matters.
That extended debt profile also interacts with the key catalysts investors often watch. If Myers keeps driving efficiency from facility consolidation and SG&A cuts while industrial and infrastructure backlogs convert, the current leverage structure may look more manageable. If revenue softness reappears instead, the same debt load could quickly move back to the front of the risk list.
Myers Industries' current analyst narrative points to revenues of $646.8 million and earnings of $90.4 million by 2029, implying a 7.9% yearly revenue decline and an earnings increase of about 2.2x from $41.5 million today.
Uncover why Myers Industries' fair value indicates a 17% potential upside to its current price, which investors may see materialize sooner than expected.
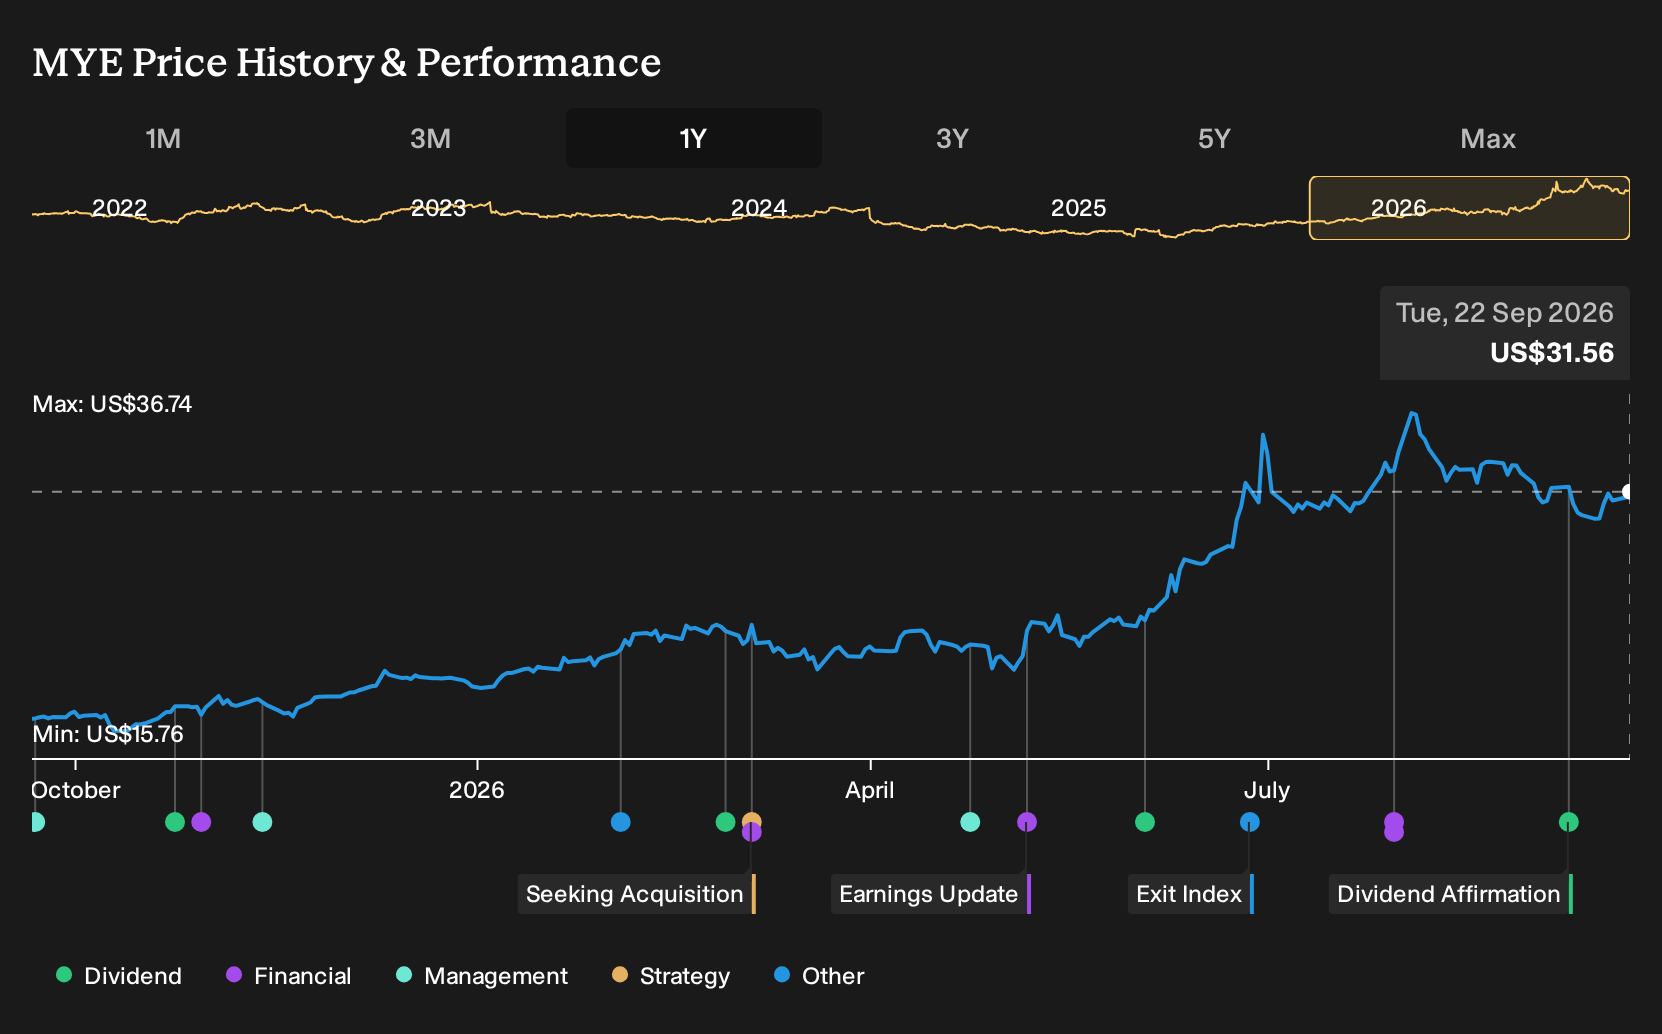
Exploring Other Perspectives
The two fair value views from the Simply Wall St Community span from US$37 to about US$105 per share, which is a huge gap for Myers Industries. That divergence sits beside real-world swing factors such as potential weakness in automotive demand and any divestiture of Myers Tire Supply. You can explore how different investors weigh those moving parts and reach very different conclusions.
Explore another Myers Industries fair value estimate, including one estimate that suggests it could be worth just $37.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Myers Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Myers Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Myers Industries' overall financial health at a glance.
Looking for more investment ideas beyond Myers Industries?
Once you have a handle on Myers Industries, it can help to compare its profile with other listed businesses that match the kind of risk and return trade off you are comfortable with.
- If you want income to play a bigger role in your returns, you can scan higher yielding companies through the 7 dividend fortresses.
- If upside potential is your focus, you can see which financially robust businesses trade below their estimated value by reviewing the 29 high quality undervalued stocks.
- If capital preservation matters most, you can narrow your watchlist to companies with stronger balance sheets by starting with the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com