


Havas (ENXTAM:HAVAS) has been back in the market buying its own shares. The group reported repurchases tied to its €50 million buyback plan, including 5,000 shares acquired between September 14 and 18, 2026.
Recent trading has been softer, with the share price down 5.33% over the past month, even after a 5.34% 90 day share price return. The 1 year total shareholder return of 20.43% points to momentum that has been building over a longer stretch.
Scan how Havas compares with other media and communications groups by reviewing our curated list of 620 high quality undiscovered gems that may still be flying under most investors' radar.
Havas is putting real money behind its own equity through buybacks while the share price has cooled in recent weeks. That combination raises the obvious question: Is the business quality already fully in the price today?
Price-to-Earnings of 8.7x: Is it justified?
Havas trades on a P/E of 8.7x, with the shares at €17.75 at the last close, while the business screens as good value against both peers and its own history of profit growth.
The P/E ratio links what investors are willing to pay today with the earnings the group is currently producing. For a communications and marketing group like Havas, where profit quality is described as high and earnings have been growing, this measure gives a simple way to compare expectations for future profitability with the current share price.
Havas is assessed as good value on this 8.7x P/E against the European Media industry average of 15x. It is also compared favorably to an estimated fair P/E of 16.3x. That gap is wide, so the market is currently pricing the stock at a level that is well below both sector peers and the fair ratio the SWS model suggests it could move toward over time.
Explore the SWS fair ratio for Havas.
Result: Price-to-Earnings of 8.7x (UNDERVALUED)
Still, the recent 5.33% share price decline and modest 0.5% annual revenue growth leave room for disappointment if Havas struggles to convert earnings strength into sustained top line progress.
Find out about the key risks to this Havas narrative.
Another view on Havas using our DCF model
The P/E points to value, but the SWS DCF model goes even further. On this view, Havas at €17.75 is trading at a 55.1% discount to an estimated future cash flow value of €39.57. If both signals are right, a gap of that size may be noteworthy for investors.
Look into how the SWS DCF model arrives at its fair value.
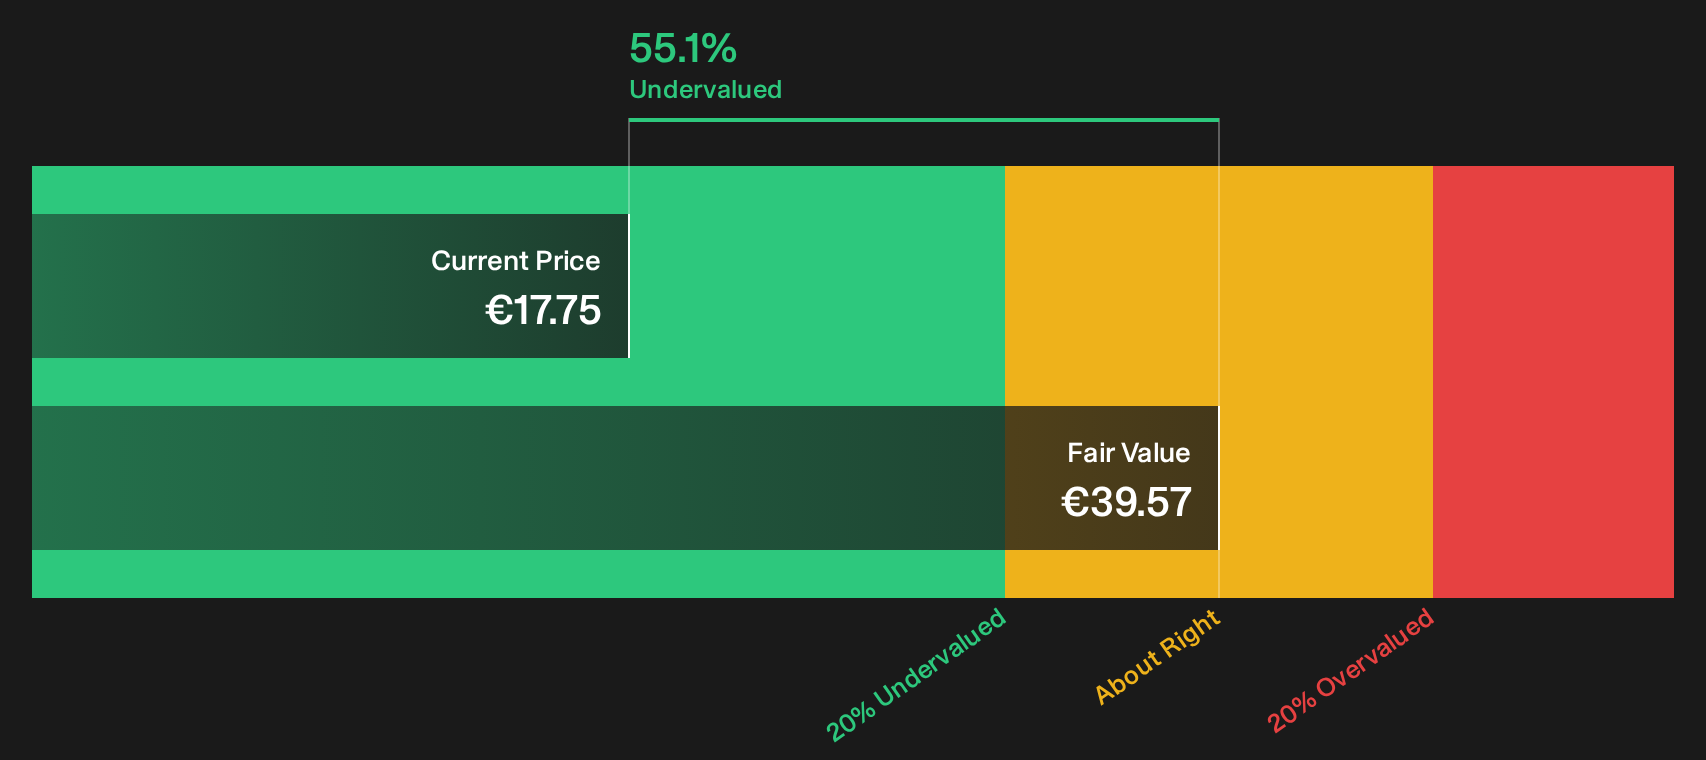
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Havas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether this cautious optimism around Havas fits your own view of the business? Look through the numbers yourself, then check the 5 key rewards
Looking for more Havas-sized investment ideas?
Do not stop your research with Havas. Use the Simply Wall Street Screener to spot other opportunities that fit different goals before the crowd reacts.
- Target potential mispricing by scanning companies that screen as strong value using the 173 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (198 results) for businesses that may better handle financial stress.
- Increase your income focus by lining up candidates in the 161 dividend fortresses that offer higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com