


- McDonald's announced a multi year McDonald's > NEXT plan, committing up to US$8.5b through 2036 to help franchisees modernize restaurants, install AI driven systems like ArchIQ and upgrade equipment, while also raising its quarterly dividend to US$1.93 per share, equivalent to US$7.72 annually.
- The same package of remodels, tech deployment and menu upgrades is expected to lift restaurant level efficiency and cash flow, yet it lands just as U.S. traffic softens and comparable sales slow, which puts execution risk and timing of payback at the center of McDonald's operating story.
- We will now examine how McDonald's long term NEXT spending plan, especially the US$8.5b franchisee support, reshapes its investment narrative.
Compare McDonald's NEXT reset with other potential turnaround stories by scanning our hand picked 29 high quality undervalued stocks that pair solid fundamentals with cautious market expectations.
McDonald's Investment Narrative Recap
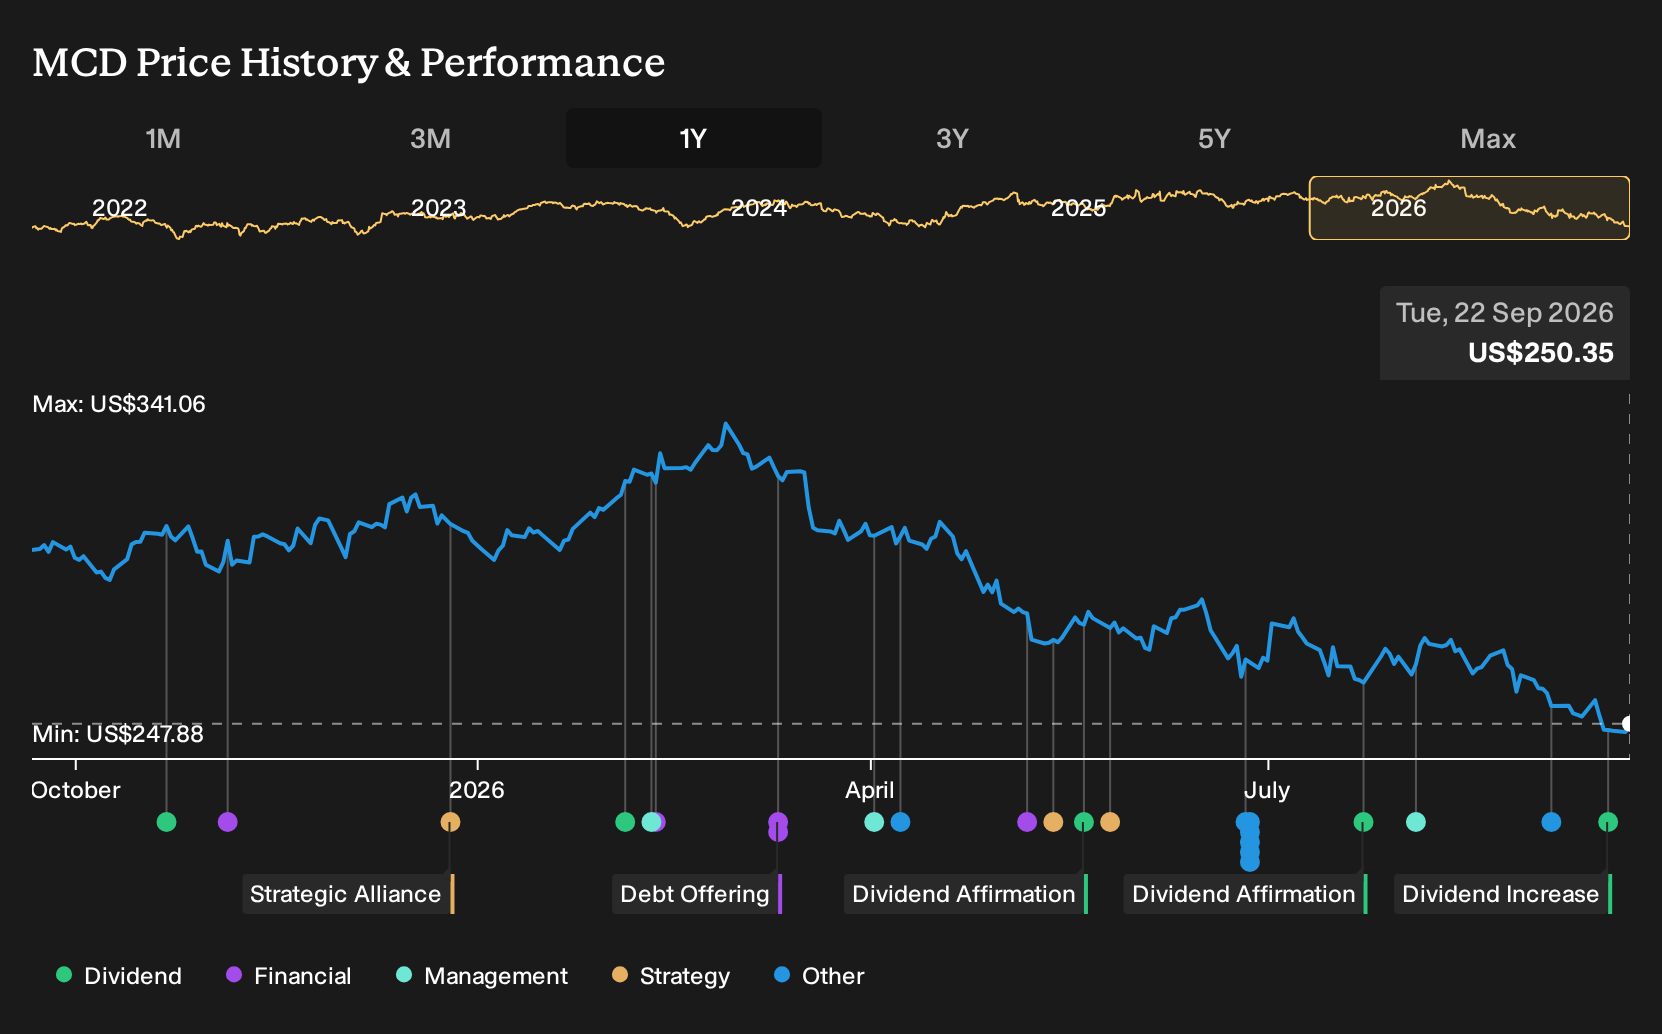
To stay invested in McDonald's, you need to be comfortable with a reset story. The business is leaning into its McDonald's > NEXT plan, putting up to US$8.5b behind franchisee upgrades and AI led operations while U.S. traffic is under pressure and the share price is near a 52 week low. The key short term catalyst is whether these changes start to stabilise guest counts and same store sales.
The biggest near term risk is that lower income traffic remains soft, so value messaging and consistent execution on deals matter more than usual. The dividend increase to US$1.93 per quarter signals confidence in recurring cash flow, although it does not change the immediate challenge around weaker U.S. growth and industry wide cost inflation.
The most relevant recent announcement is the McDonald's > NEXT investment and franchisee support package. Management plans to commit about US$8.5b through 2036, including rent relief and capital support, to fund modernised kitchens, ArchIQ deployment and restaurant redesigns, with a targeted 250 basis point improvement in restaurant efficiency and roughly US$100,000 in added annual cash flow per average U.S. location.
For you, the question is whether execution on this program becomes a visible catalyst before cost pressure and soft traffic do more damage. Rolling AI systems across thousands of outlets, revamping menus and retraining roughly 2 million employees introduces real operational risk. Progress on digital engagement, value menus and U.S. guest counts will likely be the clearest early markers of whether the NEXT plan is on track or slipping.
What The McDonald's Consensus Is Pricing In
McDonald's narrative projects US$31.5b revenue and US$10.6b earnings by 2029. This implies revenue growing at about 4.3% per year and an earnings increase of roughly US$1.8b from the current US$8.8b base.
Uncover how McDonald's fair value indicates a 31% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
There are 9 fair value views from the Simply Wall St Community, ranging from about US$234 at the low end to roughly US$312 at the top, so private investors are clearly not aligned on what McDonald's is worth. Some focus on risks such as softer U.S. traffic and inflation squeezing margins. Others emphasize potential catalysts including digital loyalty, value menus and the 10 year NEXT investment. Use that spread as a prompt to inspect several of these perspectives yourself.
Explore 8 other McDonald's fair value estimates, including one that suggests as much as 31% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your McDonald's research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for McDonald's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McDonald's overall financial health at a glance.
Looking For More Ideas Beyond McDonald's?
Once you have a view on McDonald's and its NEXT plan, it can help to set that against a wider watchlist of companies with very different drivers and risk profiles. The Simply Wall St Screener gives you a fast way to surface a few focused starting points that match what you care about most.
- If resilience and lower volatility matter to you right now, start with a curated set of 30 resilient stocks with low risk scores that aim to keep business and balance sheet risk contained.
- If you prefer dependable cash generation and income, scan a hand picked group of 7 dividend fortresses that pair higher yields with durable fundamentals.
- If you are hunting for under the radar opportunities, review a focused pool of 16 high quality undiscovered gems where fundamentals look solid but market attention remains limited.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com