


Hamilton Insurance Group has delivered a strong share price run over the past year, which naturally raises a question for anyone looking at the stock. Are investors now paying a price that is fully explained by the company’s current earnings power, or has sentiment moved ahead of what the business is actually generating?
- The share price is up 45.8% over the past year, which puts real weight on whether the current earnings base can carry that kind of re-rating.
- As a specialty insurer and reinsurer, Hamilton Insurance Group’s ability to price risk, control underwriting costs and convert premiums into steady profits may support or constrain what investors are prepared to pay for its earnings.
- There is a second opinion on Hamilton Insurance Group worth weighing. See what analysts think Hamilton Insurance Group's shares could be worth.
The issue now is whether Hamilton Insurance Group’s current earnings justify today’s share price or whether expectations have started to stretch beyond what the business is delivering.
If you are weighing whether Hamilton Insurance Group’s 45.8% one year return is fully backed by its earnings, it can help to compare it against a wider set of 29 high quality undervalued stocks.
Does Hamilton Insurance Group Look Undervalued on Earnings?
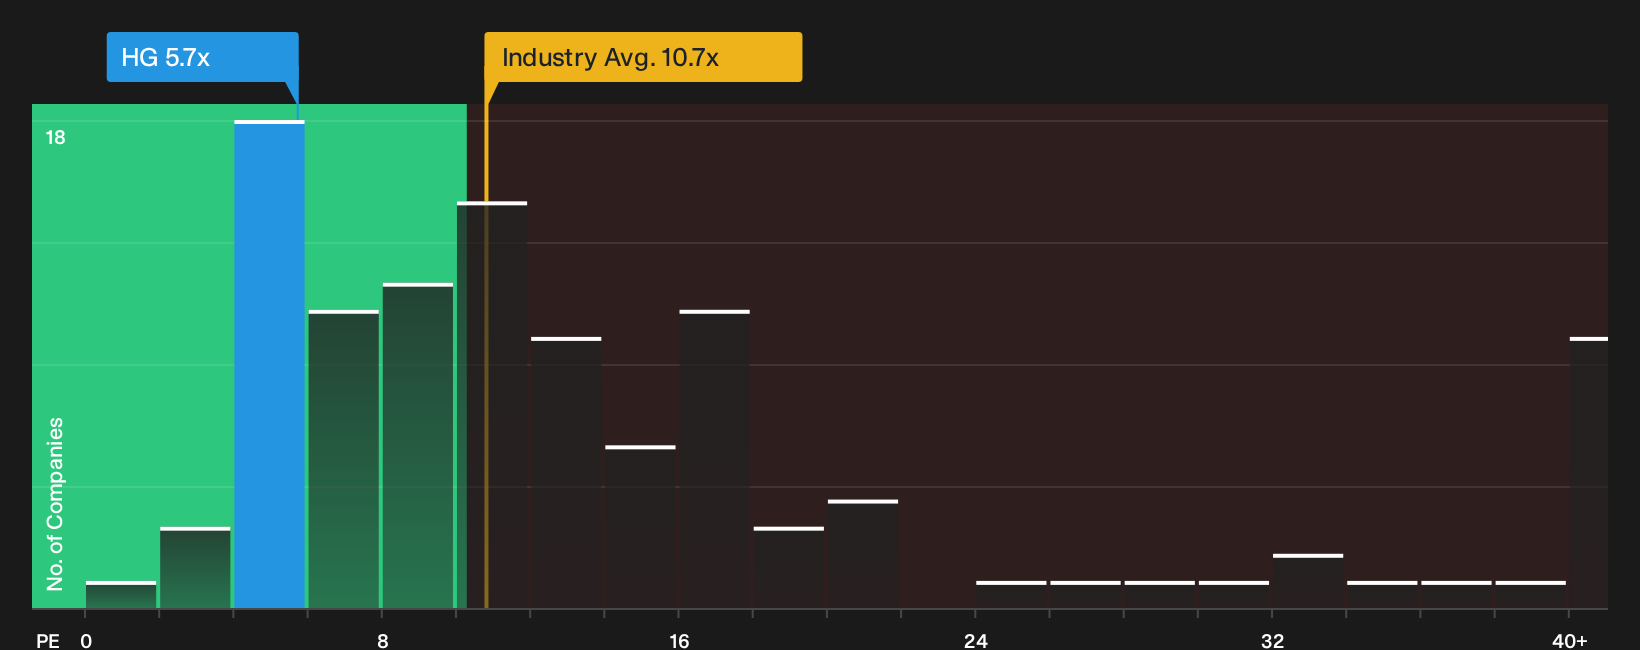
P/E works well for Hamilton Insurance Group because earnings are a central yardstick for insurers whose business model revolves around underwriting profit and investment income. On this measure, the stock trades on a P/E of about 5.6x, which is roughly half the Insurance sector average of 10.7x and also well below the peer group on about 10.3x. For a reader comparing options inside the same industry, that kind of gap is hard to ignore.
The fair multiple implied by Hamilton Insurance Group’s own economics is higher than where the shares trade today, so the current P/E sits on the discounted side of that benchmark rather than the expensive side. The market is therefore pricing each dollar of Hamilton Insurance Group earnings more cautiously than both the sector and the tailored model suggest, which leaves you weighing whether that gap reflects perceived risk or a potential valuation opportunity. Explore the numbers behind Hamilton Insurance Group's P/E valuation.
The Hamilton Insurance Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Hamilton Insurance Group valuation puzzle leaves off by spelling out what growth, margin and earnings paths would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Each narrative presents that implied fair value as a clear thesis about Hamilton Insurance Group's business that you can track over time to see how it holds up against reality.
Hamilton Insurance Group splits opinion, with one camp seeing more upside on disciplined underwriting and capital returns while the other leans toward a cooler, more cautious outlook.
Bull case: 13% undervalued
"A robust capital position and ongoing share repurchases at a discount to book value are accretive to earnings and book value per share..."
Discover why this Narrative puts Hamilton Insurance Group at 13% undervalued.
Bear case: roughly fairly valued
"Pressure on property reinsurance pricing, including at key midyear renewals, could erode risk adjusted returns over time if competition intensifies faster than Hamilton Insurance Group can tighten terms..."
Explore why this Narrative puts Hamilton Insurance Group at roughly fairly valued.
One more Hamilton Insurance Group check belongs beside the price tag
Before treating Hamilton Insurance Group’s valuation story as complete, it is worth knowing that Simply Wall St’s broader checks have flagged specific issues that could influence how you weigh the risk profile. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com