


- Northwest Bancshares has approved plans for a new corporate headquarters in Dublin, Ohio, aiming to more than double head-office staff by 2034 while adding new financial centers around Columbus to deepen its Central Ohio presence.
- The relocation concentrates Northwest Bancshares' leadership and resources in a Midwestern hub. This could reshape cost structures, talent access, and how the bank balances expansion with rising personnel expenses and classified loan risk.
- We will now look at how Northwest Bancshares' investment narrative could shift as it commits to a larger Dublin headquarters footprint.
Northwest Bancshares Investment Narrative Recap
To own Northwest Bancshares, you need to believe the bank can use its Midwestern and mid Atlantic footprint to keep building a stable deposit base while improving efficiency. The Dublin headquarters plan leans into that idea by concentrating leadership and support functions. The key near term swing factor still sits in execution on expense control and loan growth rather than the address on the front door.
The biggest operational risk remains credit quality and cost creep as the branch network grows. Rising classified loans, including exposure to multifamily construction around Columbus, already flag that concern. A larger presence in Central Ohio could amplify either outcome, whether tighter asset quality discipline or more volatility, depending on how underwriting and pricing are managed.
The most relevant backdrop to this headquarters decision is Northwest Bancshares' ongoing push into suburban markets such as Columbus and Indianapolis through new branch openings. Management is already spending to plant physical locations in higher growth corridors. Moving the corporate center to Dublin lines up with that existing build out rather than creating an entirely new direction.
That expansion sits alongside integration of the Penns Woods acquisition and continued investment in digital platforms. Your focus as a shareholder is whether the combination of a bigger Columbus footprint, acquisition cost savings and technology projects can more than offset higher personnel expenses and branch operating costs while keeping credit losses in check.
Northwest Bancshares' current analyst script points to revenues of $874.2 million and earnings of $298.6 million by 2029. These projections are based on a 10.1% yearly revenue growth assumption and an earnings increase of about $145.7 million from $152.9 million today.
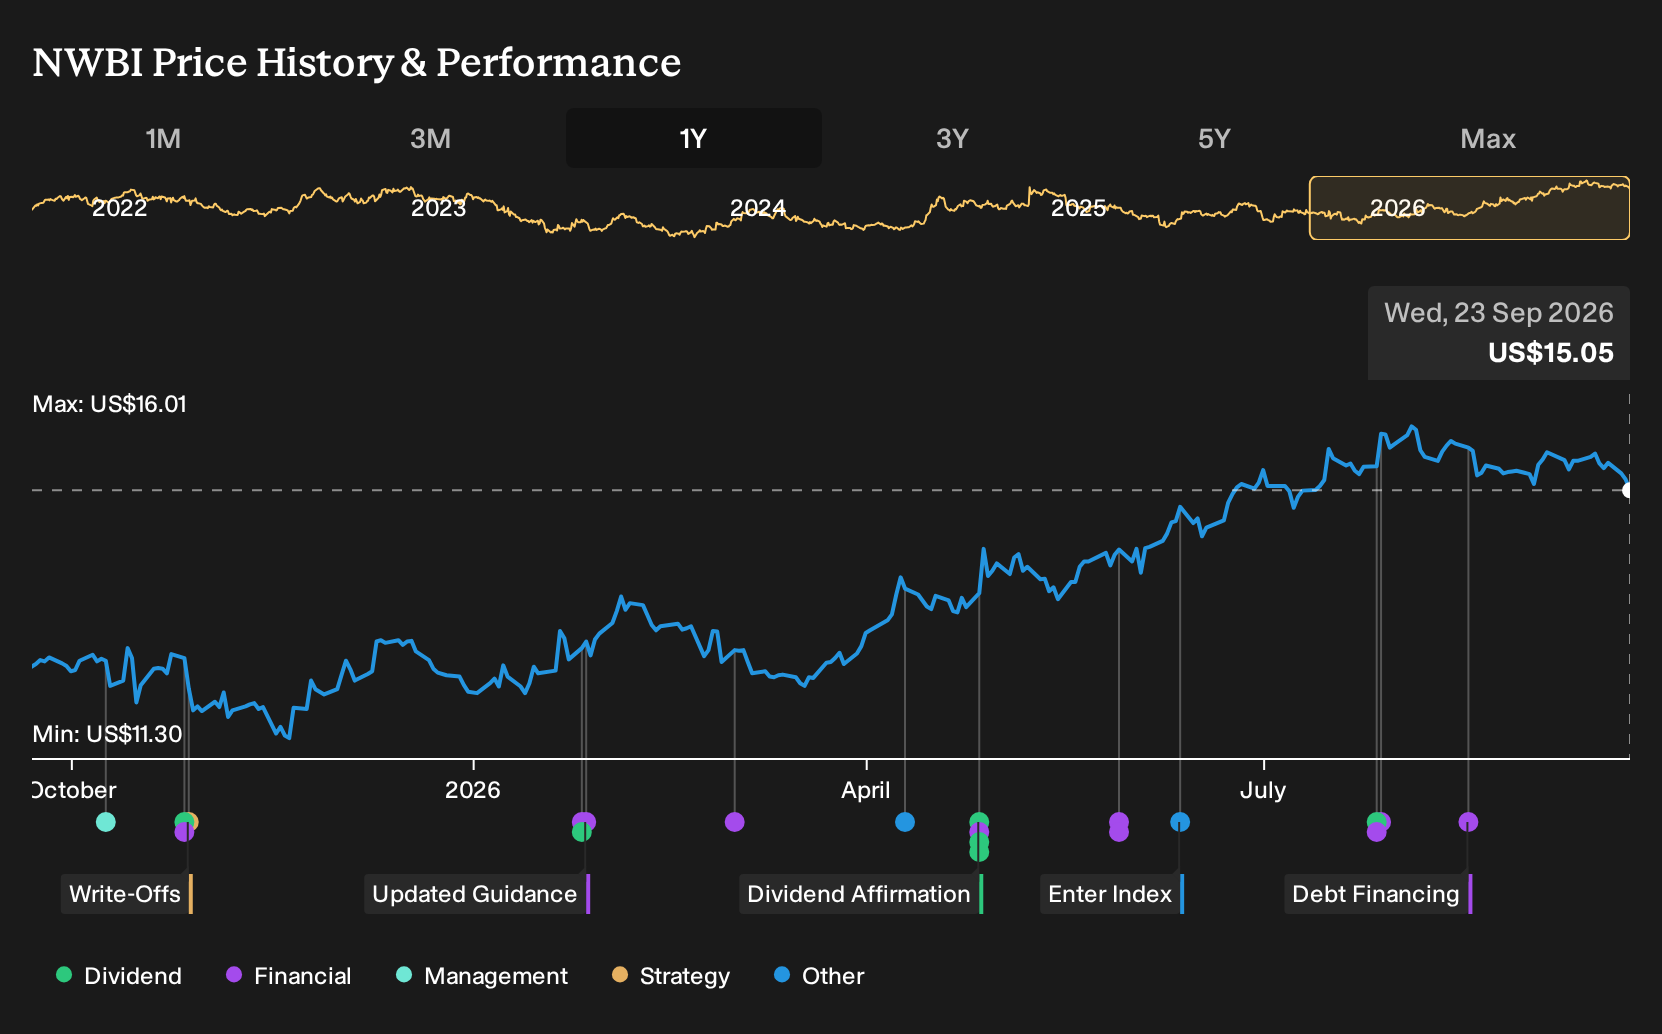
Uncover how Northwest Bancshares' fair value indicates a 5% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$15.86 to US$27.07 per share, which is a wide bracket for Northwest Bancshares. Those estimates ignore the Dublin headquarters news, so weigh them against branch expansion costs, credit risks and integration of Penns Woods. Opinions differ sharply, so explore several viewpoints before deciding where you land.
Explore another Northwest Bancshares fair value estimate, including one that suggests potential upside of as much as 80% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Northwest Bancshares research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Northwest Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northwest Bancshares' overall financial health at a glance.
Looking for more investment ideas beyond Northwest Bancshares?
If the Northwest Bancshares story has you thinking about how to balance growth with resilience, it can help to line it up against other businesses that score well on fundamentals using the Simply Wall St Screener.
- For investors who care most about financial strength and balance sheet durability, compare Northwest Bancshares with a curated 30 resilient stocks with low risk scores that keep risk indicators in check.
- If income is your priority, set Northwest Bancshares alongside a focused 7 dividend fortresses that combine higher yields with business models built for ongoing payouts.
- For those searching for solid fundamentals that may not yet be widely followed, weigh Northwest Bancshares against a hand picked 16 high quality undiscovered gems that could complement a more established bank holding.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com