


Restaurant Brands International has delivered a 5 year share price gain that many franchise investors would accept without complaint, yet the recent pullback puts fresh focus on a different question. Are today’s cash flows, and the ones investors expect over time, sufficient to support where the stock now trades?
- Over the past 5 years the stock is up 38.5%, which puts real weight on whether the underlying cash generation now lines up with that longer term move.
- Recent updates on system wide sales growth and a renewed share buyback plan can influence expectations around future free cash flow and how much of it will be returned to shareholders versus reinvested in the brands.
- Prefer to judge Restaurant Brands International on earnings? See what Restaurant Brands International's 17.9x P/E says about the price.
The stock's next move may depend on whether that recent price, after a mix of gains and setbacks, is well supported by Restaurant Brands International’s projected cash flows under a Discounted Cash Flow (DCF) view.
If you want to test the same cash flow question you are asking of Restaurant Brands International across a wider field, scan the 30 high quality undervalued stocks.
Does Restaurant Brands International Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Restaurant Brands International can return to shareholders over time. Latest twelve month free cash flow sits around $1.62b, which sets a sizeable base for the projections used in this two stage Free Cash Flow to Equity approach. Those forecasts assume growing free cash flow rather than a turnaround story, with expectations that the business continues to build on its existing cash generation.
Under those cash flow assumptions, the DCF output indicates an estimated intrinsic value that is meaningfully above the current share price of $71.66. The renewed US$1b share repurchase plan helps explain why the market is still not fully closing that gap, since buybacks can matter most when the underlying cash flows point higher than where the equity is trading. Find out what Restaurant Brands International could be worth using our Discounted Cash Flow (DCF) estimate.
The Restaurant Brands International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Discounted Cash Flow exercise stops by spelling out which paths for Restaurant Brands International's growth, margins and earnings would need to hold for the shares to be worth materially more or materially less than today’s price, and they sit on Simply Wall St's Community page. Each is built around a specific fair value view and the assumptions behind it, so you can line those expectations up against actual results as they come through.
One of the top community narratives on Restaurant Brands International: 17% undervalued
"Rapid international expansion through a largely franchise-led model, including the plan for about 1,800 net new restaurants by 2028 with around 1,100 net adds in international markets and more than 200 net new Burger King China units backed by improving unit economics and double digit comps there, continues to support recurring, capital light royalty revenue and the potential for higher system-wide sales and earnings…"
Discover why this Narrative puts Restaurant Brands International at 17% undervalued.
One More Question For Restaurant Brands International Before You Decide
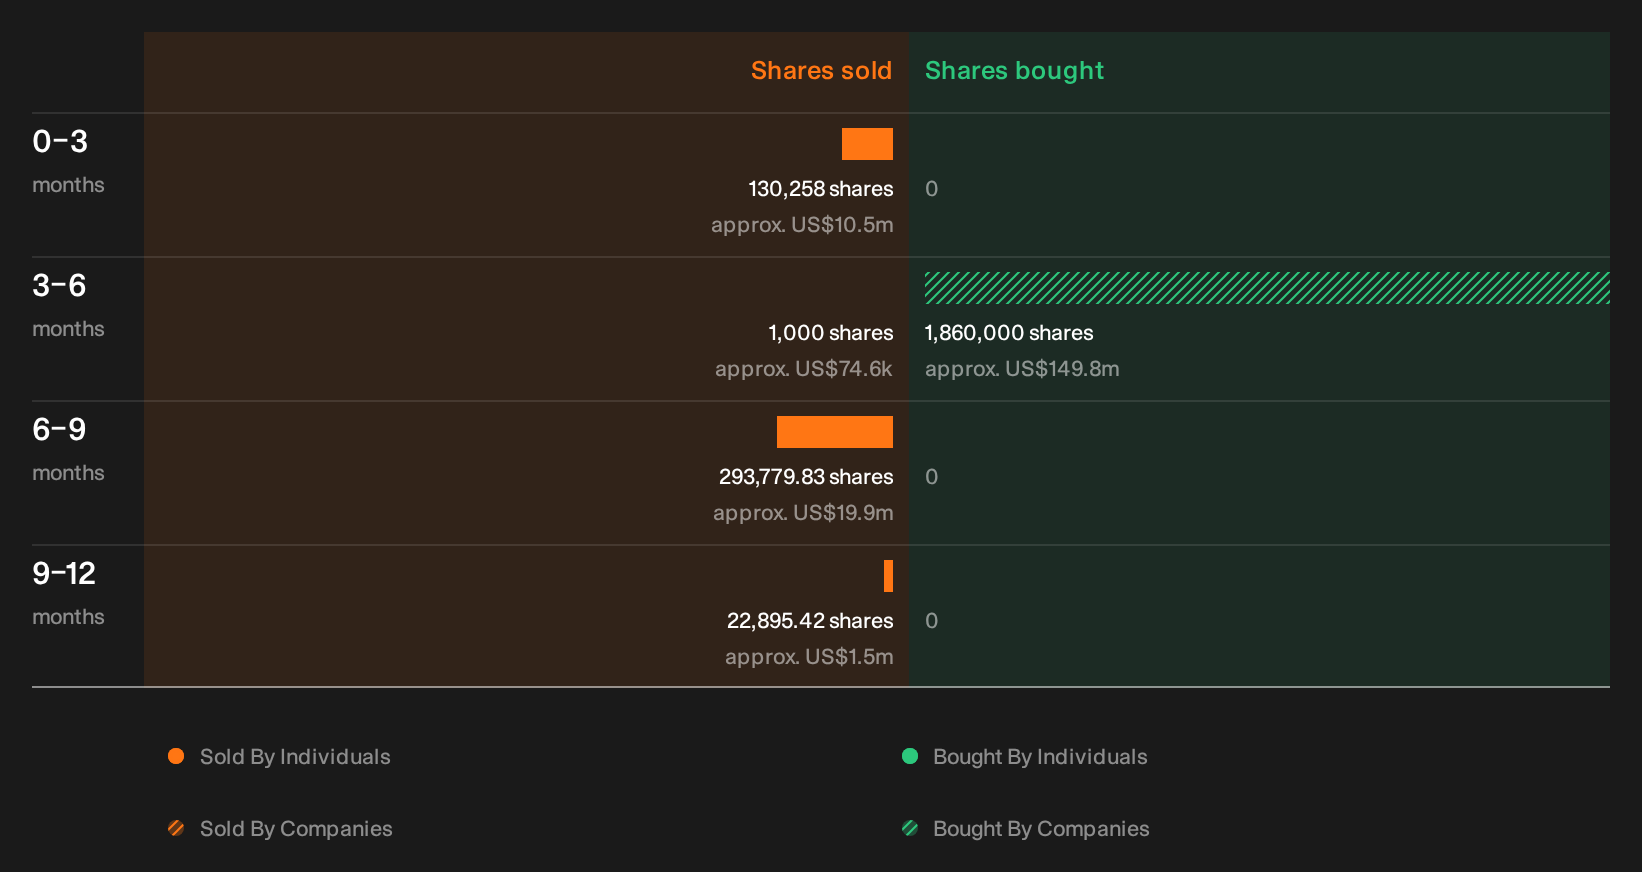
Before acting on any view of Restaurant Brands International, it is worth knowing that recent trading by people inside the business has been picked up by our checks, with who sold, how much and what it might signal left for you to review. See the recent insider selling flagged for Restaurant Brands International.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com