


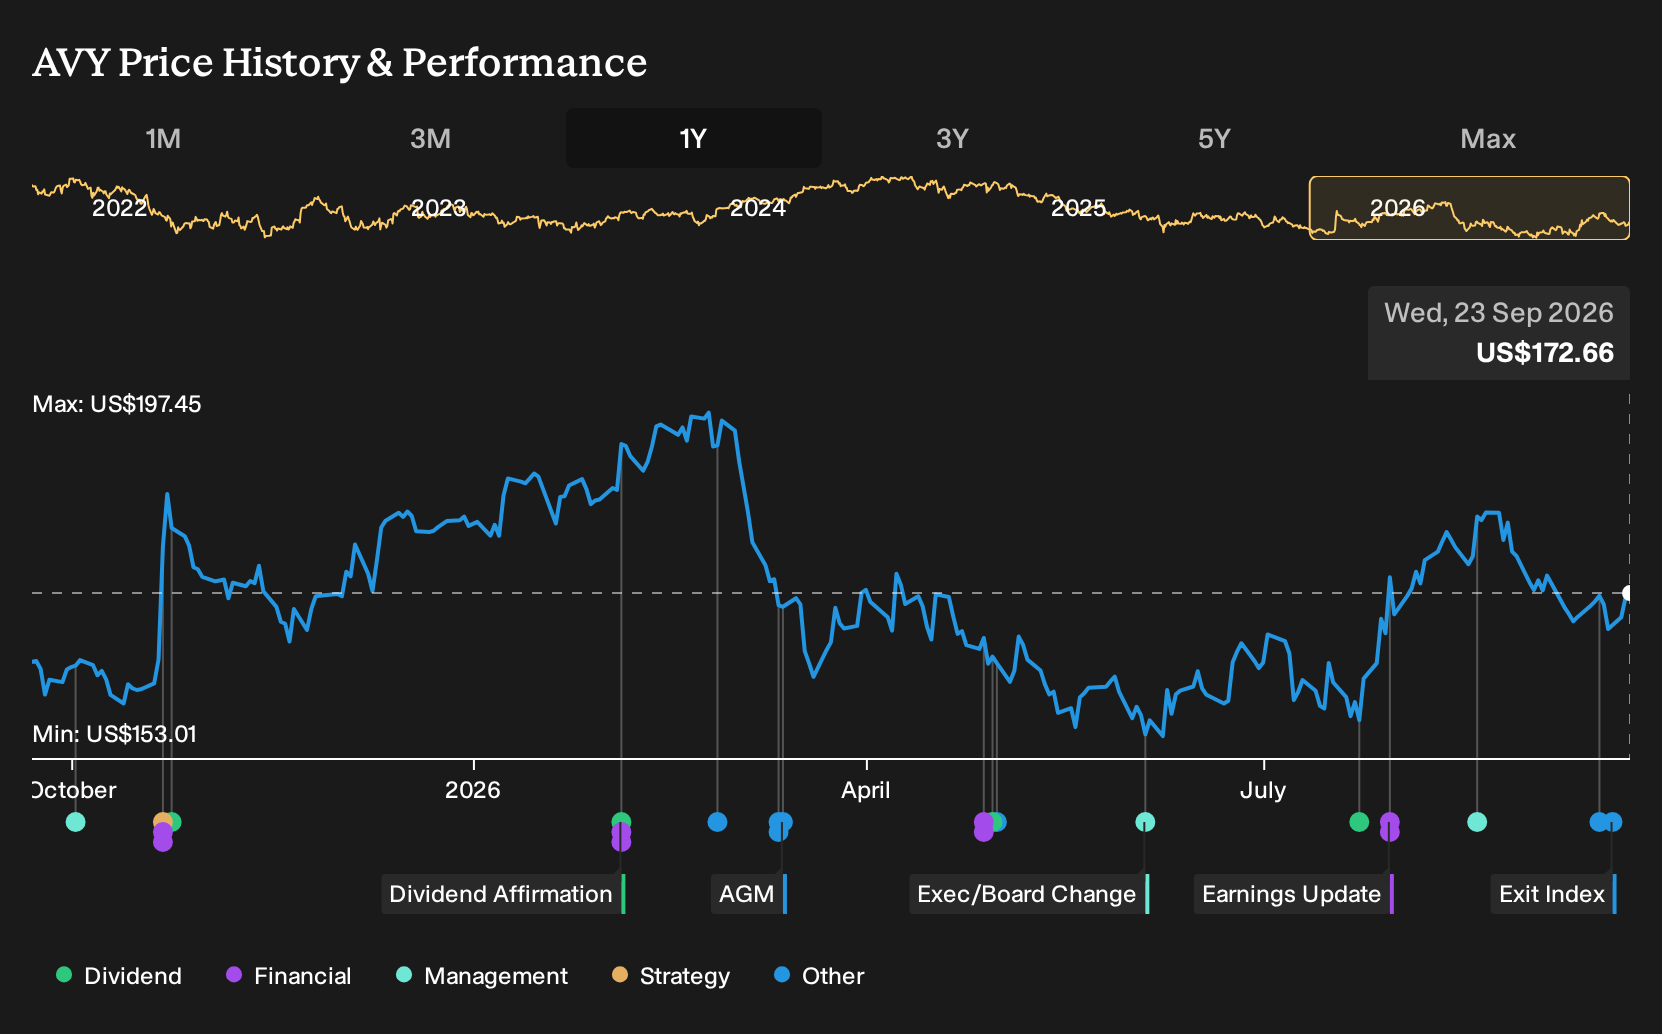
- Avery Dennison was removed from the FTSE All-World Index (USD) on 19 September 2026, following a recent investor call focused on its high-value category portfolio and broader industry trends.
- This exit from a major global benchmark puts Avery Dennison’s fundamentals into sharper focus, particularly the balance between index-driven ownership and demand for its higher value labeling and RFID solutions.
- We will now look at how Avery Dennison’s index removal could reshape its investment narrative, which is built around higher value labeling growth.
Scan how other labeling and packaging specialists are handling similar index shifts and capital flows by reviewing the curated list of solid balance sheet and fundamentals (23 results) that can better withstand benchmark turnover pressure.
Avery Dennison Investment Narrative Recap
To be a shareholder in Avery Dennison, you need to believe its higher value labeling and RFID programs can gradually offset sluggish organic growth in the core materials operations. The recent FTSE All World exit is more about technical flows than day to day execution. The more immediate swing factor remains how quickly Intelligent Labels and other premium categories gain share.
The biggest operational watchpoint is still the unwind of customer inventory prebuys and the move from raw material deflation to high single digit inflation in the second half of 2026. If end market demand or pricing actions disappoint, that reversal could weigh more on earnings than any impact from index related selling.
The special investor call on 16 September that focused on Avery Dennison’s high value category portfolio is the announcement that most links to this index change. Management clearly wanted investors focused on the mix shift toward Intelligent Labels, Specialty and Durable Labels, Embelex, Vestcom and architectural films, rather than on benchmark status.
For you, that call matters because it goes straight to the key catalysts and risks. Execution on RFID rollouts and higher value materials, supported by pricing, needs to offset revenue growth of 3.3% per year, rising raw material and wage costs and a high level of debt. If those programs scale as planned, the operating story can stay intact even with some pressure from benchmark turnover.
Avery Dennison Consensus Growth and Valuation Frame
Avery Dennison's narrative projects US$10.2b revenue and US$939.6m earnings by 2029. This assumes 3.2% yearly revenue growth and an earnings increase of about US$234.7m from current earnings of US$704.9m.
Uncover why Avery Dennison's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$201.8 to US$366.7 per share, so opinions on Avery Dennison are already wide apart before the FTSE All World exit is factored in. Layer in the risk from EPS headwinds as customer prebuys unwind, and you have a strong case for comparing several alternative scenarios yourself.
Explore another Avery Dennison fair value estimate, including one that suggests potential upside of up to 112% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Avery Dennison research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avery Dennison. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avery Dennison's overall financial health at a glance.
Looking for more investment ideas beyond Avery Dennison?
Once you have formed a view on Avery Dennison, it can help to benchmark that thesis against other businesses with different balance sheet strength, dividend profiles, and valuation setups using the Simply Wall St Screener.
- If capital preservation is high on your list, consider reviewing a 31 resilient stocks with low risk scores that may offer steadier fundamentals and lower volatility than more speculative options.
- For investors hunting for quality at a reasonable price, scan a 30 high quality undervalued stocks that filters for companies with solid cash flows and support from intrinsic value estimates.
- Income focused readers can compare Avery Dennison with a 7 dividend fortresses that concentrates on higher yield payouts with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com